
349 lines
13 KiB
Markdown
349 lines
13 KiB
Markdown
|
|
> Name
|
|
|
|
基于转折点的RSI背离策略Pivot-based-RSI-Divergence-Strategy
|
|
|
|
> Author
|
|
|
|
ChaoZhang
|
|
|
|
> Strategy Description
|
|
|
|
|
|
[trans]
|
|
|
|
## 概述
|
|
|
|
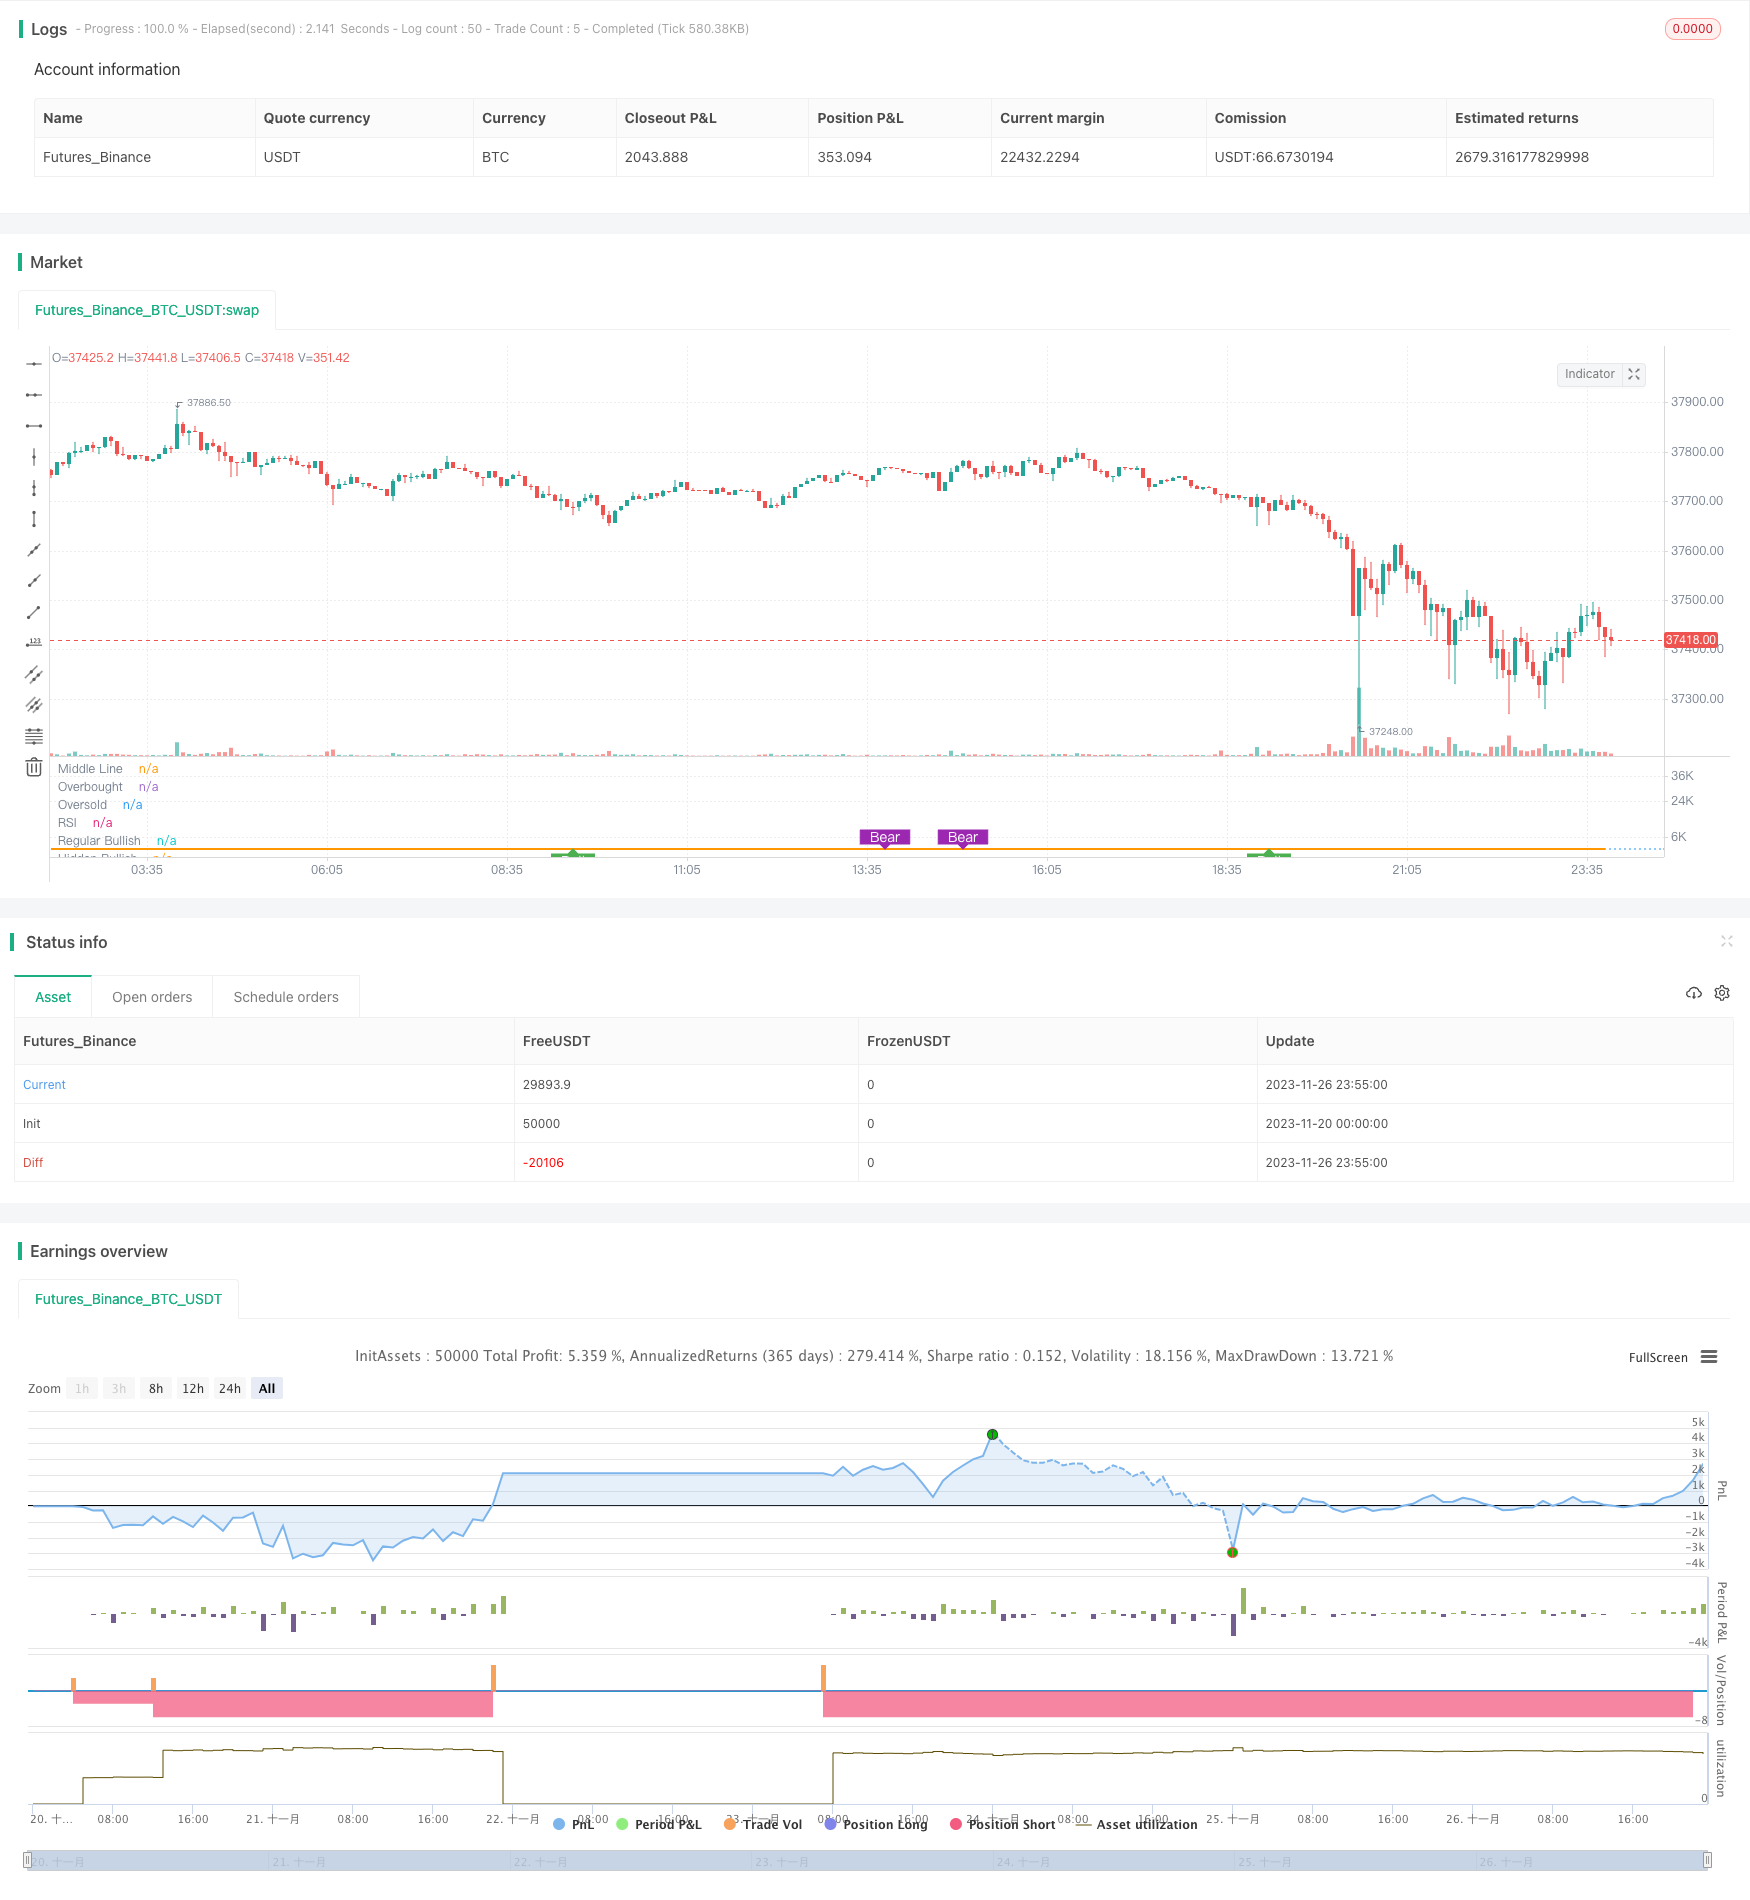
该策略名为“基于转折点的RSI背离策略”(Pivot-based RSI Divergence Strategy)。它利用RSI指标在不同周期上的背离来判断买入卖出点,并在此基础上增加了长线RSI作为过滤条件,从而提高策略的稳定性。
|
|
|
|
## 策略原理
|
|
|
|
该策略主要判断短线RSI(如5日RSI)与价格出现“隐藏型多头背离”或“常规型多头背离”时机会买入;出现“隐藏型空头背离”或“常规型空头背离”时机会卖出。
|
|
|
|
所谓“常规型多头背离”是指:价格创新低而RSI未创新低;“隐藏型多头背离”则相反,价格未创新低而RSI创新低。两者定义中的“新低”和“新高”是相对于一定滚动窗口的历史极值而言的。
|
|
|
|
此外,策略还引入长线RSI(如50日RSI)作为过滤条件。只有当长RSI大于50时,才考虑买入信号;当长RSI小于30时,考虑止损或止盈退出。
|
|
|
|
## 策略优势
|
|
|
|
该策略最大的优势在于同时利用短线RSI的背离信号和长线RSI的过滤,能够在一定程度上避免被套和错过行情。具体来说,主要具有以下几个优势:
|
|
|
|
1. 短线RSI背离信号能提前判断价格反转机会,及时捕捉行情转折点;
|
|
2. 长线RSI过滤条件避免在趋势不确定时盲目做多;
|
|
3. 多种类型的止盈方式,分批止盈有利于减少风险;
|
|
4. Pyramiding机制允许加仓,进一步提高盈利空间。
|
|
|
|
## 策略风险
|
|
|
|
该策略也存在一些风险需要注意:
|
|
|
|
1. RSI背离并不总是有效,有可能出现假信号;
|
|
2. 加仓后风险会放大。如果判断错误,亏损会加速扩大;
|
|
3. 止盈设置不当也可能导致过早止盈或盈利不足。
|
|
|
|
对应风险管理措施包括:合理设定止损止盈条件、控制每个头寸大小、分批减仓以平滑盈亏曲线等。
|
|
|
|
## 优化方向
|
|
|
|
该策略还存在进一步优化的空间:
|
|
|
|
1. RSI参数可以进一步优化,找到最佳参数组合;
|
|
2. 可以测试其他指标的背离信号,如MACD、KD等;
|
|
3. 可以在特定品种(如原油、贵金属等)上专门优化参数,提高适应性。
|
|
|
|
## 总结
|
|
|
|
本策略综合运用短线与长线RSI的多空背离信号,在控制风险的同时,提高盈利效率。它体现了量化交易策略设计的多项原则,包括何时入场、何时离场、分批建仓减仓、设置止损止盈等。这是一个可供参考借鉴的RSI背离策略范例。
|
|
|
|
||
|
|
|
|
|
|
## Overview
|
|
|
|
This strategy is called "Pivot-based RSI Divergence Strategy". It uses the divergence between RSI indicators at different cycles to determine entry and exit points, and adds long-term RSI as a filter condition to improve the stability of the strategy.
|
|
|
|
## Strategy Logic
|
|
|
|
The strategy mainly judges the opportunity to buy when there is a "hidden bullish divergence" or "regular bullish divergence" between the short-term RSI (such as 5-day RSI) and price; and to sell when there is a "hidden bearish divergence" or "regular bearish divergence".
|
|
|
|
A "regular bullish divergence" means that the price makes a new low while the RSI does not make a new low; a "hidden bullish divergence" is the opposite, the price does not make a new low while the RSI makes a new low. The "new lows" and "new highs" referred to in both definitions are relative to historical extremes over a certain rolling window.
|
|
|
|
In addition, the strategy also introduces long-term RSI (such as 50-day RSI) as a filter condition. It only considers buy signals when the long RSI is greater than 50; and considers stop loss or take profit exit when the long RSI is less than 30.
|
|
|
|
## Advantages
|
|
|
|
The biggest advantage of this strategy is that it utilizes both the RSI divergence signals on the short-term and the filter of long-term RSI, which can avoid being trapped and missing trends to some extent. Specifically, it has the following main advantages:
|
|
|
|
1. The short-term RSI divergence signal can give early judgment of price reversal opportunities and timely capture turning points;
|
|
2. The long-term RSI filter avoids going long blindly when the trend is uncertain;
|
|
3. Multiple types of take profit methods and partial profit-taking help reduce risk;
|
|
4. The pyramiding mechanism allows adding positions and further expands profit potential.
|
|
|
|
## Risks
|
|
|
|
The strategy also has some risks to note:
|
|
|
|
1. RSI divergences are not always valid and there could be false signals;
|
|
2. Risks amplify after pyramiding. Losses could accelerate if the judgment is wrong;
|
|
3. Improper take profit settings may also lead to premature profit-taking or insufficient profits.
|
|
|
|
Corresponding risk management measures include: reasonably setting stop loss/take profit conditions, controlling position sizing, partial profit-taking to smooth the equity curve, etc.
|
|
|
|
## Optimization Directions
|
|
|
|
There is room for further optimization of the strategy:
|
|
|
|
1. RSI parameters can be further optimized to find the best combination;
|
|
2. Divergence signals of other indicators such as MACD and KD can be tested;
|
|
3. Parameters can be specifically optimized on certain products (such as crude oil, precious metals, etc.) to improve adaptability.
|
|
|
|
## Summary
|
|
|
|
This strategy combines the long/short RSI divergence signals of short-term and long-term to improve profitability while controlling risks. It reflects multiple principles in quantitative strategy design, including when to enter, when to exit, partial profit-taking, stop loss/take profit setting, etc. This is an exemplary RSI divergence strategy for reference.
|
|
|
|
[/trans]
|
|
|
|
> Strategy Arguments
|
|
|
|
|
|
|
|
|Argument|Default|Description|
|
|
|----|----|----|
|
|
|v_input_1|5|RSI Period|
|
|
|v_input_2|50|Long RSI Period|
|
|
|v_input_3_close|0|RSI Source: close|high|low|open|hl2|hlc3|hlcc4|ohlc4|
|
|
|v_input_4|3|Pivot Lookback Right|
|
|
|v_input_5|true|Pivot Lookback Left|
|
|
|v_input_6|75|Take Profit at RSI Level|
|
|
|v_input_7|false|Stop Loss%(if checked 8% rule applied)|
|
|
|v_input_8|60|Max of Lookback Range|
|
|
|v_input_9|5|Min of Lookback Range|
|
|
|v_input_10|true|Plot Bullish|
|
|
|v_input_11|true|Plot Hidden Bullish|
|
|
|v_input_12|true|Plot Bearish|
|
|
|v_input_13|false|Plot Hidden Bearish|
|
|
|
|
|
|
> Source (PineScript)
|
|
|
|
``` pinescript
|
|
/*backtest
|
|
start: 2023-11-20 00:00:00
|
|
end: 2023-11-27 00:00:00
|
|
period: 5m
|
|
basePeriod: 1m
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
|
*/
|
|
|
|
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
|
|
// © mohanee
|
|
|
|
//@version=4
|
|
|
|
//GOOGL setting 5 ,50 close, 3 , 1 profitLevel at 75 and No stop Loss shows win rate 99.03 % profit factor 5830.152
|
|
|
|
strategy(title="RSI5_50 with Divergence", overlay=false,pyramiding=2, default_qty_type=strategy.fixed, default_qty_value=3, initial_capital=10000, currency=currency.USD)
|
|
|
|
len = input(title="RSI Period", minval=1, defval=5)
|
|
longRSILen = input(title="Long RSI Period", minval=10, defval=50)
|
|
src = input(title="RSI Source", defval=close)
|
|
lbR = input(title="Pivot Lookback Right", defval=3)
|
|
lbL = input(title="Pivot Lookback Left", defval=1)
|
|
takeProfitRSILevel = input(title="Take Profit at RSI Level", minval=50, defval=75)
|
|
stopLoss = input(title="Stop Loss%(if checked 8% rule applied)", defval=false)
|
|
|
|
shortTermRSI = rsi(close,len)
|
|
longTermRSI = rsi(close,longRSILen)
|
|
|
|
rangeUpper = input(title="Max of Lookback Range", defval=60)
|
|
rangeLower = input(title="Min of Lookback Range", defval=5)
|
|
plotBull = input(title="Plot Bullish", defval=true)
|
|
plotHiddenBull = input(title="Plot Hidden Bullish", defval=true)
|
|
plotBear = input(title="Plot Bearish", defval=true)
|
|
plotHiddenBear = input(title="Plot Hidden Bearish", defval=false)
|
|
|
|
|
|
bearColor = color.purple
|
|
bullColor = color.green
|
|
hiddenBullColor = color.new(color.green, 80)
|
|
hiddenBearColor = color.new(color.red, 80)
|
|
textColor = color.white
|
|
noneColor = color.new(color.white, 100)
|
|
|
|
|
|
|
|
plot(shortTermRSI, title="RSI", linewidth=2, color=#8D1699)
|
|
plot(longTermRSI, title="longTermRSI", linewidth=2, color=color.orange)
|
|
|
|
hline(50, title="Middle Line", linestyle=hline.style_dotted)
|
|
obLevel = hline(70, title="Overbought", linestyle=hline.style_dotted)
|
|
osLevel = hline(30, title="Oversold", linestyle=hline.style_dotted)
|
|
fill(obLevel, osLevel, title="Background", color=longTermRSI >=50 ? color.green:color.purple, transp=65) // longTermRSI >=50
|
|
|
|
plFound = na(pivotlow(shortTermRSI, lbL, lbR)) ? false : true
|
|
phFound = na(pivothigh(shortTermRSI, lbL, lbR)) ? false : true
|
|
|
|
_inRange(cond) =>
|
|
bars = barssince(cond == true)
|
|
rangeLower <= bars and bars <= rangeUpper
|
|
|
|
//------------------------------------------------------------------------------
|
|
// Regular Bullish
|
|
|
|
// shortTermRSI: Higher Low
|
|
oscHL = shortTermRSI[lbR] > valuewhen(plFound, shortTermRSI[lbR], 1) and _inRange(plFound[1])
|
|
|
|
// Price: Lower Low
|
|
priceLL = low[lbR] < valuewhen(plFound, low[lbR], 1)
|
|
|
|
bullCond = plotBull and priceLL and oscHL and plFound
|
|
|
|
plot(
|
|
plFound ? shortTermRSI[lbR] : na,
|
|
offset=-lbR,
|
|
title="Regular Bullish",
|
|
linewidth=2,
|
|
color=(bullCond ? bullColor : noneColor),
|
|
transp=0
|
|
)
|
|
|
|
|
|
plotshape(
|
|
bullCond ? shortTermRSI[lbR] : na,
|
|
offset=-lbR,
|
|
title="Regular Bullish Label",
|
|
text=" Bull ",
|
|
style=shape.labelup,
|
|
location=location.absolute,
|
|
color=bullColor,
|
|
textcolor=textColor,
|
|
transp=0
|
|
)
|
|
|
|
//------------------------------------------------------------------------------
|
|
// Hidden Bullish
|
|
|
|
// shortTermRSI: Lower Low
|
|
oscLL = shortTermRSI[lbR] < valuewhen(plFound, shortTermRSI[lbR], 1) and _inRange(plFound[1])
|
|
|
|
// Price: Higher Low
|
|
priceHL = low[lbR] > valuewhen(plFound, low[lbR], 1)
|
|
|
|
hiddenBullCond = plotHiddenBull and priceHL and oscLL and plFound
|
|
|
|
plot(
|
|
plFound ? shortTermRSI[lbR] : na,
|
|
offset=-lbR,
|
|
title="Hidden Bullish",
|
|
linewidth=2,
|
|
color=(hiddenBullCond ? hiddenBullColor : noneColor),
|
|
transp=0
|
|
)
|
|
|
|
plotshape(
|
|
hiddenBullCond ? shortTermRSI[lbR] : na,
|
|
offset=-lbR,
|
|
title="Hidden Bullish Label",
|
|
text=" H Bull ",
|
|
style=shape.labelup,
|
|
location=location.absolute,
|
|
color=bullColor,
|
|
textcolor=textColor,
|
|
transp=0
|
|
)
|
|
|
|
longCondition= longTermRSI >=50 and ( (bullCond or hiddenBullCond ) ) or (strategy.position_size>0 and crossover(shortTermRSI,20) )
|
|
//last condition above is to leg in if you are already in the Long trade,
|
|
|
|
|
|
strategy.entry(id="RSIDivLE", long=true, when=longCondition)
|
|
|
|
|
|
//------------------------------------------------------------------------------
|
|
// Regular Bearish
|
|
|
|
// shortTermRSI: Lower High
|
|
oscLH = shortTermRSI[lbR] < valuewhen(phFound, shortTermRSI[lbR], 1) and _inRange(phFound[1])
|
|
|
|
// Price: Higher High
|
|
priceHH = high[lbR] > valuewhen(phFound, high[lbR], 1)
|
|
|
|
bearCond = plotBear and priceHH and oscLH and phFound
|
|
|
|
plot(
|
|
phFound ? shortTermRSI[lbR] : na,
|
|
offset=-lbR,
|
|
title="Regular Bearish",
|
|
linewidth=2,
|
|
color=(bearCond ? bearColor : noneColor),
|
|
transp=0
|
|
)
|
|
|
|
plotshape(
|
|
bearCond ? shortTermRSI[lbR] : na,
|
|
offset=-lbR,
|
|
title="Regular Bearish Label",
|
|
text=" Bear ",
|
|
style=shape.labeldown,
|
|
location=location.absolute,
|
|
color=bearColor,
|
|
textcolor=textColor,
|
|
transp=0
|
|
)
|
|
|
|
//------------------------------------------------------------------------------
|
|
// Hidden Bearish
|
|
|
|
// shortTermRSI: Higher High
|
|
oscHH = shortTermRSI[lbR] > valuewhen(phFound, shortTermRSI[lbR], 1) and _inRange(phFound[1])
|
|
|
|
// Price: Lower High
|
|
priceLH = high[lbR] < valuewhen(phFound, high[lbR], 1)
|
|
|
|
hiddenBearCond = plotHiddenBear and priceLH and oscHH and phFound
|
|
|
|
plot(
|
|
phFound ? shortTermRSI[lbR] : na,
|
|
offset=-lbR,
|
|
title="Hidden Bearish",
|
|
linewidth=2,
|
|
color=(hiddenBearCond ? hiddenBearColor : noneColor),
|
|
transp=0
|
|
)
|
|
|
|
plotshape(
|
|
hiddenBearCond ? shortTermRSI[lbR] : na,
|
|
offset=-lbR,
|
|
title="Hidden Bearish Label",
|
|
text=" H Bear ",
|
|
style=shape.labeldown,
|
|
location=location.absolute,
|
|
color=bearColor,
|
|
textcolor=textColor,
|
|
transp=0
|
|
)
|
|
|
|
|
|
//calculate stop Loss
|
|
stopLossVal = stopLoss==true ? ( strategy.position_avg_price - (strategy.position_avg_price*0.08) ) : 0
|
|
|
|
//partial profit
|
|
strategy.close(id="RSIDivLE", comment="TP1", qty=strategy.position_size*3/4, when=strategy.position_size>0 and (longTermRSI>=takeProfitRSILevel or crossover(longTermRSI,90)))
|
|
strategy.close(id="RSIDivLE",comment="TP2", qty=strategy.position_size*3/4 , when=crossover(longTermRSI,70))
|
|
strategy.close(id="RSIDivLE",comment="TP3", qty=strategy.position_size/2, when=crossover(longTermRSI,65))
|
|
strategy.close(id="RSIDivLE",comment="TP4", qty=strategy.position_size/2 , when=crossover(longTermRSI,60))
|
|
|
|
//close the whole position when stoploss hits or longTermRSI goes below 30
|
|
strategy.close(id="RSIDivLE",comment="Exit", when=crossunder(longTermRSI,30) or close<stopLossVal)
|
|
|
|
|
|
```
|
|
|
|
> Detail
|
|
|
|
https://www.fmz.com/strategy/433539
|
|
|
|
> Last Modified
|
|
|
|
2023-11-28 13:43:05
|