
195 lines
7.2 KiB
Markdown
195 lines
7.2 KiB
Markdown
|
|
> Name
|
|
|
|
反向K线突破短线交易策略Reversal-Short-term-Breakout-Trading-Strategy
|
|
|
|
> Author
|
|
|
|
ChaoZhang
|
|
|
|
> Strategy Description
|
|
|
|
|
|
[trans]
|
|
|
|
## 概述
|
|
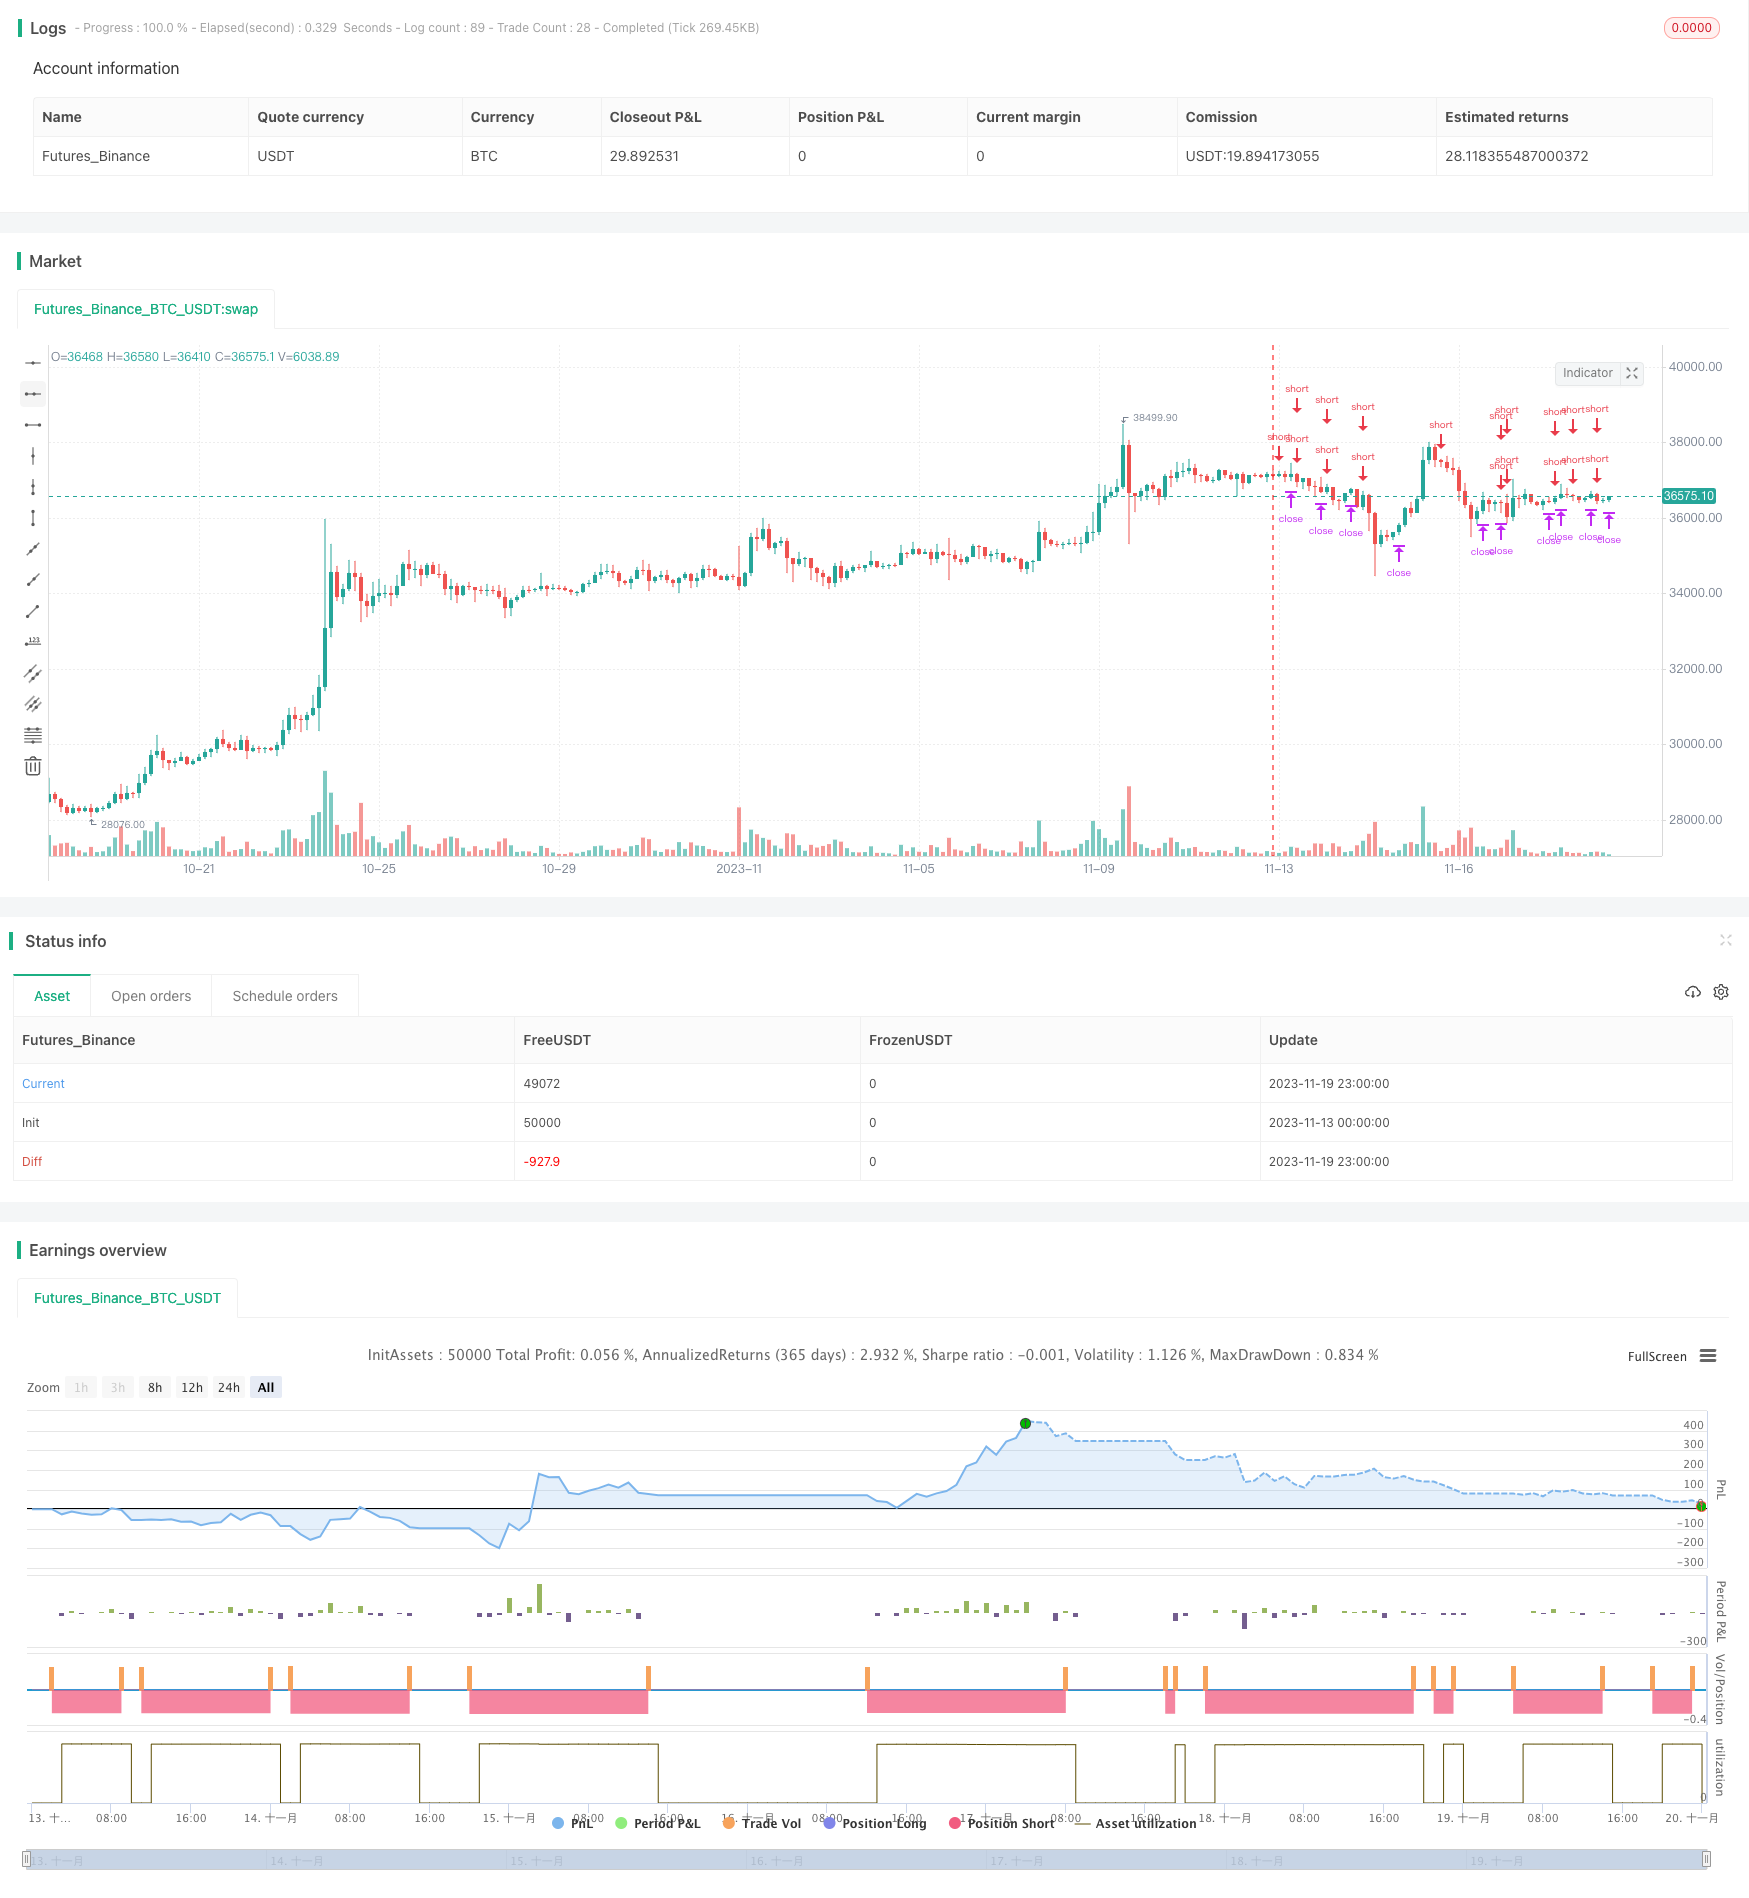
该策略用于捕捉短线反转交易机会。它会在连续N根K线都是上涨后开仓做空,在连续M根K线都是下跌后平仓。同时,该策略加入了时间段限制和止损止盈功能。
|
|
|
|
## 原理
|
|
1. 输入参数:连续上涨K线数N,连续下跌K线数M
|
|
2. 定义逻辑:
|
|
- ups统计上涨K线数,price>price[1]则+1,否则reset为0
|
|
- dns统计下跌K线数,price<price[1]则+1,否则reset为0
|
|
3. 入场:当ups≥N时,做空;当dns≥M时,平仓
|
|
4. 出场:固定止损止盈或时间段结束
|
|
|
|
## 优势
|
|
1. 捕捉反转交易机会,适合短线操作
|
|
2. 可灵活设置交易时间段,适应不同交易计划
|
|
3. 内置止损止盈功能,有助于风险控制
|
|
|
|
## 风险
|
|
1. 短线反转不一定成功,可能再次反转导致损失
|
|
2. 需要合理设置参数N、M,过大或过小都不利
|
|
3. 停止时刻设置不当可能无法及时止损
|
|
|
|
## 优化方向
|
|
1. 结合趋势指标避免逆势操作
|
|
2. 动态调整参数N、M
|
|
3. 优化止损机制
|
|
|
|
## 总结
|
|
该策略通过统计K线形态来捕捉短线交易机会。设置合理的参数以及风控措施对于获得稳定收益至关重要。通过进一步结合趋势判断及动态调整参数,可望获得更好的效果。
|
|
|
|
||
|
|
|
|
## Overview
|
|
This strategy aims to capture short-term reversal trading opportunities. It will open short position after N consecutive up-bars and close position after M consecutive down-bars. It also incorporates time frame filter and stop loss/take profit features.
|
|
|
|
## Logic
|
|
1. Input parameters: Number of consecutive up-bars N, consecutive down-bars M
|
|
2. Definition:
|
|
- ups counts number of up-bars, price>price[1] then +1, otherwise reset to 0
|
|
- dns counts number of down-bars, price<price[1] then +1, otherwise reset to 0
|
|
3. Entry: short when ups≥N; close position when dns≥M
|
|
4. Exit: fixed stop loss/take profit or end of time frame
|
|
|
|
## Pros
|
|
1. Capture reversal trading chances, suitable for short-term trading
|
|
2. Flexible time frame setting catering to different trading plans
|
|
3. Embedded stop loss/take profit facilitating risk management
|
|
|
|
## Risks
|
|
1. Short-term reversal may fail and reverse again leading to loss
|
|
2. Reasonable N, M parameters needed, too large or small unfavourable
|
|
3. Improper stop time may unable to stop loss in time
|
|
|
|
## Optimization Directions
|
|
1. Combine with trend indicator to avoid against trend trades
|
|
2. Dynamic adjustment of parameters N, M
|
|
3. Optimize stop loss mechanism
|
|
|
|
## Conclusion
|
|
The strategy captures short-term trading opportunities through statistical K-line patterns. Reasonable parameter tuning and risk control measures are crucial for steady profits. Further improvements on combining trend analysis and dynamic parameter adjustment may lead to even better performance.
|
|
|
|
[/trans]
|
|
|
|
> Strategy Arguments
|
|
|
|
|
|
|
|
|Argument|Default|Description|
|
|
|----|----|----|
|
|
|v_input_1|true|Consecutive Bars Up|
|
|
|v_input_2|true|Consecutive Bars Down|
|
|
|v_input_3|timestamp(2021-01-01T00:00:00)|Backtesting Start Date|
|
|
|v_input_4|timestamp(2021-12-31T00:00:00)|Backtesting End Date|
|
|
|v_input_5||Time Frame To Enter Trades|
|
|
|v_input_6|false|Enable Close Trade At End Of Time Frame|
|
|
|v_input_7|false|Enable Take Profit & Stop Loss|
|
|
|v_input_8|5|Stop Loss Ticks|
|
|
|v_input_9|10|Take Profit Ticks|
|
|
|v_input_10||Long Entry message|
|
|
|v_input_11||Short Entry message|
|
|
|v_input_12||Close Long message|
|
|
|v_input_13||Close Short message|
|
|
|v_input_14||Take Profit message|
|
|
|v_input_15||Stop Loss message|
|
|
|
|
|
|
> Source (PineScript)
|
|
|
|
``` pinescript
|
|
/*backtest
|
|
start: 2023-11-13 00:00:00
|
|
end: 2023-11-20 00:00:00
|
|
period: 3h
|
|
basePeriod: 15m
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
|
*/
|
|
|
|
//@version=4
|
|
|
|
// Strategy
|
|
strategy("Up/Down Short Strategy", overlay=true, initial_capital = 10000, default_qty_value = 10000, default_qty_type = strategy.cash)
|
|
|
|
// There will be no short entries, only exits from long.
|
|
strategy.risk.allow_entry_in(strategy.direction.short)
|
|
|
|
consecutiveBarsUp = input(1, title='Consecutive Bars Up')
|
|
consecutiveBarsDown = input(1, title='Consecutive Bars Down')
|
|
|
|
price = close
|
|
|
|
ups = 0.0
|
|
ups := price > price[1] ? nz(ups[1]) + 1 : 0
|
|
|
|
dns = 0.0
|
|
dns := price < price[1] ? nz(dns[1]) + 1 : 0
|
|
|
|
// Strategy Backtesting
|
|
startDate = input(timestamp("2021-01-01T00:00:00"), type = input.time, title='Backtesting Start Date')
|
|
finishDate = input(timestamp("2021-12-31T00:00:00"), type = input.time, title='Backtesting End Date')
|
|
|
|
time_cond = true
|
|
|
|
//Time Restriction Settings
|
|
startendtime = input("", title='Time Frame To Enter Trades')
|
|
enableclose = input(false, title='Enable Close Trade At End Of Time Frame')
|
|
timetobuy = (time(timeframe.period, startendtime))
|
|
timetoclose = na(time(timeframe.period, startendtime))
|
|
|
|
// Stop Loss & Take Profit Tick Based
|
|
enablesltp = input(false, title='Enable Take Profit & Stop Loss')
|
|
stopTick = input(5.0, title='Stop Loss Ticks', type=input.float) / 100
|
|
takeTick = input(10.0, title='Take Profit Ticks', type=input.float) / 100
|
|
|
|
longStop = strategy.position_avg_price - stopTick
|
|
shortStop = strategy.position_avg_price + stopTick
|
|
shortTake = strategy.position_avg_price - takeTick
|
|
longTake = strategy.position_avg_price + takeTick
|
|
|
|
plot(strategy.position_size > 0 and enablesltp ? longStop : na, style=plot.style_linebr, color=color.red, linewidth=1, title="Long Fixed SL")
|
|
plot(strategy.position_size < 0 and enablesltp ? shortStop : na, style=plot.style_linebr, color=color.red, linewidth=1, title="Short Fixed SL")
|
|
plot(strategy.position_size > 0 and enablesltp ? longTake : na, style=plot.style_linebr, color=color.green, linewidth=1, title="Long Take Profit")
|
|
plot(strategy.position_size < 0 and enablesltp ? shortTake : na, style=plot.style_linebr, color=color.green, linewidth=1, title="Short Take Profit")
|
|
|
|
// Alert messages
|
|
message_enterlong = input("", title="Long Entry message")
|
|
message_entershort = input("", title="Short Entry message")
|
|
message_closelong = input("", title="Close Long message")
|
|
message_closeshort = input("", title="Close Short message")
|
|
message_takeprofit = input("", title="Take Profit message")
|
|
message_stoploss = input("", title="Stop Loss message")
|
|
|
|
// Strategy Execution
|
|
if (ups >= consecutiveBarsUp) and time_cond and timetobuy
|
|
strategy.entry("Long", strategy.long, stop = high + syminfo.mintick, alert_message = message_enterlong)
|
|
|
|
if (dns >= consecutiveBarsDown) and time_cond and timetobuy
|
|
strategy.entry("Short", strategy.short, stop = low + syminfo.mintick, alert_message = message_entershort)
|
|
|
|
if strategy.position_size > 0 and timetoclose and enableclose
|
|
strategy.close_all(alert_message = message_closelong)
|
|
if strategy.position_size < 0 and timetoclose and enableclose
|
|
strategy.close_all(alert_message = message_closeshort)
|
|
|
|
if strategy.position_size > 0 and enablesltp and time_cond
|
|
strategy.exit(id="Close Long", stop=longStop, limit=longTake, alert_message = message_takeprofit)
|
|
if strategy.position_size < 0 and enablesltp and time_cond
|
|
strategy.exit(id="Close Short", stop=shortStop, limit=shortTake, alert_message = message_stoploss)
|
|
|
|
|
|
|
|
|
|
|
|
```
|
|
|
|
> Detail
|
|
|
|
https://www.fmz.com/strategy/432806
|
|
|
|
> Last Modified
|
|
|
|
2023-11-21 17:03:32
|