
535 lines
25 KiB
Markdown
535 lines
25 KiB
Markdown
|
|
> Name
|
|
|
|
双重超强趋势跟踪止损策略Dual-Strong-Trend-Tracking-Stop-Loss-Strategy
|
|
|
|
> Author
|
|
|
|
ChaoZhang
|
|
|
|
> Strategy Description
|
|
|
|
|
|
[trans]
|
|
|
|
## 概述
|
|
|
|
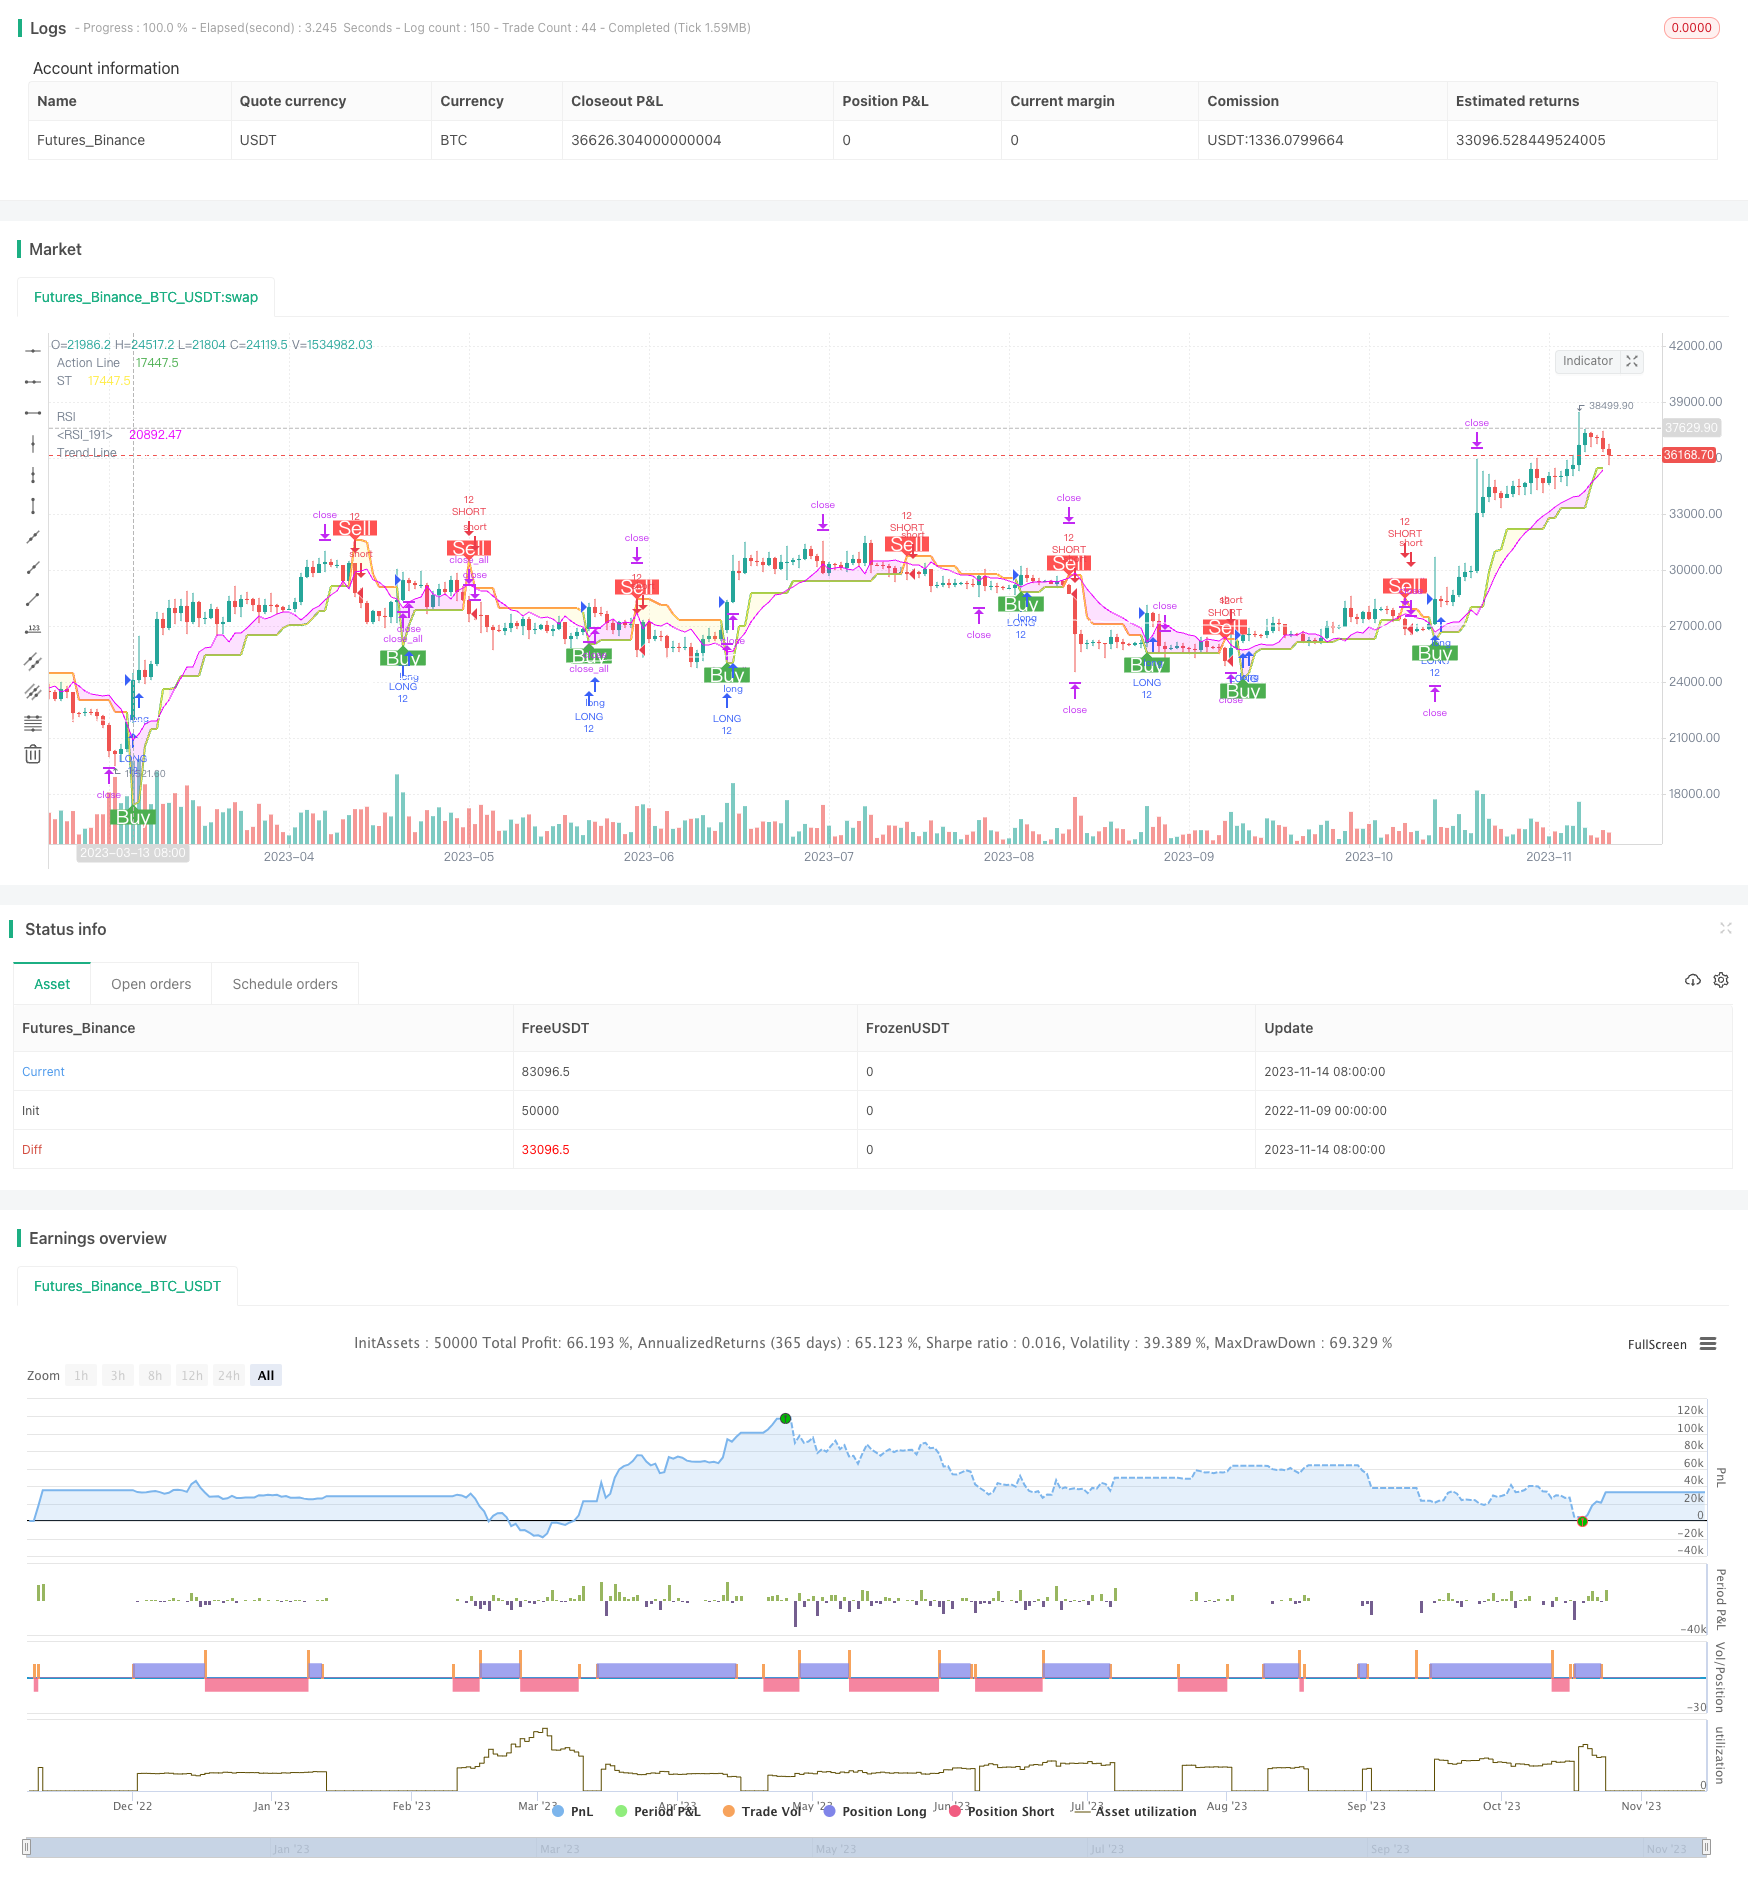
本策略基于超强指数平滑移动平均线和相对强弱指数,设计了双重趋势跟踪机制,可以准确判断行情趋势,并设定合理的止损止盈点。策略具有止损点随行情跟踪、止盈点根据趋势设定、双重趋势判断等特点,可以有效控制 einzelnen交易的风险,在趋势行情中获得超强收益。
|
|
|
|
## 策略原理
|
|
|
|
1. 计算超强指数平滑移动平均线(Super Trend),判断主要趋势方向。超强指数平滑移动平均线能够准确判断趋势方向,并给出理想的入场点。
|
|
|
|
2. 计算相对强弱指数(RSI),作为辅助判断趋势指标。RSI高位时为超买区,表示牛市趋势;RSI低位时为超卖区,表示熊市趋势。
|
|
|
|
3. 当关闭价跨过超强指数平滑移动平均线时,做多;当关闭价跌破超强指数平滑移动平均线时,做空。
|
|
|
|
4. 合理设定止损止盈点。做多时,以超强指数平滑移动平均线作为止损线,以超强指数平滑移动平均线加合理盈利为止盈点;做空时,以超强指数平滑移动平均线作为止损线,以超强指数平滑移动平均线减合理盈利为止盈点。
|
|
|
|
5. 止损点会随着行情波动进行浮动。如行情向有利方向发展,止损线会向有利方向移动,确保利润。
|
|
|
|
6. 当RSI与超强指数平滑移动平均线方向一致时,表示目前趋势较强,此时策略才会入场。当RSI与超强指数平滑移动平均线方向不一致时,表示趋势转折的可能,此时策略会暂时离场。
|
|
|
|
## 优势分析
|
|
|
|
- 双重趋势判断机制,可以减少错误信号,增强策略稳定性。
|
|
|
|
- 停损点随趋势移动,可以最大程度锁定利润,避免止损过早。
|
|
|
|
- RSI指标的运用,可以过滤掉部分弱势的交易信号。
|
|
|
|
- 合理设定止盈位置,让利润最大化。
|
|
|
|
- 策略参数可调节,可以根据不同品种和行情特点进行优化。
|
|
|
|
- 策略回撤可控,具有较强的风险管理能力。
|
|
|
|
## 风险分析
|
|
|
|
- 若遇到突发事件,如重大政策消息,行情可能出现剧烈波动,导致止损点被突破,造成较大亏损。可以适当放宽止损点,或在重大风险事件来临前及时离场。
|
|
|
|
- 参数设置不当,可能导致止损止盈点设定不合理,扩大亏损或缩小盈利。可以通过反复回测寻找最佳参数组合。
|
|
|
|
- 多空混战阶段,RSI和超强指数平滑移动平均线可能出现一定背离,导致策略产生错误交易信号。这时可以暂时不交易,等待明确趋势再入场。
|
|
|
|
## 优化方向
|
|
|
|
- 优化ATR周期参数,使之更符合不同品种的特点。
|
|
|
|
- 优化RSI参数设置,找到更稳定可靠的辅助趋势判断条件。
|
|
|
|
- 结合其他指标判断,如布林带、KDJ等,设定更精准的入场出场依据。
|
|
|
|
- 测试不同的止盈策略,如跟踪止盈、阶梯止盈、影线止盈等,优化盈利水平。
|
|
|
|
- 根据回测结果调整仓位管理策略,降低单笔交易风险。
|
|
|
|
## 总结
|
|
|
|
本策略整体具有较强的稳定性和持续盈利能力。双重趋势判断机制可以有效过滤噪音,止损止盈策略可以锁定盈利并控制风险。通过不断优化参数设置和入场出场条件,可以使策略在不同市场环境中获得良好表现。总体来说,本策略可作为量化交易的优秀策略模板,值得重点研究和应用。
|
|
|
|
||
|
|
|
|
## Overview
|
|
|
|
This strategy is designed with dual trend tracking mechanisms based on Supertrend and Relative Strength Index to accurately determine the trend of the market and set reasonable stop loss and take profit points. The strategy features stop loss points that track the market movement, take profit points based on the trend, and dual trend judgment, which can effectively control the risk of individual trades and achieve super strong returns in trending markets.
|
|
|
|
## Strategy Logic
|
|
|
|
1. Calculate the Supertrend to determine the main trend direction. Supertrend can accurately judge the trend direction and give ideal entry points.
|
|
|
|
2. Calculate the Relative Strength Index (RSI) as an auxiliary indicator for trend judgment. High RSI indicates a bullish trend in a bull market. Low RSI indicates a bearish trend in a bear market.
|
|
|
|
3. Go long when the close price crosses above the Supertrend line, and go short when the close price breaks below the Supertrend line.
|
|
|
|
4. Reasonably set stop loss and take profit points. When going long, set the Supertrend line as the stop loss, and the Supertrend line plus reasonable profit as the take profit. When going short, set the Supertrend line as the stop loss, and the Supertrend line minus reasonable profit as the take profit.
|
|
|
|
5. The stop loss points will float according to the market fluctuation. As the market moves in a favorable direction, the stop loss line will move towards the favorable direction to secure profits.
|
|
|
|
6. Only enter trades when RSI aligns with Supertrend, indicating a stronger current trend. Avoid entering when RSI diverges from Supertrend, indicating a potential trend reversal.
|
|
|
|
## Advantage Analysis
|
|
|
|
- The dual trend judgment mechanism can reduce false signals and enhance the stability of the strategy.
|
|
|
|
- The stop loss points move with the trend to maximize profit locking and avoid premature stop loss.
|
|
|
|
- The application of RSI filters out some weak trading signals.
|
|
|
|
- Reasonable take profit positioning maximizes profits.
|
|
|
|
- Adjustable strategy parameters can be optimized for different products and market conditions.
|
|
|
|
- Controllable drawdowns give the strategy strong risk management capabilities.
|
|
|
|
## Risk Analysis
|
|
|
|
- In case of black swan events like significant policy news, huge market swings may stop out positions and cause major losses. Wider stop loss points or timely position exiting prior to events can help manage such risks.
|
|
|
|
- Improper parameter settings may lead to unreasonable stop loss and take profit points, enlarging losses or shrinking profits. Repeated backtests can help find the optimal parameter combination.
|
|
|
|
- Divergence between RSI and Supertrend may generate false signals during range-bound markets. Avoid trading and wait for a clear trend in such cases.
|
|
|
|
## Optimization Directions
|
|
|
|
- Optimize the ATR period parameter for different products.
|
|
|
|
- Optimize RSI settings to find more stable auxiliary trend conditions.
|
|
|
|
- Incorporate other indicators like Bollinger Bands and KDJ to set more precise entry and exit rules.
|
|
|
|
- Test different take profit strategies like trailing stop, staggered profit taking, wick stop etc. to improve profitability.
|
|
|
|
- Adjust position sizing based on backtest results to lower single trade risks.
|
|
|
|
## Conclusion
|
|
|
|
The strategy demonstrates overall strong stability and profitability. The dual trend judgment filters out noise effectively and the stop loss/profit taking strategy locks in profits and controls risks. Continuous optimization of parameters and entry/exit conditions will enable great performance across different market environments. It can serve as an excellent template strategy for quantitative trading and is worth in-depth research and application.
|
|
|
|
[/trans]
|
|
|
|
> Strategy Arguments
|
|
|
|
|
|
|
|
|Argument|Default|Description|
|
|
|----|----|----|
|
|
|v_input_1|true|════════════ FROM ════════════|
|
|
|v_input_4|true|══════════ STRATEGY ══════════|
|
|
|v_input_string_1|0|Position Type: LONG|SHORT|
|
|
|v_input_float_1|3|Initial Stop Loss|
|
|
|v_input_5|true|ATR Period|
|
|
|v_input_float_2|3|ATR multplierFactoriplier|
|
|
|v_input_int_1|7|RSI|
|
|
|v_input_6|true|══════════ LOT CALC ══════════|
|
|
|v_input_7|true|══════════ TREND LINE ══════════|
|
|
|v_input_int_2|200|Trend Line|
|
|
|v_input_8_close|0|Source: close|high|low|open|hl2|hlc3|hlcc4|ohlc4|
|
|
|v_input_9|true|══════════ MT LOGIN ══════════|
|
|
|v_input_string_2|0|EXCHANGE: MT5|MT4|
|
|
|v_input_string_6|0|STRATEGY ON: ON|OFF|
|
|
|v_input_string_7|0|ENTRY MODE: CLOSE OPEN|OPEN|
|
|
|v_input_10|true|══════════ DISPLAY LOGIN ══════════|
|
|
|v_input_2|timestamp(02 Jan 2023 00:00 +0000)|(?RISK MANAGEMENT)START FILTER|
|
|
|v_input_3|timestamp(12 Dec 2100 00:00 +0000)|END FILTER|
|
|
|v_input_float_3|250000|(?INPUTS)ACCOUNT BALANCE|
|
|
|v_input_float_4|100|ENTRY PRICE|
|
|
|v_input_float_5|100|STOP LOSS PRICE|
|
|
|v_input_float_6|true|RISK USD|
|
|
|v_input_float_7|10|LOT SIZE|
|
|
|v_input_string_3||(?mt)MT LOGIN|
|
|
|v_input_string_4||MT PASSWORD|
|
|
|v_input_string_5||MT SERVER|
|
|
|v_input_11|false|(?PRODUCTION)DISPLAY TABLE|
|
|
|
|
|
|
> Source (PineScript)
|
|
|
|
``` pinescript
|
|
/*backtest
|
|
start: 2022-11-09 00:00:00
|
|
end: 2023-11-15 00:00:00
|
|
period: 1d
|
|
basePeriod: 1h
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
|
*/
|
|
|
|
//@version=5
|
|
//
|
|
// ▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒
|
|
// -----------------------------------------------------------------------------
|
|
// Copyright 2019 Mauricio Pimenta | exit490
|
|
// SuperTrend with Trailing Stop Loss script may be freely distributed under the MIT license.
|
|
//
|
|
// Permission is hereby granted, free of charge,
|
|
// to any person obtaining a copy of this software and associated documentation files (the "Software"),
|
|
// to deal in the Software without restriction, including without limitation the rights to use, copy, modify, merge,
|
|
// publish, distribute, sublicense, and/or sell copies of the Software, and to permit persons to whom the Software is furnished to do so,
|
|
// subject to the following conditions:
|
|
//
|
|
// The above copyright notice and this permission notice shall be included in all copies or substantial portions of the Software.
|
|
//
|
|
// THE SOFTWARE IS PROVIDED "AS IS", WITHOUT WARRANTY OF ANY KIND,
|
|
// EXPRESS OR IMPLIED, INCLUDING BUT NOT LIMITED TO THE WARRANTIES OF MERCHANTABILITY,
|
|
// FITNESS FOR A PARTICULAR PURPOSE AND NONINFRINGEMENT. IN NO EVENT SHALL THE AUTHORS OR COPYRIGHT HOLDERS BE LIABLE FOR ANY CLAIM,
|
|
// DAMAGES OR OTHER LIABILITY, WHETHER IN AN ACTION OF CONTRACT, TORT OR OTHERWISE, ARISING FROM,
|
|
// OUT OF OR IN CONNECTION WITH THE SOFTWARE OR THE USE OR OTHER DEALINGS IN THE SOFTWARE.
|
|
//
|
|
// -----------------------------------------------------------------------------
|
|
//
|
|
// Authors: @exit490
|
|
// Revision: v1.0.0
|
|
// Date: 5-Aug-2019
|
|
//
|
|
// Description
|
|
// ===========
|
|
// SuperTrend is a moving stop and reversal line based on the volatility (ATR).
|
|
// The strategy will ride up your stop loss when price moviment 1%.
|
|
// The strategy will close your operation when the market price crossed the stop loss.
|
|
// The strategy will close operation when the line based on the volatility will crossed
|
|
//
|
|
// The strategy has the following parameters:
|
|
//
|
|
// INITIAL STOP LOSS - Where can isert the value to first stop.
|
|
// POSITION TYPE - Where can to select trade position.
|
|
// ATR PERIOD - To select number of bars back to execute calculation
|
|
// ATR MULTPLIER - To add a multplier factor on volatility
|
|
// BACKTEST PERIOD - To select range.
|
|
//
|
|
// -----------------------------------------------------------------------------
|
|
// Disclaimer:
|
|
// 1. I am not licensed financial advisors or broker dealers. I do not tell you
|
|
// when or what to buy or sell. I developed this software which enables you
|
|
// execute manual or automated trades multplierFactoriplierFactoriple trades using TradingView. The
|
|
// software allows you to set the criteria you want for entering and exiting
|
|
// trades.
|
|
// 2. Do not trade with money you cannot afford to lose.
|
|
// 3. I do not guarantee consistent profits or that anyone can make money with no
|
|
// effort. And I am not selling the holy grail.
|
|
// 4. Every system can have winning and losing streaks.
|
|
// 5. Money management plays a large role in the results of your trading. For
|
|
// example: lot size, account size, broker leverage, and broker margin call
|
|
// rules all have an effect on results. Also, your Take Profit and Stop Loss
|
|
// settings for individual pair trades and for overall account equity have a
|
|
// major impact on results. If you are new to trading and do not understand
|
|
// these items, then I recommend you seek education materials to further your
|
|
// knowledge.
|
|
//
|
|
// YOU NEED TO FIND AND USE THE TRADING SYSTEM THAT WORKS BEST FOR YOU AND YOUR
|
|
// TRADING TOLERANCE.
|
|
//
|
|
// I HAVE PROVIDED NOTHING MORE THAN A TOOL WITH OPTIONS FOR YOU TO TRADE WITH THIS PROGRAM ON TRADINGVIEW.
|
|
//
|
|
// I accept suggestions to improve the script.
|
|
// If you encounter any problems I will be happy to share with me.
|
|
// -----------------------------------------------------------------------------
|
|
//
|
|
// ▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒ //
|
|
|
|
strategy(title='DEO SESSSION', shorttitle='DEO S', overlay=true, precision=8, calc_on_order_fills=true, calc_on_every_tick=true, backtest_fill_limits_assumption=0, default_qty_type=strategy.percent_of_equity, default_qty_value=100, initial_capital=1000, currency=currency.USD, linktoseries=true)
|
|
|
|
//
|
|
// ▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒ //
|
|
|
|
// === BACKTEST RANGE ===
|
|
backTestSectionFrom = input(title='════════════ FROM ════════════', defval=true)
|
|
|
|
|
|
// selected dates
|
|
i_startTime = input(title="START FILTER", defval=timestamp("02 Jan 2023 00:00 +0000"), group="RISK MANAGEMENT", tooltip="Start date & time to begin searching for setups")
|
|
i_endTime = input(title="END FILTER", defval=timestamp("12 Dec 2100 00:00 +0000"), group="RISK MANAGEMENT", tooltip="End date & time to stop searching for setups")
|
|
afterStartDate = true
|
|
|
|
//
|
|
// ▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒ //
|
|
|
|
parameterSection = input(title='══════════ STRATEGY ══════════', defval=true)
|
|
// === INPUT TO SELECT POSITION ===
|
|
positionType = input.string(defval='LONG', title='Position Type', options=['LONG', 'SHORT'])
|
|
|
|
// === INPUT TO SELECT INITIAL STOP LOSS
|
|
initialStopLossPercent = input.float(defval=3.0, minval=0.0, title='Initial Stop Loss')
|
|
|
|
// === INPUT TO SELECT BARS BACK
|
|
barsBack = input(title='ATR Period', defval=1)
|
|
|
|
// === INPUT TO SELECT MULTPLIER FACTOR
|
|
multplierFactor = input.float(title='ATR multplierFactoriplier', step=0.1, defval=3.0)
|
|
|
|
|
|
RSI = input.int(title='RSI', defval=7, minval=1, maxval=100)
|
|
|
|
calcSection = input(title='══════════ LOT CALC ══════════', defval=true)
|
|
accountBalance = input.float(title="ACCOUNT BALANCE", defval=250000, minval=1, group="INPUTS")
|
|
entryPrice = input.float(title="ENTRY PRICE", defval=100, minval=1, group="INPUTS")
|
|
slPrice = input.float(title="STOP LOSS PRICE", defval=100, minval=1, group="INPUTS")
|
|
riskPer = input.float(title="RISK USD", defval=1, minval=0.1, group="INPUTS")
|
|
lotSize = input.float(title="LOT SIZE", defval=10, minval=0.1, group="INPUTS")
|
|
|
|
RiskSize = riskPer
|
|
qtyLongTargetPrice = math.abs((RiskSize / ((entryPrice - slPrice) * syminfo.pointvalue)) / lotSize)
|
|
|
|
trendcSection = input(title='══════════ TREND LINE ══════════', defval=true)
|
|
// ema trend
|
|
tLen = input.int(200, minval=1, title="Trend Line")
|
|
tSrc = input(close, title="Source")
|
|
thisEma = ta.ema(tSrc, tLen)
|
|
plot(thisEma, title = "Trend Line",color=#ffffff)
|
|
|
|
MTSection = input(title='══════════ MT LOGIN ══════════', defval=true)
|
|
exchange = input.string(defval='MT5', title='EXCHANGE', options=['MT4', 'MT5'])
|
|
mtLogin= input.string(defval="", title='MT LOGIN', group = "mt")
|
|
mtPassword =input.string(defval='', title='MT PASSWORD', group = "mt")
|
|
mtServer =input.string(defval='', title='MT SERVER', group = "mt")
|
|
mtIsOn = input.string(defval='ON', title='STRATEGY ON', options=['ON', 'OFF'])
|
|
mtEntryMode = input.string(defval='CLOSE OPEN', title='ENTRY MODE', options=['CLOSE OPEN', 'OPEN'])
|
|
|
|
displaySection = input(title='══════════ DISPLAY LOGIN ══════════', defval=true)
|
|
displayTable = input(title="DISPLAY TABLE", defval=false, group = 'PRODUCTION', tooltip = "MAKES YOUR STRATEGY TRIGGER SLOWER")
|
|
|
|
|
|
|
|
//
|
|
// ▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒▒ //
|
|
|
|
// LOGIC TO FIND DIRECTION WHEN THERE IS TREND CHANGE ACCORDING VOLATILITY
|
|
atr = multplierFactor * ta.atr(barsBack)
|
|
|
|
longStop = hl2 - atr
|
|
longStopPrev = nz(longStop[1], longStop)
|
|
longStop := close[1] > longStopPrev ? math.max(longStop, longStopPrev) : longStop
|
|
|
|
shortStop = hl2 + atr
|
|
shortStopPrev = nz(shortStop[1], shortStop)
|
|
shortStop := close[1] < shortStopPrev ? math.min(shortStop, shortStopPrev) : shortStop
|
|
|
|
direction = 1
|
|
direction := nz(direction[1], direction)
|
|
direction := direction == -1 and close > shortStopPrev ? 1 : direction == 1 and close < longStopPrev ? -1 : direction
|
|
|
|
|
|
longColor = color.blue
|
|
shortColor = color.blue
|
|
|
|
var valueToPlot = 0.0
|
|
var colorToPlot = color.white
|
|
|
|
if direction == 1
|
|
valueToPlot := longStop
|
|
colorToPlot := color.green
|
|
colorToPlot
|
|
else
|
|
valueToPlot := shortStop
|
|
colorToPlot := color.red
|
|
colorToPlot
|
|
|
|
//RSI
|
|
|
|
src = close
|
|
|
|
ep = 2 * RSI - 1
|
|
auc = ta.ema(math.max(src - src[1], 0), ep)
|
|
adc = ta.ema(math.max(src[1] - src, 0), ep)
|
|
x1 = (RSI - 1) * (adc * 70 / (100 - 70) - auc)
|
|
ub = x1 >= 0 ? src + x1 : src + x1 * (100 - 70) / 70
|
|
x2 = (RSI - 1) * (adc * 30 / (100 - 30) - auc)
|
|
lb = x2 >= 0 ? src + x2 : src + x2 * (100 - 30) / 30
|
|
|
|
//Affichage
|
|
plot(math.avg(ub, lb), color=color.white ,linewidth=1, title='RSI')
|
|
plot(valueToPlot == 0.0 ? na : valueToPlot, title='Action Line', linewidth=2, color=color.new(colorToPlot, 0))
|
|
plotshape(direction == 1 and direction[1] == -1 ? longStop : na, title='Buy', style=shape.labelup, location=location.absolute, size=size.normal, text='Buy', textcolor=color.new(color.white, 0), color=color.new(color.green, 0))
|
|
plotshape(direction == -1 and direction[1] == 1 ? shortStop : na, title='Sell', style=shape.labeldown, location=location.absolute, size=size.normal, text='Sell', textcolor=color.new(color.white, 0), color=color.new(color.red, 0))
|
|
|
|
|
|
|
|
p_ma1 = plot(valueToPlot, title = "ST", color = color.rgb(255, 236, 66))
|
|
p_ma2 = plot(math.avg(ub, lb), title = "RSI", color = color.rgb(234, 0, 255))
|
|
// Definitions: Trends
|
|
TrendUp1() =>
|
|
valueToPlot > math.avg(ub, lb)
|
|
TrendDown1() =>
|
|
valueToPlot < math.avg(ub, lb)
|
|
|
|
trendColor1 = TrendUp1() ? color.rgb(255, 236, 66, 85): TrendDown1() ? color.rgb(234, 0, 255, 85) : color.rgb(255, 255, 255, 85)
|
|
fill(p_ma1, p_ma2, color=trendColor1)
|
|
|
|
|
|
longCondition () =>
|
|
ta.crossover(close, valueToPlot)
|
|
|
|
shortCondition () =>
|
|
ta.crossunder(close, valueToPlot)
|
|
|
|
IsLongShort() =>
|
|
strategy.position_size != 0
|
|
|
|
getNewLotSize() =>
|
|
math.abs(riskPer / (close - valueToPlot))
|
|
|
|
// plot(getNewLotSize(), "new lot size")
|
|
newLotS = getNewLotSize()
|
|
|
|
|
|
alertManagement = str.tostring(exchange) + "," + str.tostring(mtLogin) + "," +str.tostring(mtPassword) + ","
|
|
alertManagement += str.tostring(mtServer) + "," + str.tostring(newLotS)
|
|
// alertManagement += str.tostring(stopLoss) + "," + str.tostring(applyingSL) + "," + str.tostring(applyTrailingStop) + ","
|
|
// alertManagement += str.tostring(exchange) + "," + str.tostring(exchangeAccount) + "," + str.tostring(slAmount) + "," + str.tostring(closeTpAmount) + ","
|
|
// alertManagement += str.tostring(exchangeLeverage) + "," + str.tostring(exchangeLeverageType) + ","
|
|
// alertManagement += str.tostring(mtLogin) + "," + str.tostring(mtPassword) + "," + str.tostring(mtServer) + "," + str.tostring(mtLot) + ","
|
|
// alertManagement += str.tostring(mtTp) + "," + str.tostring(mtTs) + "," + str.tostring(orderStrategy)
|
|
|
|
|
|
// alertManagement = "alertManagement"
|
|
myStop = 0.0
|
|
myTarget = 0.0
|
|
|
|
if (longCondition())
|
|
qtyLongTargetPrice := math.abs((RiskSize / ((close - valueToPlot) * syminfo.pointvalue)) / lotSize)
|
|
if IsLongShort()
|
|
strategy.close_all(comment = "close all entries")
|
|
strategy.entry("LONG", strategy.long, qty=12, comment="LONG", alert_message=alertManagement)
|
|
strategy.exit("TPL", "LONG", stop=valueToPlot, limit= close + (close - valueToPlot), comment="Target", alert_message=alertManagement)
|
|
|
|
if (shortCondition())
|
|
qtyLongTargetPrice := math.abs((RiskSize / ((close - valueToPlot) * syminfo.pointvalue)) / lotSize)
|
|
if IsLongShort()
|
|
strategy.close_all(comment = "close all entries")
|
|
strategy.entry("SHORT", strategy.short, qty=12, comment="SHORT", alert_message=alertManagement)
|
|
strategy.exit("TPS", "SHORT", stop=valueToPlot, limit= close + (close - valueToPlot), comment="Target", alert_message=alertManagement)
|
|
|
|
|
|
// Calculate the average profit per open trade
|
|
// avgProfit = profitSum / strategy.opentrades
|
|
|
|
getTotalProfit()=>
|
|
// Sum the profit of all open trades
|
|
profitSum = 0.0
|
|
for tradeNumber = 0 to strategy.closedtrades - 1
|
|
if strategy.closedtrades.profit(tradeNumber) > 0
|
|
profitSum += strategy.closedtrades.profit(tradeNumber)
|
|
result = profitSum
|
|
|
|
getTotalLoss()=>
|
|
// Sum the profit of all open trades
|
|
lossSum = 0.0
|
|
for tradeNumber = 0 to strategy.closedtrades - 1
|
|
if strategy.closedtrades.profit(tradeNumber) < 0
|
|
lossSum += strategy.closedtrades.profit(tradeNumber)
|
|
result = lossSum
|
|
|
|
|
|
maxLossRun()=>
|
|
lossRun = 0.0
|
|
currentMaxLoss = 0.0
|
|
for tradeNo = 0 to strategy.closedtrades - 1
|
|
if strategy.closedtrades.profit(tradeNo) < 0.0
|
|
lossRun += strategy.closedtrades.profit(tradeNo)
|
|
else
|
|
currentMaxLoss := math.min(currentMaxLoss, lossRun)
|
|
lossRun := 0.0
|
|
result = currentMaxLoss
|
|
|
|
|
|
|
|
TotalTrades() =>
|
|
strategy.closedtrades + strategy.opentrades
|
|
|
|
maxDrawDown() =>
|
|
maxDrawdown = 0.0
|
|
for tradeNo = 0 to strategy.closedtrades - 1
|
|
maxDrawdown := math.max(maxDrawdown, strategy.closedtrades.max_drawdown(tradeNo))
|
|
result = maxDrawdown
|
|
|
|
maxRunUp() =>
|
|
maxRunup = 0.0
|
|
for tradeNo = 0 to strategy.closedtrades - 1
|
|
maxRunup := math.max(maxRunup, strategy.closedtrades.max_runup(tradeNo))
|
|
result = maxRunup
|
|
|
|
tradeMaxLossReached() =>
|
|
maxLoss = 0.0
|
|
for tradeNo = 0 to strategy.closedtrades - 1
|
|
maxLoss := math.min(maxLoss, strategy.closedtrades.profit(tradeNo))
|
|
result = maxLoss
|
|
|
|
|
|
tradingStartTime() =>
|
|
strategy.closedtrades.entry_time(0)
|
|
|
|
|
|
|
|
|
|
|
|
daysBetween(t1, t2) => (t1 - t2) / 86400000
|
|
|
|
// Table
|
|
var InfoPanel = table.new(position = position.bottom_right, columns = 2, rows = 40, border_width = 1)
|
|
ftable(_table_id, _column, _row, _text, _bgcolor) =>
|
|
table.cell(_table_id, _column, _row, _text, 0, 0, color.black, text.align_right, text.align_center, size.small, _bgcolor)
|
|
|
|
tfString(int timeInMs) =>
|
|
// @function Produces a string corresponding to the input time in days, hours, and minutes.
|
|
// @param (series int) A time value in milliseconds to be converted to a string variable.
|
|
// @returns (string) A string variable reflecting the amount of time from the input time.
|
|
float s = timeInMs / 100000
|
|
float m = s / 60
|
|
float h = m / 60
|
|
float d = h / 24
|
|
float mo = d / 30.416
|
|
int tm = math.floor(m % 60)
|
|
int tr = math.floor(h % 24)
|
|
int td = math.floor(d % 30.416)
|
|
int tmo = math.floor(mo % 12)
|
|
int ys = math.floor(d / 365)
|
|
|
|
string result =
|
|
switch
|
|
d == 30 and tr == 10 and tm == 30 => "1M"
|
|
d == 7 and tr == 0 and tm == 0 => "1W"
|
|
=>
|
|
string yStr = ys ? str.tostring(ys) + "Y " : ""
|
|
string moStr = tmo ? str.tostring(tmo) + "M " : ""
|
|
string dStr = td ? str.tostring(td) + "D " : ""
|
|
string hStr = tr ? str.tostring(tr) + "H " : ""
|
|
string mStr = tm ? str.tostring(tm) + "min" : ""
|
|
yStr + moStr + dStr + hStr + mStr
|
|
|
|
|
|
|
|
if displayTable
|
|
maxLossRunInMarket= maxLossRun()
|
|
maxLossReached = tradeMaxLossReached()
|
|
tradeMaxLossReached = tradeMaxLossReached()
|
|
tradingInDays=daysBetween(time, tradingStartTime())
|
|
totalTrades=TotalTrades()
|
|
```
|
|
|
|
> Detail
|
|
|
|
https://www.fmz.com/strategy/432335
|
|
|
|
> Last Modified
|
|
|
|
2023-11-16 15:50:54
|