
263 lines
9.9 KiB
Markdown
263 lines
9.9 KiB
Markdown
|
|
> Name
|
|
|
|
Ichimoku-Kinko-Hyo趋势跟踪策略Ichimoku-Kinko-Hyo-indicator-Balancing-Trend-Strategy
|
|
|
|
> Author
|
|
|
|
ChaoZhang
|
|
|
|
> Strategy Description
|
|
|
|
|
|
[trans]
|
|
|
|
## 概述
|
|
|
|
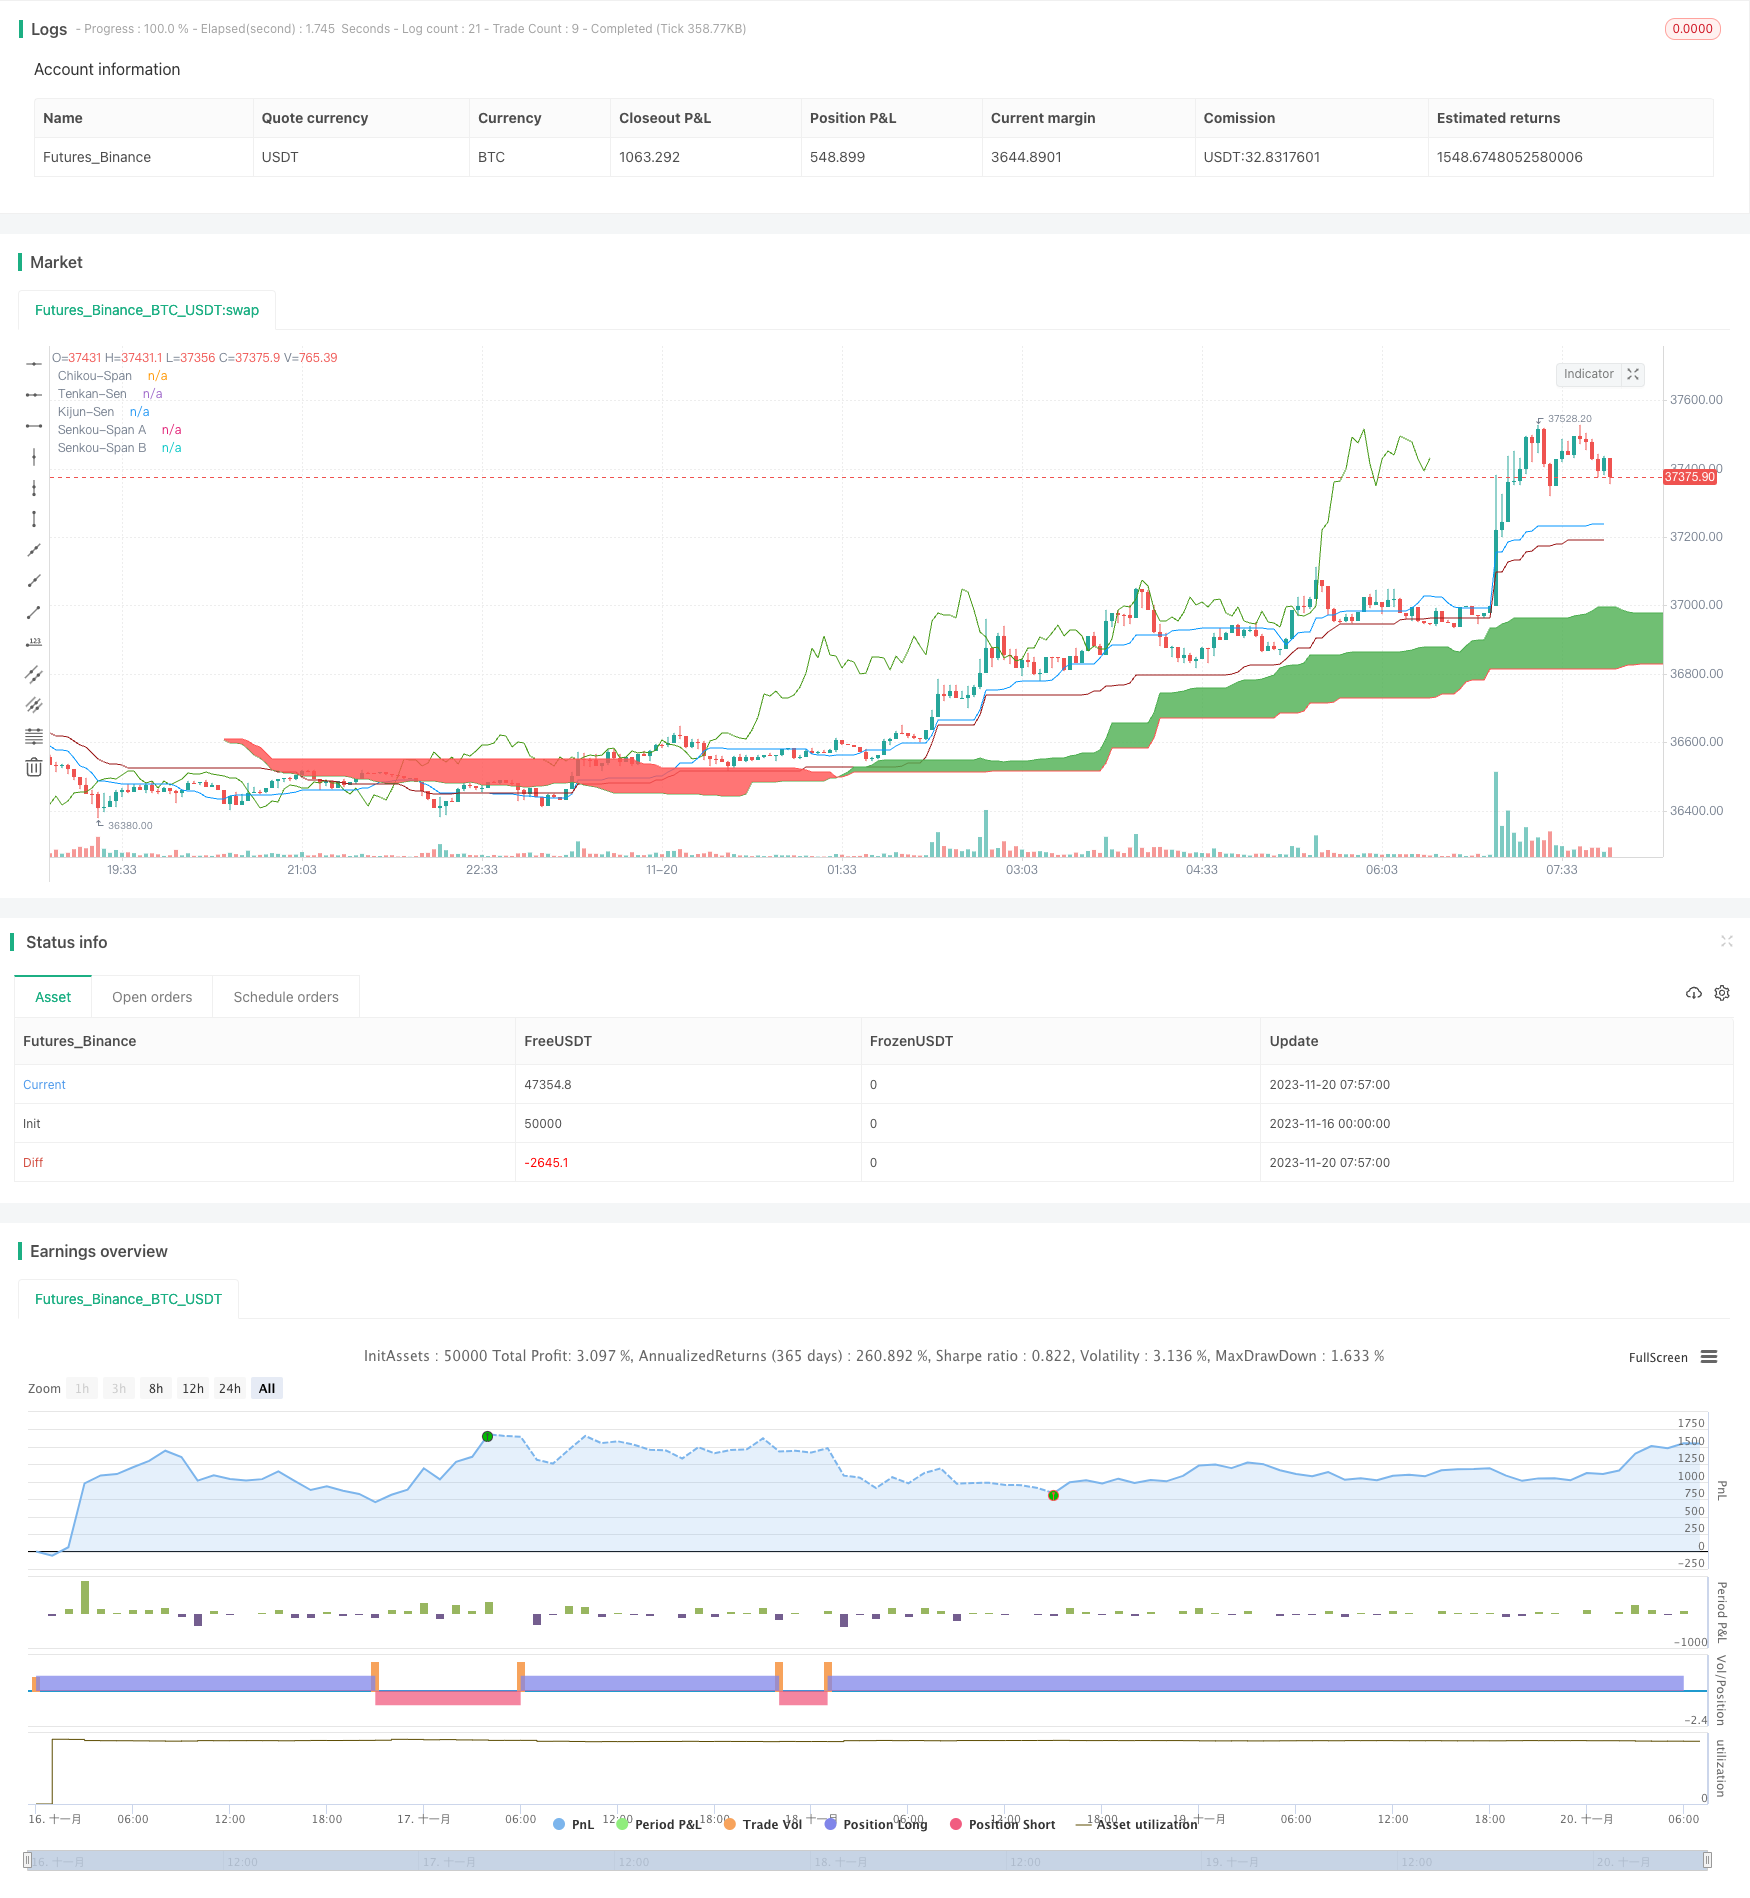
一目均衡策略是一个利用Ichimoku Kinko Hyo指标实现的趋势跟踪策略。该策略结合多种指标识别趋势方向,在牛市中做多,在熊市中做空,实现资金的长期增值。
|
|
|
|
## 策略原理
|
|
|
|
该策略主要基于Ichimoku Kinko Hyo指标。该指标由转向线(Tenkan-Sen)、基准线(Kijun-Sen)、前沿线(Senkou-Span A)、先行线(Senkou-Span B)和延迟线(Chikou-Span)组成。当价格在云图之上时为多头趋势,当价格在云图之下时为空头趋势。
|
|
|
|
该策略的交易信号来自以下条件的组合:
|
|
|
|
1. 转向线上穿基准线为多头信号
|
|
2. 转向线下穿基准线为空头信号
|
|
3. 延迟线向上穿越为多头确认
|
|
4. 延迟线向下穿越为空头确认
|
|
5. RSI指标高于50为多头指标
|
|
6. RSI指标低于50为空头指标
|
|
7. 价格在云图之上为多头趋势
|
|
8. 价格在云图之下为空头趋势
|
|
|
|
当上述多头条件同时满足时,做多入场;当上述空头条件同时满足时,做空入场。
|
|
|
|
## 优势分析
|
|
|
|
该策略结合趋势跟踪和超买超卖指标,能够有效识别趋势的方向。主要优势如下:
|
|
|
|
1. Ichimoku Kinko Hyo指标能够识别中长期趋势,避免被短期市场噪音误导。
|
|
2. 结合RSI指标可以有效判断超买超卖区域,防止错过反转机会。
|
|
3. 考虑了股价波动率条件,只在波动率较高时出手,避免无效交易。
|
|
4. 严格的入场和出场机制,最大程度规避风险。
|
|
|
|
## 风险分析
|
|
|
|
该策略也存在一些风险需要注意:
|
|
|
|
1. Ichimoku Kinko Hyo指标存在滞后,可能导致入场时机偏晚。
|
|
2. 多条件组合交易信号出现的频率较低,容易导致交易次数不足。
|
|
3. 未考虑资金管理和仓位管理,可能存在超量交易的风险。
|
|
|
|
对应解决方法:
|
|
|
|
1. 适当缩短Ichimoku Kinko Hyo参数,提高指标的灵敏度。
|
|
2. 降低入场条件严格度,增加交易频率。
|
|
3. 加入资金管理和仓位管理模块,控制单笔交易资金占比和仓位。
|
|
|
|
## 优化方向
|
|
|
|
该策略可以从以下几个方向进行优化:
|
|
|
|
1. 更换或组合其他指标,如KDJ、MACD等,丰富信号来源。
|
|
2. 优化Ichimoku Kinko Hyo 参数,提高指标灵敏度。
|
|
3. 加入止损策略,以锁定利润和控制风险。
|
|
4. 增加仓位管理模块,根据资金规模动态调整仓位。
|
|
5. 增加期货套期保值模块,管理多头套期保值风险。
|
|
|
|
## 总结
|
|
|
|
一目均衡策略整体是一个可靠、稳健的趋势跟踪策略。它解决了趋势交易中的重要问题——识别趋势准确度和 trades 生成频率之间的平衡。通过参数调整和模块扩展仍有优化空间,是可以长期运用的策略之一。
|
|
|
|
||
|
|
|
|
## Overview
|
|
|
|
The Balancing Trend strategy is a trend following strategy that utilizes the Ichimoku Kinko Hyo indicator. It identifies trend directions by combining multiple indicators, goes long in a bull market and goes short in a bear market, to achieve long-term capital appreciation.
|
|
|
|
## Strategy Principle
|
|
|
|
The core of this strategy is based on the Ichimoku Kinko Hyo indicator, which consists of the Tenkan-Sen (Conversion Line), Kijun-Sen (Base Line), Senkou Span A (Leading Span A), Senkou Span B (Leading Span B) and Chikou Span (Lagging Span). When price is above the cloud, it signals an upward trend. When price is below the cloud, it signals a downward trend.
|
|
|
|
The trading signals are generated based on the combination of the following conditions:
|
|
|
|
1. Tenkan-Sen crosses above Kijun-Sen as bullish signal
|
|
2. Tenkan-Sen crosses below Kijun-Sen as bearish signal
|
|
3. Chikou Span crossover upward as bullish confirmation
|
|
4. Chikou Span crossover downward as bearish confirmation
|
|
5. RSI above 50 as bullish indicator
|
|
6. RSI below 50 as bearish indicator
|
|
7. Price above the cloud indicates upward trend
|
|
8. Price below the cloud indicates downward trend
|
|
|
|
It goes long when all bullish conditions are met and goes short when all bearish conditions are met.
|
|
|
|
## Advantage Analysis
|
|
|
|
This strategy combines trend following and overbought-oversold indicators to effectively identify trend directions. The main advantages are:
|
|
|
|
1. Ichimoku Kinko Hyo can identify medium- to long-term trends, avoiding being misled by short-term market noises.
|
|
2. Incorporating RSI helps determine overbought and oversold zones, preventing missing reversal opportunities.
|
|
3. Only acts when volatility is high enough, avoiding ineffective trades.
|
|
4. Strict entry and exit rules maximally mitigate risks.
|
|
|
|
## Risk Analysis
|
|
|
|
Some risks to note for this strategy:
|
|
|
|
1. Ichimoku Kinko Hyo has lagging effect, possibly delaying entry timing.
|
|
2. Low frequency of trade signal occurrence with multiple condition combination, leading to insufficient number of trades.
|
|
3. No consideration around position sizing and risk management, risks around over-trading.
|
|
|
|
Corresponding solutions:
|
|
|
|
1. Shorten Ichimoku parameters to improve sensitivity.
|
|
2. Reduce strictness of entry conditions to increase trade frequency.
|
|
3. Incorporate risk management and position sizing modules to control per trade risk exposure and overall position.
|
|
|
|
## Optimization Directions
|
|
|
|
The strategy can be improved in the following aspects:
|
|
|
|
1. Add or combine additional indicators like KDJ, MACD to diversify signal sources.
|
|
2. Optimize Ichimoku parameters to improve sensitivity.
|
|
3. Add stop loss mechanisms to lock in profits and control risks.
|
|
4. Incorporate dynamic position sizing module based on account size.
|
|
5. Add hedging module to manage risks for long positions.
|
|
|
|
## Summary
|
|
|
|
Overall this Balancing Trend strategy is a reliable, robust trend following system. It addresses the key challenge in trend trading - balancing trend identification accuracy and trade generation frequency. There is still room for improvement through parameter tuning and module expansion. It is a strategy that can be applied for the long run.
|
|
|
|
[/trans]
|
|
|
|
> Strategy Arguments
|
|
|
|
|
|
|
|
|Argument|Default|Description|
|
|
|----|----|----|
|
|
|v_input_1|22|Tenkan-Sen Bars|
|
|
|v_input_2|60|Kijun-Sen Bars|
|
|
|v_input_3|120|Senkou-Span B Bars|
|
|
|v_input_4|30|Chikou-Span Offset|
|
|
|v_input_5|30|Senkou-Span Offset|
|
|
|v_input_6|true|Long Entry|
|
|
|v_input_7|true|Short Entry|
|
|
|v_input_8|2|VolLength|
|
|
|v_input_9|0.2|Volatility Target|
|
|
|v_input_10|true|From Day|
|
|
|v_input_11|true|From Month|
|
|
|v_input_12|2019|From Year|
|
|
|v_input_13|31|To Day|
|
|
|v_input_14|12|To Month|
|
|
|v_input_15|2020|To Year|
|
|
|
|
|
|
> Source (PineScript)
|
|
|
|
``` pinescript
|
|
/*backtest
|
|
start: 2023-11-16 00:00:00
|
|
end: 2023-11-20 08:00:00
|
|
period: 3m
|
|
basePeriod: 1m
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
|
*/
|
|
|
|
//@version=4
|
|
strategy("Ichimoku Kinko Hyo: ETH 3h Strategy by tobuno", overlay=true)
|
|
|
|
//Inputs
|
|
ts_bars = input(22, minval=1, title="Tenkan-Sen Bars")
|
|
ks_bars = input(60, minval=1, title="Kijun-Sen Bars")
|
|
ssb_bars = input(120, minval=1, title="Senkou-Span B Bars")
|
|
cs_offset = input(30, minval=1, title="Chikou-Span Offset")
|
|
ss_offset = input(30, minval=1, title="Senkou-Span Offset")
|
|
long_entry = input(true, title="Long Entry")
|
|
short_entry = input(true, title="Short Entry")
|
|
|
|
//Volatility
|
|
vollength = input(defval=2, title="VolLength")
|
|
voltarget = input(defval=0.2, type=float, step=0.1, title="Volatility Target")
|
|
Difference = abs((close - open)/((close + open)/2) * 100)
|
|
MovingAverage = sma(Difference, vollength)
|
|
highvolatility = MovingAverage > voltarget
|
|
|
|
////////////////////////////////////////////////////////////////////////////////
|
|
// BACKTESTING RANGE
|
|
|
|
// From Date Inputs
|
|
fromDay = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
|
|
fromMonth = input(defval = 1, title = "From Month", minval = 1, maxval = 12)
|
|
fromYear = input(defval = 2019, title = "From Year", minval = 1970)
|
|
|
|
// To Date Inputs
|
|
toDay = input(defval = 31, title = "To Day", minval = 1, maxval = 31)
|
|
toMonth = input(defval = 12, title = "To Month", minval = 1, maxval = 12)
|
|
toYear = input(defval = 2020, title = "To Year", minval = 1970)
|
|
|
|
// Calculate start/end date and time condition
|
|
startDate = timestamp(fromYear, fromMonth, fromDay, 00, 00)
|
|
finishDate = timestamp(toYear, toMonth, toDay, 00, 00)
|
|
time_cond = true
|
|
|
|
////////////////////////////////////////////////////////////////////////////////
|
|
|
|
middle(len) => avg(lowest(len), highest(len))
|
|
|
|
// Ichimoku Components
|
|
tenkan = middle(ts_bars)
|
|
kijun = middle(ks_bars)
|
|
senkouA = avg(tenkan, kijun)
|
|
senkouB = middle(ssb_bars)
|
|
|
|
//RSI
|
|
change = change(close)
|
|
gain = change >= 0 ? change : 0.0
|
|
loss = change < 0 ? (-1) * change : 0.0
|
|
avgGain = rma(gain, 14)
|
|
avgLoss = rma(loss, 14)
|
|
rs = avgGain / avgLoss
|
|
rsi = 100 - (100 / (1 + rs))
|
|
|
|
// Plot Ichimoku Kinko Hyo
|
|
plot(tenkan, color=#0496ff, title="Tenkan-Sen")
|
|
plot(kijun, color=#991515, title="Kijun-Sen")
|
|
plot(close, offset=-cs_offset+1, color=#459915, title="Chikou-Span")
|
|
sa=plot(senkouA, offset=ss_offset-1, color=green, title="Senkou-Span A")
|
|
sb=plot(senkouB, offset=ss_offset-1, color=red, title="Senkou-Span B")
|
|
fill(sa, sb, color = senkouA > senkouB ? green : red, title="Cloud color")
|
|
|
|
ss_high = max(senkouA[ss_offset-1], senkouB[ss_offset-1])
|
|
ss_low = min(senkouA[ss_offset-1], senkouB[ss_offset-1])
|
|
|
|
// Entry/Exit Signals
|
|
tk_cross_bull = tenkan > kijun
|
|
tk_cross_bear = tenkan < kijun
|
|
cs_cross_bull = mom(close, cs_offset-1) > 0
|
|
cs_cross_bear = mom(close, cs_offset-1) < 0
|
|
price_above_kumo = close > ss_high
|
|
price_below_kumo = close < ss_low
|
|
rsi_bullish = rsi > 50
|
|
rsi_bearish = rs < 50
|
|
bullish = tk_cross_bull and cs_cross_bull and price_above_kumo and rsi_bullish and highvolatility
|
|
bearish = tk_cross_bear and cs_cross_bear and price_below_kumo and rsi_bearish and highvolatility
|
|
|
|
strategy.entry("Long", strategy.long, when=bullish and long_entry and time_cond)
|
|
strategy.entry("Short", strategy.short, when=bearish and short_entry and time_cond)
|
|
|
|
strategy.close("Long", when=bearish and not short_entry and time_cond)
|
|
strategy.close("Short", when=bullish and not long_entry and time_cond)
|
|
|
|
```
|
|
|
|
> Detail
|
|
|
|
https://www.fmz.com/strategy/433104
|
|
|
|
> Last Modified
|
|
|
|
2023-11-24 14:38:47
|