
313 lines
16 KiB
Markdown
313 lines
16 KiB
Markdown
|
|
> Name
|
|
|
|
EMAC指数移动平均线交叉优化策略EMAC-Exponential-Moving-Average-Cross-Optimized-Strategy
|
|
|
|
> Author
|
|
|
|
ChaoZhang
|
|
|
|
> Strategy Description
|
|
|
|
|
|
[trans]
|
|
|
|
## 概述
|
|
|
|
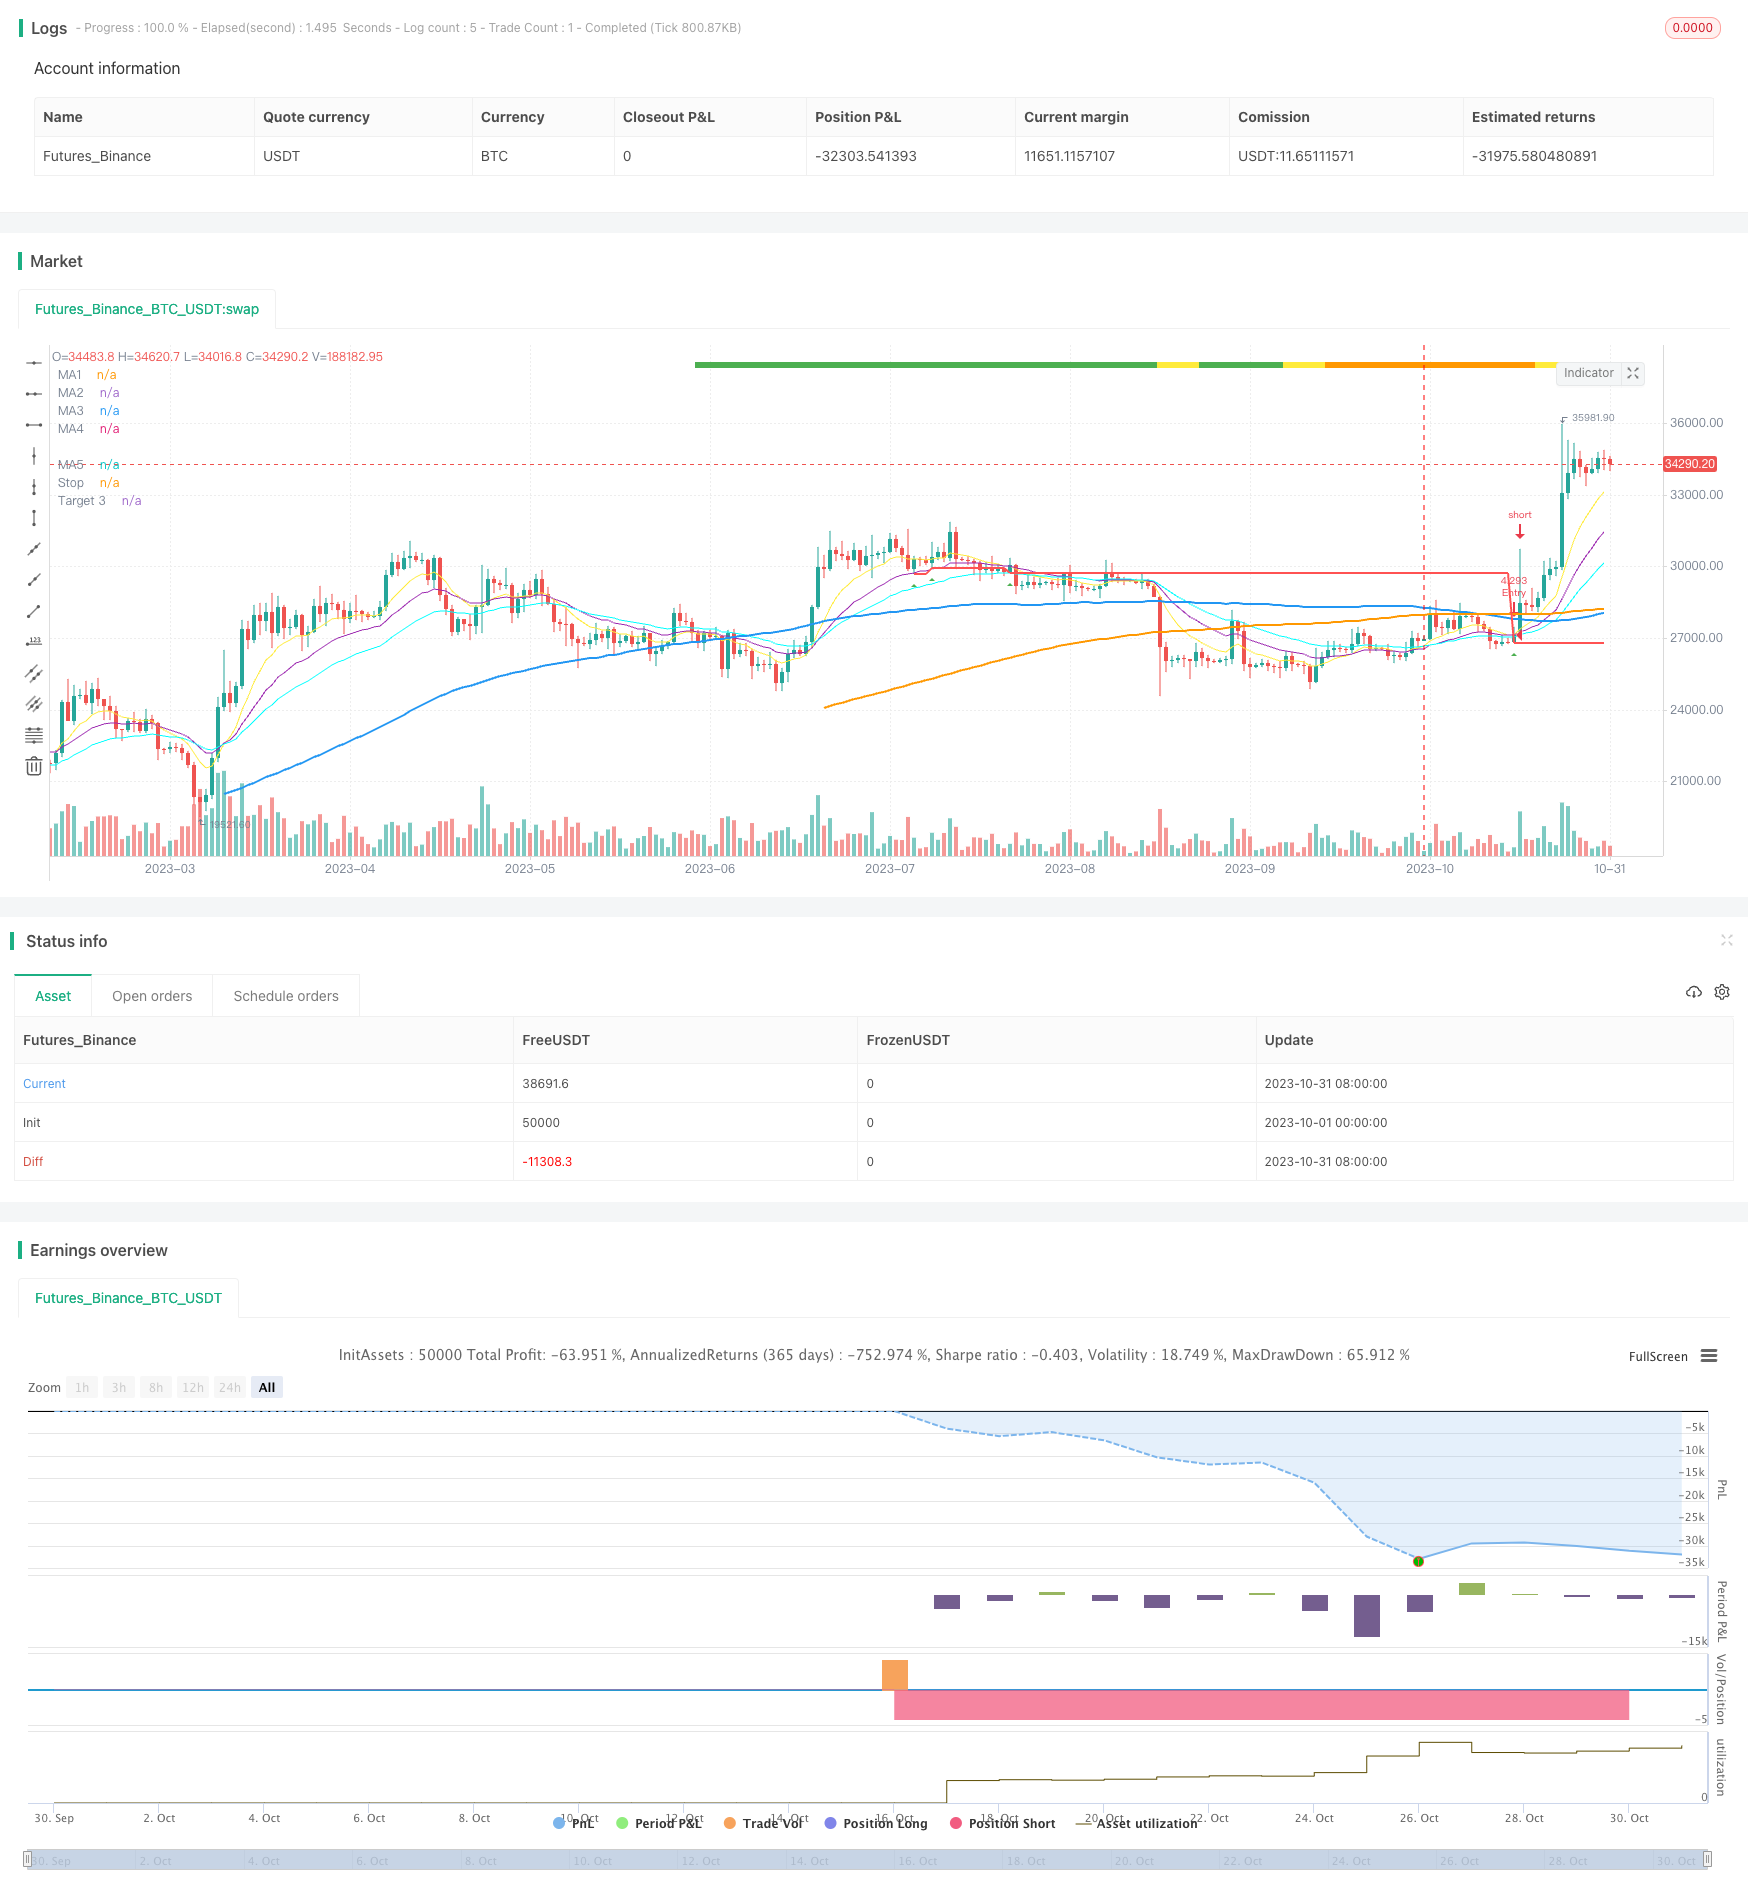
EMAC指数移动平均线交叉优化策略是在基础的EMAC策略上进行参数优化后的版本。该策略融合了趋势判断、多重均线过滤和止损止盈 Exit,旨在抓住中长线趋势进行趋势跟随。
|
|
|
|
## 策略原理
|
|
|
|
1. 判断最近趋势方向:计算过去26周期的收盘价涨跌幅,判断为上升、下降、震荡。
|
|
|
|
2. 多重均线过滤:计算10周期、20周期、34周期的EMA,待它们上穿50周期SMA时产生买入信号。
|
|
|
|
3. ATR止损:Entry信号出现时,止损位设为 Entry柱低点或高点减去2.5ATR。
|
|
|
|
4. 移动止损:随价格上涨逐步向上移动止损线。
|
|
|
|
5. 目标止盈:Entry信号出现时,设置目标位为当时收盘价加上3ATR。
|
|
|
|
6. MA均线回调止损Exit:当价格回破10日EMA时主动止损退出。
|
|
|
|
## 策略优势
|
|
|
|
1. 多重均线过滤增加了信号的可靠性,避免被虚假突破误导。
|
|
|
|
2. 采用ATR止损,可以根据市场波动性设置合理的止损距离。
|
|
|
|
3. 移动止损使止损线逐步向上移动,保护了部分利润。
|
|
|
|
4. 目标止盈设定合理的盈利目标,不贪心,避免把利润吐出。
|
|
|
|
5. MA回调Exit使得在趋势反转时能够及时止损退出。
|
|
|
|
## 策略风险及解决方法
|
|
|
|
1. 在震荡行情中,EMA均线容易形成多次交叉对穿,可能会产生连续亏损的风险。可以适当调大EMA参数,或增加MA金叉过滤条件来降低这种概率。
|
|
|
|
2. ATR数值较大时,止损距离过大,亏损风险增加。可以考虑采用ATR的移动平均值或在ATR上乘以一个缩减比例系数来优化。
|
|
|
|
3. 未考虑夜间隔空风险。可以加入夜间停牌时间段的判断逻辑,避免信号在不能交易的时间出现。
|
|
|
|
4. 没有考虑大盘状态的影响。可以加入对大盘趋势的判断作为策略的开关条件之一,降低在大盘不利情况下的损失。
|
|
|
|
## 策略优化方向
|
|
|
|
1. 可以测试不同长度的EMA参数组合,找到对不同品种更适合的均线长度。
|
|
|
|
2. 可以测试ATR的移动平均值或系数缩减的方法来优化止损距离。
|
|
|
|
3. 可以加入夜间停牌时间段判断逻辑,以规避隔夜风险。
|
|
|
|
4. 可以加入对大盘态势的判断,设置对大盘趋势不利时的开关条件。
|
|
|
|
5. 可以通过反向测试多年历史数据来选择参数组合,使策略在回测中具有最佳稳定性。
|
|
|
|
## 总结
|
|
|
|
EMAC指数移动平均线交叉优化策略结合趋势判断、多重均线过滤和动态止损止盈,旨在跟踪中长线趋势进行长线持有。相较于原始版本进行了参数优化,可望获得更好的实盘表现。但该策略仍需进一步优化与完善,加入更多逻辑判断以应对多种市场情况,降低实盘交易中的风险,提高策略的稳定性和盈利能力。
|
|
|
|
||
|
|
|
|
|
|
## Overview
|
|
|
|
The EMAC Exponential Moving Average Cross Optimized Strategy is an optimized version based on the basic EMAC strategy. It incorporates trend judgment, multiple moving average filtering, and stop loss/take profit exits, aiming to follow mid-to-long term trends.
|
|
|
|
## Strategy Logic
|
|
|
|
1. Judge recent trend direction: calculate the increase/decrease percentage of close price over past 26 weeks to determine uptrend, downtrend or sideways.
|
|
|
|
2. Multiple moving average filter: calculate 10-period, 20-period, 34-period EMA and wait for them to cross above 50-period SMA to trigger buy signals.
|
|
|
|
3. ATR stop loss: when entry signal appears, set stop loss at entry bar's low or high minus 2.5ATR.
|
|
|
|
4. Trailing stop loss: gradually move up stop loss line as price rises.
|
|
|
|
5. Take profit: when entry signal appears, set target at close price plus 3ATR.
|
|
|
|
6. MA pullback exit: actively exit when price breaks back below 10-day EMA.
|
|
|
|
## Advantages
|
|
|
|
1. Multiple MA filter increases signal reliability, avoiding false breakouts.
|
|
|
|
2. ATR stop loss allows reasonable stop distance based on market volatility.
|
|
|
|
3. Trailing stop locks in some profits as it moves up.
|
|
|
|
4. Reasonable profit target avoids giving back too much profit.
|
|
|
|
5. MA pullback exit allows timely exit when trend reverses.
|
|
|
|
## Risks and Solutions
|
|
|
|
1. EMA crosses may whipsaw in sideways markets, causing consecutive losses. Can increase EMA periods or add MA crossover filter.
|
|
|
|
2. Large ATR values can cause stops too far away, increasing loss risk. Can optimize with ATR moving averages or reduction coefficients.
|
|
|
|
3. Overnight gap risk not considered. Can add logic to avoid signals during non-trading periods.
|
|
|
|
4. Market regime not considered. Can add market trend filter as a strategy switch.
|
|
|
|
## Optimization Directions
|
|
|
|
1. Test EMA combinations to find optimal lengths for different products.
|
|
|
|
2. Test ATR moving averages or reduction coefficients to optimize stop distance.
|
|
|
|
3. Add logic to avoid signals during non-trading periods.
|
|
|
|
4. Add market trend filter as a strategy switch when market is unfavorable.
|
|
|
|
5. Backtest parameter combinations over many years to find optimal stability.
|
|
|
|
## Summary
|
|
|
|
The EMAC Exponential Moving Average Cross Optimized Strategy combines trend judgment, multiple MA filtering and dynamic stops to follow mid-to-long term trends. Compared to the original version it has undergone parameter optimization to improve real-trading performance. But further optimizations and enhancements are needed by adding more logic to handle different market situations, reducing risks and improving stability and profitability.
|
|
|
|
[/trans]
|
|
|
|
> Strategy Arguments
|
|
|
|
|
|
|
|
|Argument|Default|Description|
|
|
|----|----|----|
|
|
|v_input_1|2015|Start Year|
|
|
|v_input_2|0|R Static or Percent: Percent|Static|
|
|
|v_input_3|2000|R Size Static|
|
|
|v_input_4|3|R Size Percent|
|
|
|v_input_5|W|Trend Timeframe|
|
|
|v_input_6|26|# of Bars for Trend|
|
|
|v_input_7|15|Trend Growth %|
|
|
|v_input_8|0|Trend Required: Red|Yellow|Orange|Green|
|
|
|v_input_9|10|MA1 Period|
|
|
|v_input_10|0|MA1 Type: EMA|SMA|WMA|
|
|
|v_input_11|20|MA2 Period|
|
|
|v_input_12|0|MA2 Type: EMA|SMA|WMA|
|
|
|v_input_13|34|MA3 Period|
|
|
|v_input_14|0|MA3 Type: EMA|SMA|WMA|
|
|
|v_input_15|100|MA4 Period|
|
|
|v_input_16|0|MA4 Type: SMA|EMA|WMA|
|
|
|v_input_17|200|MA5 Period|
|
|
|v_input_18|0|MA5 Type: SMA|EMA|WMA|
|
|
|v_input_19|0|Enable Short MA Cross Filter: No|Yes|
|
|
|v_input_20|0|Enable Long MA Cross Filter: No|Yes|
|
|
|v_input_21|2.5|Stop ATR Multiple|
|
|
|v_input_22|3|Target Multiple|
|
|
|v_input_23|0|Enable ATR Stops: No|Yes|
|
|
|v_input_24|0|Enable Stops: No|Yes|
|
|
|v_input_25|0|Enable Targets: No|Yes|
|
|
|v_input_26|0|Enable Early Exit: Yes|No|
|
|
|
|
|
|
> Source (PineScript)
|
|
|
|
``` pinescript
|
|
/*backtest
|
|
start: 2023-10-01 00:00:00
|
|
end: 2023-10-31 23:59:59
|
|
period: 1d
|
|
basePeriod: 1h
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
|
*/
|
|
|
|
//@version=4
|
|
//Author = Dustin Drummond https://www.tradingview.com/u/Dustin_D_RLT/
|
|
//Strategy based in part on original 10ema Basic Swing Trade Strategy by Matt Delong: https://www.tradingview.com/u/MattDeLong/
|
|
//Link to original 10ema Basic Swing Trade Strategy: https://www.tradingview.com/script/8yhGnGCM-10ema-Basic-Swing-Trade-Strategy/
|
|
//This is the Original EMAC - Exponential Moving Average Cross Strategy built as a class for reallifetrading dot com and so has all the default settings and has not been optimized
|
|
//I would not recomend using this strategy with the default settings and is for educational purposes only
|
|
//For the fully optimized version please come back around the same time tomorrow 6/16/21 for the EMAC - Exponential Moving Average Cross - Optimized
|
|
//EMAC - Exponential Moving Average Cross
|
|
strategy(title="EMAC - Exponential Moving Average Cross", shorttitle = "EMAC", overlay = true, calc_on_every_tick=false, default_qty_value = 100, initial_capital = 100000, default_qty_type = strategy.fixed, pyramiding = 0, process_orders_on_close=true)
|
|
//creates a time filter to prevent "too many orders error" and allows user to see Strategy results per year by changing input in settings in Stratey Tester
|
|
startYear = input(2015, title="Start Year", minval=1980, step=1)
|
|
timeFilter = true
|
|
//R Size (Risk Amount)
|
|
rStaticOrPercent = input(title="R Static or Percent", defval="Percent", options=["Static", "Percent"])
|
|
rSizeStatic = input(2000, title="R Size Static", minval=1, step=100)
|
|
rSizePercent = input(3, title="R Size Percent", minval=.01, step=.01)
|
|
rSize = rStaticOrPercent == "Static" ? rSizeStatic : rStaticOrPercent == "Percent" ? (rSizePercent * .01 * strategy.equity) : 1
|
|
//Recent Trend Indicator "See the standalone version for detailed description"
|
|
res = input(title="Trend Timeframe", type=input.resolution, defval="W")
|
|
trend = input(26, minval=1, title="# of Bars for Trend")
|
|
trendMult = input(15, minval=0, title="Trend Growth %", step=.25) / 100
|
|
currentClose = security(syminfo.tickerid, res, close)
|
|
pastClose = security(syminfo.tickerid, res, close[trend])
|
|
//Trend Indicator
|
|
upTrend = (currentClose >= (pastClose * (1 + trendMult)))
|
|
downTrend = (currentClose <= (pastClose * (1 - trendMult)))
|
|
sidewaysUpTrend = (currentClose < (pastClose * (1 + trendMult)) and (currentClose > pastClose))
|
|
sidewaysDownTrend = (currentClose > (pastClose * (1 - trendMult)) and (currentClose < pastClose))
|
|
//Plot Trend on Chart
|
|
plotshape(upTrend, "Up Trend", style=shape.square, location=location.top, color=color.green, size=size.small)
|
|
plotshape(downTrend, "Down Trend", style=shape.square, location=location.top, color=color.red, size=size.small)
|
|
plotshape(sidewaysUpTrend, "Sideways Up Trend", style=shape.square, location=location.top, color=color.yellow, size=size.small)
|
|
plotshape(sidewaysDownTrend, "Sideways Down Trend", style=shape.square, location=location.top, color=color.orange, size=size.small)
|
|
//What trend signals to use in entrySignal
|
|
trendRequired = input(title="Trend Required", defval="Red", options=["Green", "Yellow", "Orange", "Red"])
|
|
goTrend = trendRequired == "Orange" ? upTrend or sidewaysUpTrend or sidewaysDownTrend : trendRequired == "Yellow" ? upTrend or sidewaysUpTrend : trendRequired == "Green" ? upTrend : trendRequired == "Red" ? upTrend or sidewaysUpTrend or sidewaysDownTrend or downTrend : na
|
|
//MAs Inputs Defalt is 10 EMA, 20 EMA, 50 EMA, 100 SMA and 200 SMA
|
|
ma1Length = input(10, title="MA1 Period", minval=1, step=1)
|
|
ma1Type = input(title="MA1 Type", defval="EMA", options=["SMA", "EMA", "WMA"])
|
|
ma2Length = input(20, title="MA2 Period", minval=1, step=1)
|
|
ma2Type = input(title="MA2 Type", defval="EMA", options=["SMA", "EMA", "WMA"])
|
|
ma3Length = input(34, title="MA3 Period", minval=1, step=1)
|
|
ma3Type = input(title="MA3 Type", defval="EMA", options=["SMA", "EMA", "WMA"])
|
|
ma4Length = input(100, title="MA4 Period", minval=1, step=1)
|
|
ma4Type = input(title="MA4 Type", defval="SMA", options=["SMA", "EMA", "WMA"])
|
|
ma5Length = input(200, title="MA5 Period", minval=1, step=1)
|
|
ma5Type = input(title="MA5 Type", defval="SMA", options=["SMA", "EMA", "WMA"])
|
|
//MAs defined
|
|
ma1 = ma1Type == "EMA" ? ema(close, ma1Length) : ma1Type == "SMA" ? sma(close, ma1Length) : wma(close, ma1Length)
|
|
ma2 = ma2Type == "EMA" ? ema(close, ma2Length) : ma2Type == "SMA" ? sma(close, ma2Length) : wma(close, ma2Length)
|
|
ma3 = ma3Type == "EMA" ? ema(close, ma3Length) : ma3Type == "SMA" ? sma(close, ma3Length) : wma(close, ma3Length)
|
|
ma4 = ma4Type == "SMA" ? sma(close, ma4Length) : ma4Type == "EMA" ? ema(close, ma4Length) : wma(close, ma4Length)
|
|
ma5 = ma5Type == "SMA" ? sma(close, ma5Length) : ma5Type == "EMA" ? ema(close, ma5Length) : wma(close, ma5Length)
|
|
//Plot MAs
|
|
plot(ma1, title="MA1", color=color.yellow, linewidth=1, style=plot.style_line)
|
|
plot(ma2, title="MA2", color=color.purple, linewidth=1, style=plot.style_line)
|
|
plot(ma3, title="MA3", color=#00FFFF, linewidth=1, style=plot.style_line)
|
|
plot(ma4, title="MA4", color=color.blue, linewidth=2, style=plot.style_line)
|
|
plot(ma5, title="MA5", color=color.orange, linewidth=2, style=plot.style_line)
|
|
//Allows user to toggle on/off ma1 > ma2 filter
|
|
enableShortMAs = input(title="Enable Short MA Cross Filter", defval="No", options=["Yes", "No"])
|
|
shortMACross = enableShortMAs == "Yes" and ma1 > ma2 or enableShortMAs == "No"
|
|
//Allows user to toggle on/off ma4 > ma5 filter
|
|
enableLongMAs = input(title="Enable Long MA Cross Filter", defval="No", options=["Yes", "No"])
|
|
longMACross = enableLongMAs == "Yes" and ma4 >= ma5 or enableLongMAs == "No"
|
|
//Entry Signals
|
|
entrySignal = (strategy.position_size <= 0 and close[1] < ma1[1] and close > ma1 and close > ma2 and close > ma3 and shortMACross and ma1 > ma3 and longMACross and goTrend)
|
|
secondSignal = (strategy.position_size > 0 and close[1] < ma1[1] and close > ma1 and close > ma2 and close > ma3 and shortMACross and ma1 > ma3 and longMACross and goTrend)
|
|
plotshape(entrySignal, style=shape.triangleup, location=location.belowbar, color=color.green, size=size.small)
|
|
plotshape(secondSignal, style=shape.triangleup, location=location.belowbar, color=color.lime, size=size.small)
|
|
//ATR for Stops
|
|
atrValue = (atr(14))
|
|
//to test ATR enable next line
|
|
//plot(atrValue, linewidth=1, color=color.black, style=plot.style_line)
|
|
atrMult = input(2.5, minval=.25, step=.25, title="Stop ATR Multiple")
|
|
//Only target3Mult is used in current strategy target1 and target2 might be used in the future with pyramiding
|
|
//target1Mult = input(1.0, minval=.25, step=.25, title="Targert 1 Multiple")
|
|
//target2Mult = input(2.0, minval=.25, step=.25, title="Targert 2 Multiple")
|
|
target3Mult = input(3.0, minval=.25, step=.25, title="Target Multiple")
|
|
enableAtrStop = input(title="Enable ATR Stops", defval="No", options=["Yes", "No"])
|
|
//Intitial Recomended Stop Location
|
|
atrStop = entrySignal and ((high - (atrMult * atrValue)) < low) ? (high - (atrMult * atrValue)) : low
|
|
//oneAtrStop is used for testing only enable next 2 lines to test
|
|
//oneAtrStop = entrySignal ? (high - atrValue) : na
|
|
//plot(oneAtrStop, "One ATR Stop", linewidth=2, color=color.orange, style=plot.style_linebr)
|
|
initialStop = entrySignal and enableAtrStop == "Yes" ? atrStop : entrySignal ? low : na
|
|
//Stops changed to stoploss to hold value for orders the next line is old code "bug"
|
|
//plot(initialStop, "Initial Stop", linewidth=2, color=color.red, style=plot.style_linebr)
|
|
//Set Initial Stop and hold value "debug code"
|
|
stoploss = valuewhen(entrySignal, initialStop, 0)
|
|
plot(stoploss, title="Stop", linewidth=2, color=color.red)
|
|
enableStops = input(title="Enable Stops", defval="No", options=["Yes", "No"])
|
|
yesStops = enableStops == "Yes" ? 1 : enableStops == "No" ? 0 : na
|
|
//Calculate size of trade based on R Size
|
|
//Original buggy code:
|
|
//positionSize = (rSize/(close - initialStop))
|
|
//Added a minimum order size of 1 "debug code"
|
|
positionSize = (rSize/(close - initialStop)) > 1 ? (rSize/(close - initialStop)) : 1
|
|
//Targets
|
|
//Enable or Disable Targets
|
|
enableTargets = input(title="Enable Targets", defval="No", options=["Yes", "No"])
|
|
yesTargets = enableTargets == "Yes" ? 1 : enableTargets == "No" ? 0 : na
|
|
//Only target3 is used in current strategy target1 and target2 might be used in the future with pyramiding
|
|
//target1 = entrySignal ? (close + ((close - initialStop) * target1Mult)) : na
|
|
//target2 = entrySignal ? (close + ((close - initialStop) * target2Mult)) : na
|
|
target3 = entrySignal ? (close + ((close - initialStop) * target3Mult)) : na
|
|
//plot(target1, "Target 1", linewidth=2, color=color.green, style=plot.style_linebr)
|
|
//plot(target2, "Target 2", linewidth=2, color=color.green, style=plot.style_linebr)
|
|
plot(target3, "Target 3", linewidth=2, color=color.green, style=plot.style_linebr)
|
|
//Set Target and hold value "debug code"
|
|
t3 = valuewhen(entrySignal, target3, 0)
|
|
//To test t3 and see plot enable next line
|
|
//plot(t3, title="Target", linewidth=2, color=color.green)
|
|
//MA1 Cross Exit
|
|
enableEarlyExit = input(title="Enable Early Exit", defval="Yes", options=["Yes", "No"])
|
|
earlyExit = enableEarlyExit == "Yes" ? 1 : enableEarlyExit == "No" ? 0 : na
|
|
ma1CrossExit = strategy.position_size > 0 and close < ma1
|
|
//Entry Order
|
|
strategy.order("Entry", long = true, qty = positionSize, when = (strategy.position_size <= 0 and entrySignal and timeFilter))
|
|
//Early Exit Order
|
|
strategy.close_all(when = ma1CrossExit and timeFilter and earlyExit, comment = "MA1 Cross Exit")
|
|
//Stop and Target Orders
|
|
//strategy.cancel orders are needed to prevent bug with Early Exit Order
|
|
strategy.order("Stop Loss", false, qty = strategy.position_size, stop=stoploss, oca_name="Exit", when = timeFilter and yesStops, comment = "Stop Loss")
|
|
strategy.cancel("Stop Loss", when = ma1CrossExit and timeFilter and earlyExit)
|
|
strategy.order("Target", false, qty = strategy.position_size, limit=t3, oca_name="Exit", when = timeFilter and yesTargets, comment = "Target")
|
|
strategy.cancel("Target", when = ma1CrossExit and timeFilter and earlyExit)
|
|
```
|
|
|
|
> Detail
|
|
|
|
https://www.fmz.com/strategy/431395
|
|
|
|
> Last Modified
|
|
|
|
2023-11-07 15:16:03
|