
8.1 KiB
Name
布林带与RSI交易策略-Bollinger-Bands-and-RSI-Trading-Strategy
Author
ChaoZhang
Strategy Description
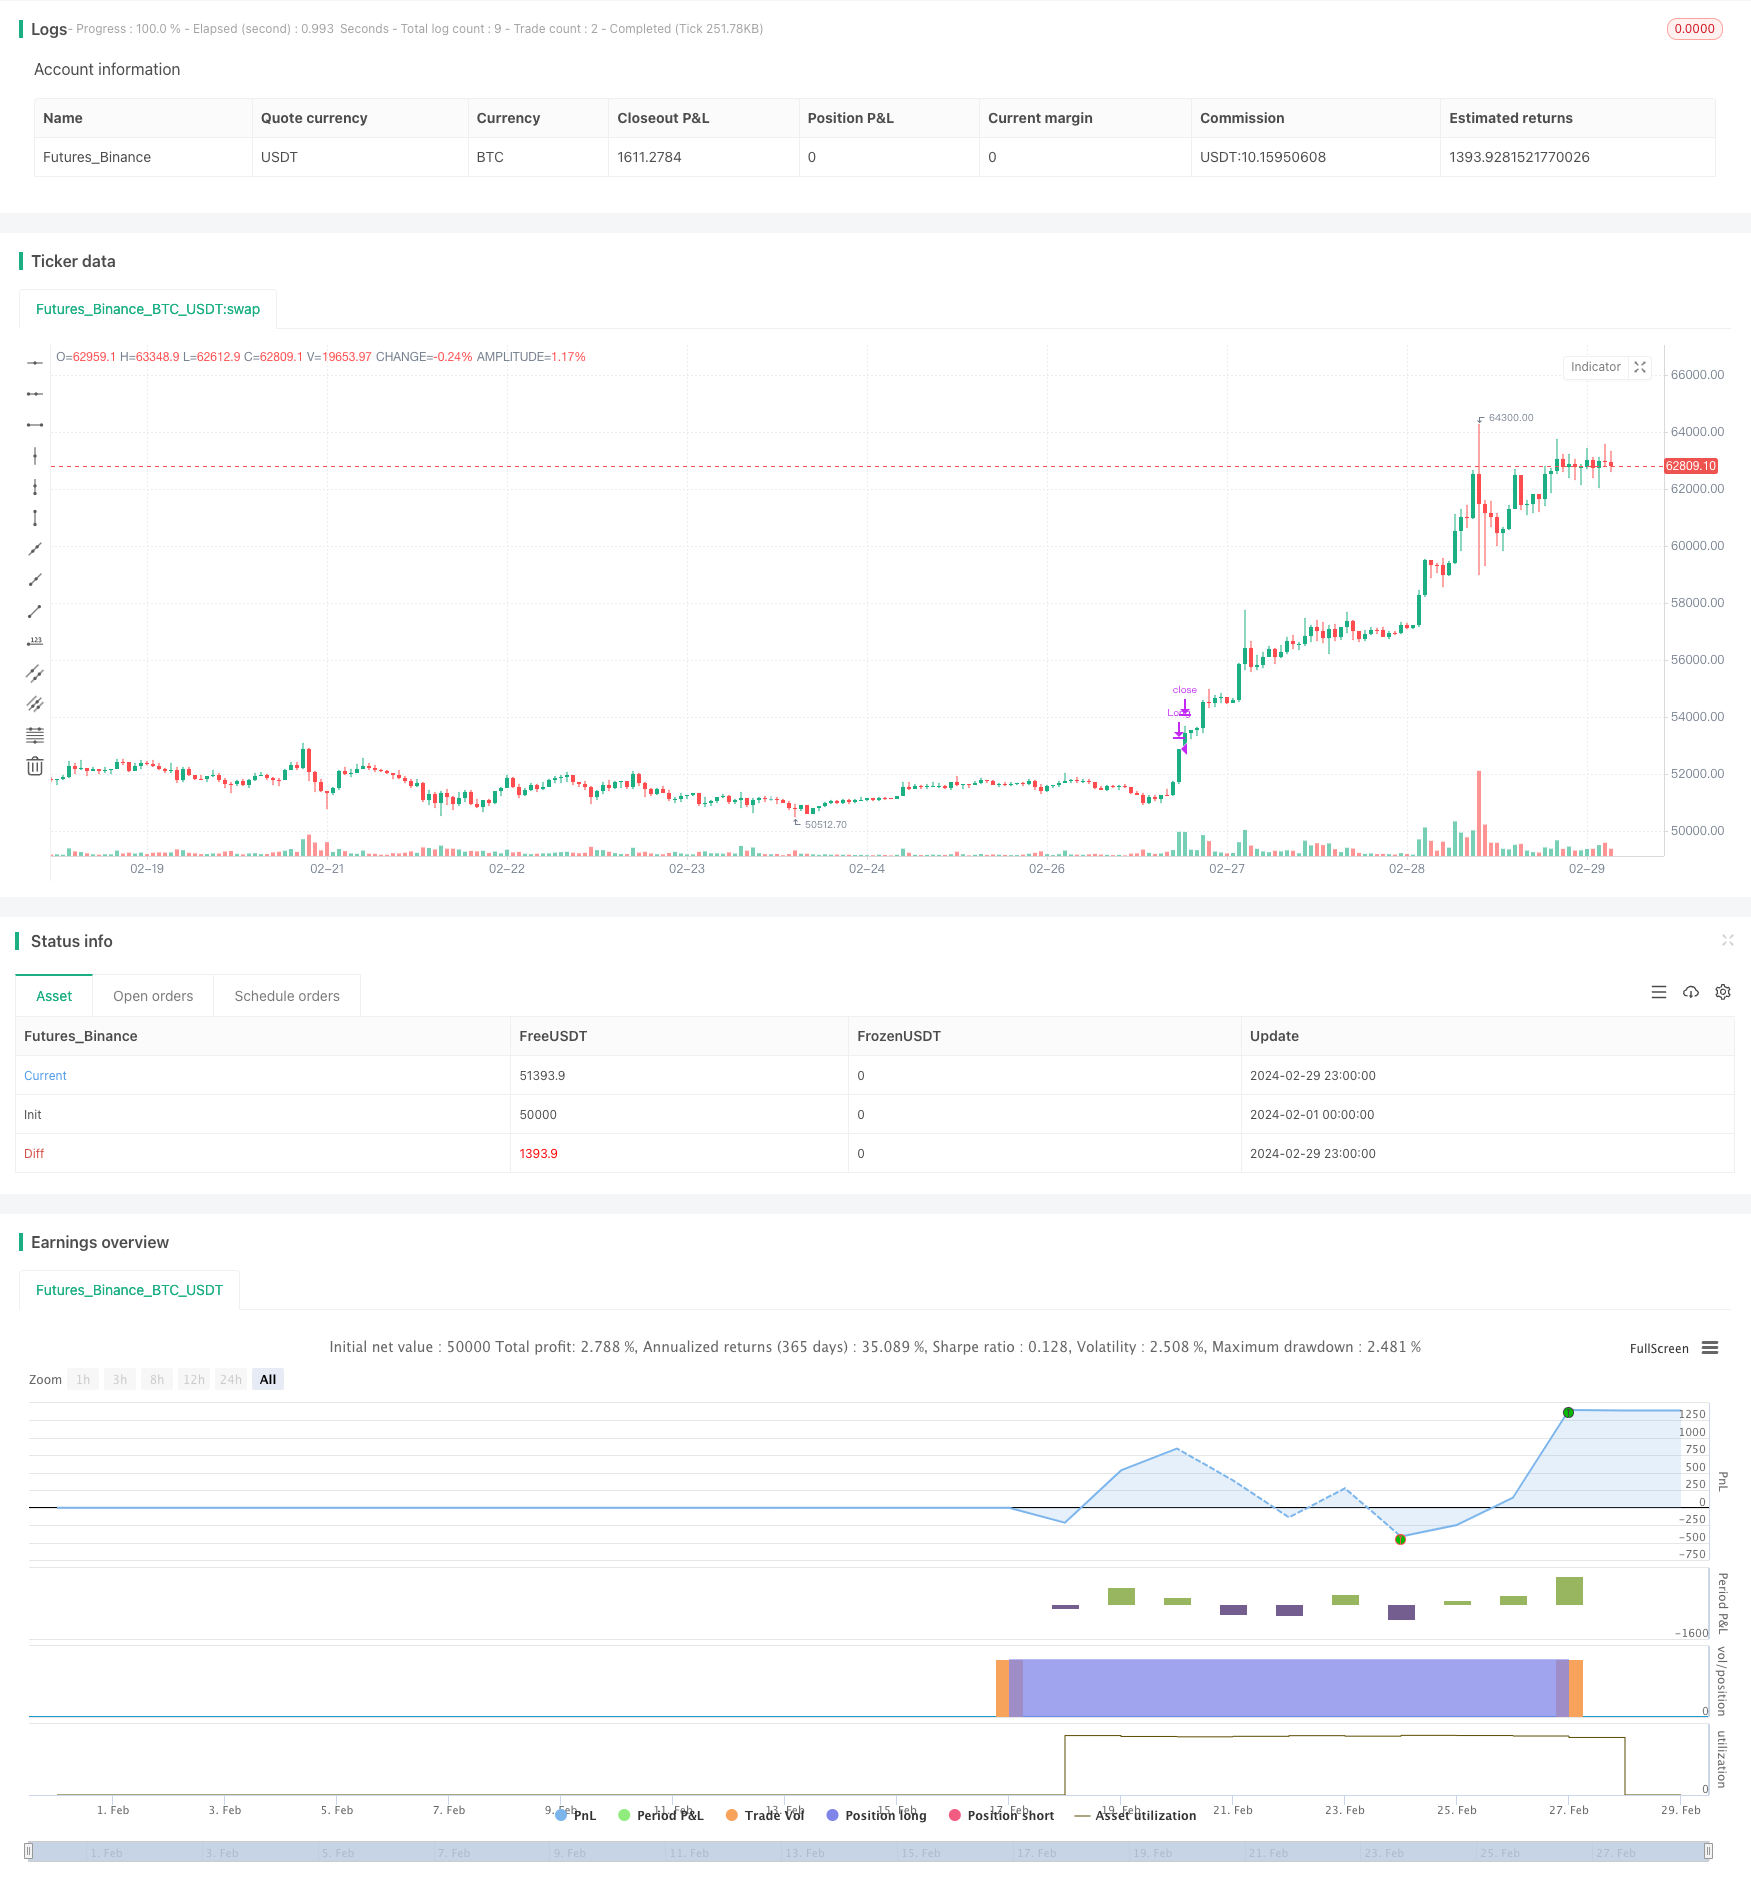
[trans]
概述
该策略结合布林带和相对强弱指标(RSI)来判断买卖信号。当价格突破布林带下轨且RSI低于设定的下限时产生买入信号;当价格突破布林带上轨且RSI高于设定的上限时产生卖出信号。同时,该策略还引入了买入间隔参数,避免频繁交易,有利于实现金字塔式仓位管理。
策略原理
- 计算RSI指标,用于衡量价格的超买超卖情况。
- 计算布林带上下轨,用于判断价格的突破情况。
- 结合RSI和布林带设定买卖信号:
- 当收盘价低于布林带下轨且RSI低于设定的下限水平时,产生买入信号。
- 当收盘价高于布林带上轨且RSI高于设定的上限水平时,产生卖出信号。
- 引入买入间隔参数,限制连续买入的频率,便于实现金字塔式仓位管理。
策略优势
- 双重确认:策略同时使用布林带和RSI两个指标,可以更可靠地捕捉趋势拐点,降低假信号风险。
- 金字塔式建仓:通过设置买入间隔参数,策略可以在趋势确立后逐步加仓,有利于控制风险和优化收益。
- 参数灵活:用户可以根据市场特点和个人偏好,灵活设置RSI上下限和买入间隔等参数。
策略风险
- 趋势延续风险:如果价格在突破布林带后出现短暂回撤,可能导致策略过早平仓,错失后续趋势。
- 参数优化风险:不同市场环境下,最优参数组合可能差异较大,策略可能面临过拟合风险。
- 黑天鹅事件:策略基于历史数据构建,可能无法有效应对极端行情。
策略优化方向
- 引入止损止盈:在策略中加入移动止损或固定止损止盈逻辑,以进一步控制单笔交易风险。
- 动态参数优化:根据市场状态的变化,动态调整RSI上下限和买入间隔等参数,提高策略适应性。
- 结合其他技术指标:引入其他趋势类或摆动类指标作为辅助判断,提高策略稳健性。
总结
该策略巧妙地结合了布林带和RSI两个经典技术指标,通过双重确认机制来捕捉趋势性机会。同时,策略引入了金字塔式建仓方法,在控制风险的同时力求优化收益。但策略也存在趋势延续风险、参数优化风险和黑天鹅事件风险,未来可以通过引入止损止盈、动态参数优化和结合其他指标等方式进一步优化。总的来说,这是一个思路清晰、逻辑严谨的量化交易策略,值得进一步探索和实践。
||
Overview
This strategy combines Bollinger Bands and the Relative Strength Index (RSI) to generate buy and sell signals. A buy signal is triggered when the price breaks below the lower Bollinger Band and the RSI is below a specified lower level. A sell signal is triggered when the price breaks above the upper Bollinger Band and the RSI is above a specified upper level. Additionally, the strategy introduces a buy interval parameter to avoid frequent trading, which is conducive to pyramid position management.
Strategy Principles
- Calculate the RSI indicator to measure overbought and oversold conditions.
- Calculate the upper and lower Bollinger Bands to determine price breakouts.
- Set buy and sell signals based on RSI and Bollinger Bands:
- A buy signal is generated when the closing price is below the lower Bollinger Band and the RSI is below the specified lower level.
- A sell signal is generated when the closing price is above the upper Bollinger Band and the RSI is above the specified upper level.
- Introduce a buy interval parameter to limit the frequency of consecutive buys, facilitating pyramid position management.
Strategy Advantages
- Double confirmation: The strategy uses both Bollinger Bands and RSI indicators, providing more reliable trend reversal detection and reducing false signals.
- Pyramid position building: By setting a buy interval parameter, the strategy gradually adds positions as the trend is established, which helps control risk and optimize returns.
- Flexible parameters: Users can flexibly set RSI upper and lower levels and buy interval parameters according to market characteristics and personal preferences.
Strategy Risks
- Trend continuation risk: If the price experiences a short pullback after breaking through the Bollinger Bands, the strategy may close positions prematurely and miss subsequent trends.
- Parameter optimization risk: The optimal parameter combination may vary significantly in different market environments, and the strategy may face overfitting risks.
- Black swan events: The strategy is built based on historical data and may not effectively handle extreme market conditions.
Strategy Optimization Directions
- Introduce stop-loss and take-profit: Add trailing stop or fixed stop-loss and take-profit logic to the strategy to further control individual trade risks.
- Dynamic parameter optimization: Dynamically adjust parameters such as RSI upper and lower levels and buy intervals based on changes in market conditions to improve strategy adaptability.
- Combine with other technical indicators: Introduce other trend or oscillator indicators as auxiliary judgments to enhance strategy robustness.
Summary
This strategy cleverly combines two classic technical indicators: Bollinger Bands and RSI. It utilizes a double confirmation mechanism to capture trending opportunities. At the same time, the strategy introduces a pyramid position-building method to control risk while optimizing returns. However, the strategy also faces risks such as trend continuation risk, parameter optimization risk, and black swan event risk. In the future, the strategy can be further optimized by introducing stop-loss and take-profit, dynamic parameter optimization, and combining with other indicators. Overall, this is a clear-cut and logically rigorous quantitative trading strategy that is worth further exploration and practice.
[/trans]
Strategy Arguments
| Argument | Default | Description |
|---|---|---|
| v_input_1 | true | GoTradePlz |
| v_input_2 | 30 | RSI 下限水平 |
| v_input_3 | 70 | RSI 上限水平 |
| v_input_4 | 5 | 购买间隔(K线数量) |
Source (PineScript)
/*backtest
start: 2024-02-01 00:00:00
end: 2024-02-29 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/

//@version=4
strategy(overlay=true, shorttitle="cakes'Strategy For RSI", default_qty_type = strategy.percent_of_equity, initial_capital = 100000, default_qty_value = 100, pyramiding = 0, title="cakes'Strategy", currency = 'USD')

////////// ** Inputs ** //////////

// Stoploss and Profits Inputs

v1 = input(true, title="GoTradePlz")

////////// ** Indicators ** //////////

// RSI

len = 14
src = close
up = rma(max(change(src), 0), len)
down = rma(-min(change(src), 0), len)
rsi = down == 0 ? 100 : up == 0 ? 0 : 100 - 100 / (1 + up / down)


//  Bollinger Bands

length1 = 20
src1 = close
mult1 = 1.0
basis1 = sma(src1, length1)
dev1 = mult1 * stdev(src1, length1)
upper1 = basis1 + dev1
lower1 = basis1 - dev1


////////// ** Triggers and Guards ** //////////


// 输入
RSILowerLevel1 = input(30, title="RSI 下限水平")
RSIUpperLevel1 = input(70, title="RSI 上限水平")

// 购买间隔
buyInterval = input(5, title="购买间隔(K线数量)")

// 跟踪购买间隔
var int lastBuyBar = na
lastBuyBar := na(lastBuyBar[1]) ? bar_index : lastBuyBar

// 策略信号
BBBuyTrigger1 = close < lower1
BBSellTrigger1 = close > upper1
rsiBuyGuard1 = rsi < RSILowerLevel1
rsiSellGuard1 = rsi > RSIUpperLevel1

Buy_1 = BBBuyTrigger1 and rsiBuyGuard1 and (bar_index - lastBuyBar) >= buyInterval
Sell_1 = BBSellTrigger1 and rsiSellGuard1

if (Buy_1)
    lastBuyBar := bar_index

strategy.entry("Long", strategy.long, when = Buy_1, alert_message = "Buy Signal!")
strategy.close("Long", when = Sell_1, alert_message = "Sell Signal!")
Detail
https://www.fmz.com/strategy/446465
Last Modified
2024-03-28 18:11:08