
164 lines
7.7 KiB
Markdown
164 lines
7.7 KiB
Markdown
|
|
> Name
|
|
|
|
基于波动率突破和多重技术指标的混合交易策略-Hybrid-Trading-Strategy-Based-on-Volatility-Breakout-and-Multiple-Technical-Indicators
|
|
|
|
> Author
|
|
|
|
ianzeng123
|
|
|
|
> Strategy Description
|
|
|
|
|
|
|
|
|
|
|
|
|
|
[trans]
|
|
#### 概述
|
|
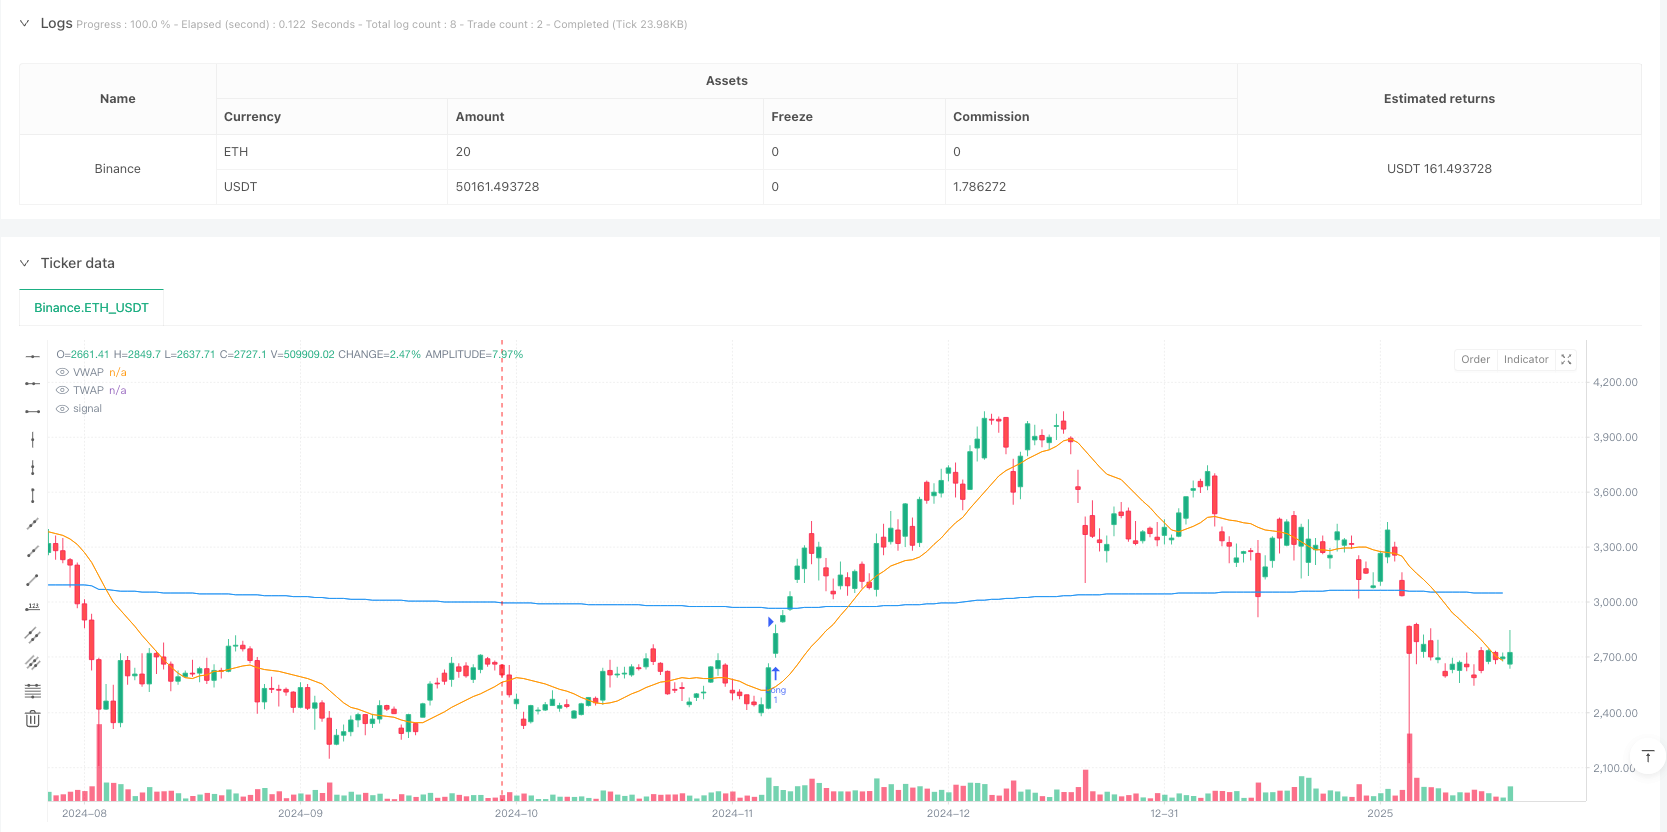
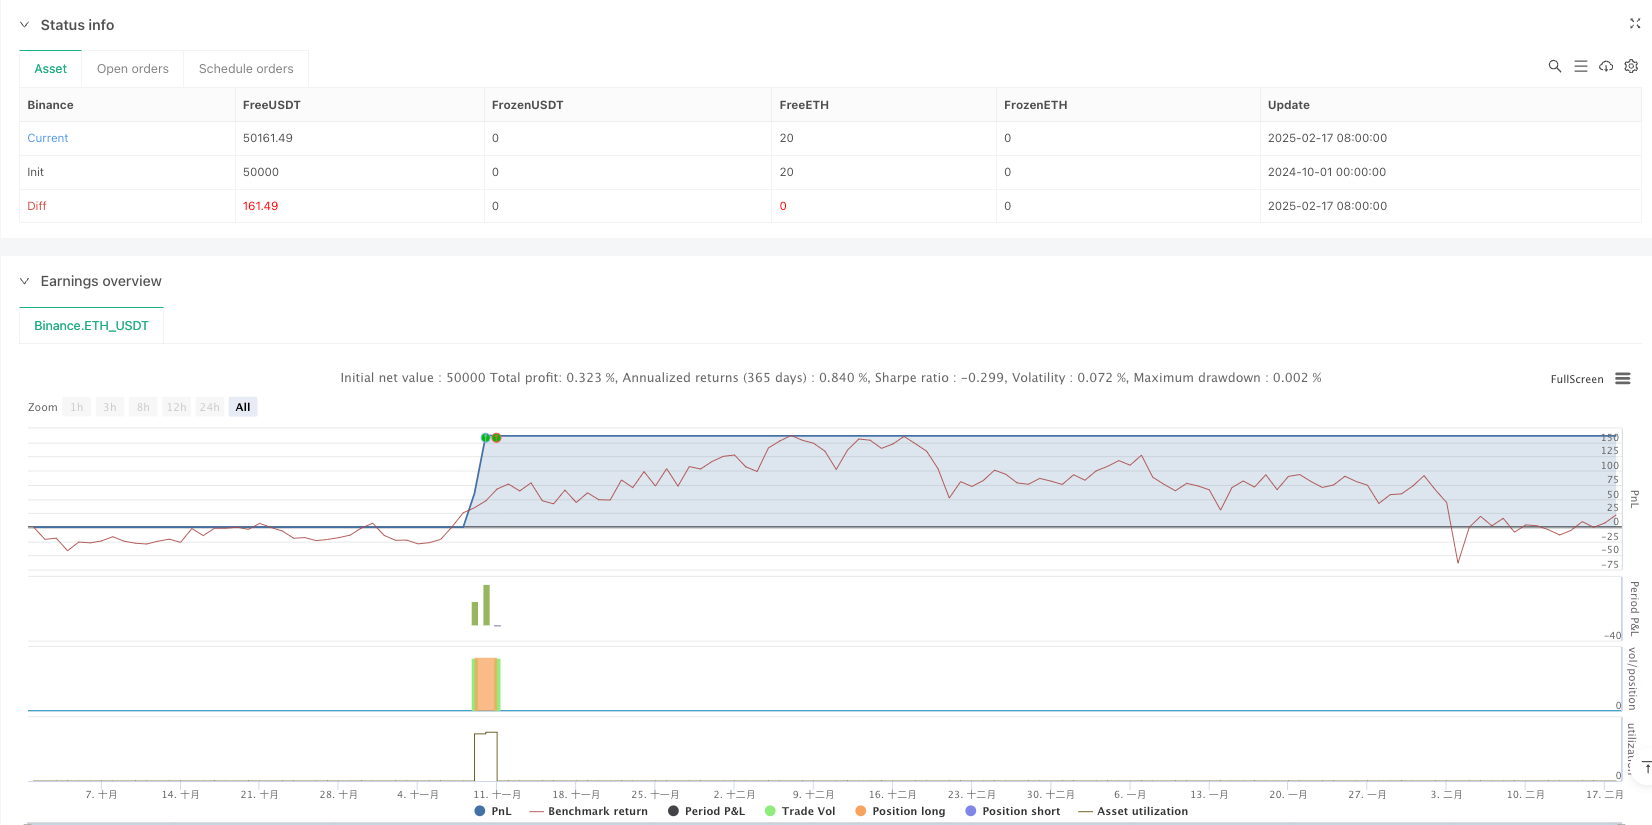
该策略是一个基于多重技术指标的混合交易系统,结合了成交量加权平均价格(VWAP)、时间加权平均价格(TWAP)、波动率突破和形态识别等多个维度的分析方法。策略通过整合多个技术指标的信号来确定市场入场和出场时机,同时结合成交量确认来提高交易的可靠性。
|
|
|
|
#### 策略原理
|
|
策略的核心逻辑基于以下几个关键组件:
|
|
1. 使用VWAP和TWAP双重均线系统作为价格趋势的参考基准
|
|
2. 通过布林带结合ATR指标进行波动率突破判断
|
|
3. 采用简单的头肩形态和三角形态识别模式
|
|
4. 将成交量作为交易确认的必要条件
|
|
5. 设置基于ATR的动态止盈止损位置
|
|
|
|
当价格突破布林带上轨、出现技术形态信号且伴随高成交量时,系统产生做多信号。而当价格失去突破动能且出现技术形态时,系统会平仓已有持仓。系统的止盈设置为入场价格加2倍ATR,止损设置为入场价格减1.5倍ATR。
|
|
|
|
#### 策略优势
|
|
1. 多维度信号确认机制显著提高了交易的可靠性
|
|
2. 动态的止盈止损设置能够根据市场波动情况自适应调整
|
|
3. 结合成交量确认可以有效过滤虚假突破
|
|
4. 使用VWAP和TWAP双重均线提供了更稳定的价格参考
|
|
5. 策略逻辑清晰,便于后续优化和调整
|
|
|
|
#### 策略风险
|
|
1. 多重条件确认可能导致错过部分交易机会
|
|
2. 在震荡市场中可能产生频繁的假突破信号
|
|
3. 形态识别的简化处理可能导致误判
|
|
4. 高成交量确认条件在低流动性市场可能不适用
|
|
5. 固定倍数的ATR止盈止损设置可能不适合所有市场环境
|
|
|
|
#### 策略优化方向
|
|
1. 引入市场环境识别机制,在不同市场条件下动态调整策略参数
|
|
2. 改进形态识别算法,增加更多技术形态的支持
|
|
3. 优化成交量确认阈值,使其能够适应不同市场的流动性特征
|
|
4. 加入趋势强度过滤器,提高交易信号的质量
|
|
5. 开发更智能的止盈止损机制,可以根据市场特征动态调整
|
|
|
|
#### 总结
|
|
这是一个融合多个技术分析维度的综合交易策略,通过多重信号确认来提高交易的可靠性。策略的核心优势在于其多维度的分析方法和严格的交易条件,这有助于降低虚假信号的风险。虽然策略存在一些需要优化的地方,但整体框架具有良好的扩展性和适应性。通过持续优化和调整,该策略有潜力在不同市场环境下保持稳定的表现。 ||
|
|
|
|
#### Overview
|
|
This strategy is a hybrid trading system based on multiple technical indicators, combining Volume Weighted Average Price (VWAP), Time Weighted Average Price (TWAP), volatility breakout, and pattern recognition analysis methods. The strategy determines market entry and exit timing by integrating signals from multiple technical indicators while incorporating volume confirmation to enhance trading reliability.
|
|
|
|
#### Strategy Principles
|
|
The core logic of the strategy is based on the following key components:
|
|
1. Using VWAP and TWAP dual moving average system as price trend reference
|
|
2. Volatility breakout judgment through Bollinger Bands combined with ATR indicator
|
|
3. Simple head and shoulders and triangle pattern recognition
|
|
4. Using volume as a necessary condition for trade confirmation
|
|
5. Setting dynamic take-profit and stop-loss levels based on ATR
|
|
|
|
The system generates long signals when price breaks above the Bollinger Band upper band, technical patterns appear, and high volume is present. When price loses breakthrough momentum and technical patterns appear, the system closes existing positions. The take-profit is set at entry price plus 2 times ATR, and stop-loss is set at entry price minus 1.5 times ATR.
|
|
|
|
#### Strategy Advantages
|
|
1. Multi-dimensional signal confirmation mechanism significantly improves trading reliability
|
|
2. Dynamic take-profit and stop-loss settings adapt to market volatility
|
|
3. Volume confirmation effectively filters false breakouts
|
|
4. VWAP and TWAP dual moving averages provide more stable price reference
|
|
5. Clear strategy logic facilitates subsequent optimization and adjustment
|
|
|
|
#### Strategy Risks
|
|
1. Multiple condition confirmation may lead to missed trading opportunities
|
|
2. May generate frequent false breakout signals in ranging markets
|
|
3. Simplified pattern recognition processing may lead to misjudgments
|
|
4. High volume confirmation conditions may not be suitable for low liquidity markets
|
|
5. Fixed multiple ATR take-profit and stop-loss settings may not suit all market environments
|
|
|
|
#### Strategy Optimization Directions
|
|
1. Introduce market environment recognition mechanism to dynamically adjust strategy parameters under different market conditions
|
|
2. Improve pattern recognition algorithm to support more technical patterns
|
|
3. Optimize volume confirmation thresholds to adapt to different market liquidity characteristics
|
|
4. Add trend strength filter to improve trading signal quality
|
|
5. Develop smarter take-profit and stop-loss mechanisms that can dynamically adjust based on market characteristics
|
|
|
|
#### Summary
|
|
This is a comprehensive trading strategy that integrates multiple technical analysis dimensions, using multiple signal confirmations to improve trading reliability. The core advantage of the strategy lies in its multi-dimensional analysis method and strict trading conditions, which help reduce the risk of false signals. Although there are aspects that need optimization, the overall framework has good scalability and adaptability. Through continuous optimization and adjustment, this strategy has the potential to maintain stable performance in different market environments.
|
|
[/trans]
|
|
|
|
|
|
|
|
> Source (PineScript)
|
|
|
|
``` pinescript
|
|
/*backtest
|
|
start: 2024-10-01 00:00:00
|
|
end: 2025-02-18 08:00:00
|
|
period: 1d
|
|
basePeriod: 1d
|
|
exchanges: [{"eid":"Binance","currency":"ETH_USDT"}]
|
|
*/
|
|
|
|
//@version=6
|
|
strategy("Hybrid Money Making Trading Strategy", overlay=true)
|
|
|
|
// VWAP Calculation
|
|
cumulative_vp = ta.cum(volume * close)
|
|
cumulative_vol = ta.cum(volume)
|
|
vwap = cumulative_vp / cumulative_vol
|
|
plot(vwap, title="VWAP", color=color.blue)
|
|
|
|
// TWAP Calculation
|
|
twap = ta.sma((high + low + close) / 3, 14)
|
|
plot(twap, title="TWAP", color=color.orange)
|
|
|
|
// Volatility Breakout
|
|
atr = ta.atr(14)
|
|
bb_upper = ta.sma(close, 20) + 2 * ta.stdev(close, 20)
|
|
bb_lower = ta.sma(close, 20) - 2 * ta.stdev(close, 20)
|
|
volatility_breakout = close > bb_upper
|
|
|
|
// Pattern Recognition (Basic Example)
|
|
head_shoulders = ta.crossover(close, ta.sma(close, 50))
|
|
triangle_pattern = ta.crossover(ta.sma(close, 10), ta.sma(close, 50))
|
|
pattern_signal = head_shoulders or triangle_pattern
|
|
|
|
// Volume Confirmation (Require high volume for entry)
|
|
vol_avg = ta.sma(volume, 20)
|
|
high_volume = volume > 1.5 * vol_avg
|
|
|
|
// Buy/Sell Signal Conditions
|
|
buy_signal = volatility_breakout and pattern_signal and high_volume
|
|
sell_signal = not volatility_breakout and pattern_signal
|
|
|
|
// Track Latest Signal
|
|
var float last_signal_price = na
|
|
var string last_signal_type = ""
|
|
if buy_signal
|
|
last_signal_price := close
|
|
last_signal_type := "BUY"
|
|
if sell_signal
|
|
last_signal_price := close
|
|
last_signal_type := "SELL"
|
|
|
|
// Strategy Entry & Exit
|
|
if buy_signal
|
|
strategy.entry("Long", strategy.long)
|
|
strategy.exit("TakeProfit", from_entry="Long", stop=close - 1.5 * atr, limit=close + 2 * atr)
|
|
if sell_signal
|
|
strategy.close("Long")
|
|
|
|
```
|
|
|
|
> Detail
|
|
|
|
https://www.fmz.com/strategy/482780
|
|
|
|
> Last Modified
|
|
|
|
2025-02-20 15:01:24
|