
194 lines
8.1 KiB
Markdown
194 lines
8.1 KiB
Markdown
|
|
> Name
|
|
|
|
基于交易量强弱的趋势跟踪策略Volume-Flow-Indicator-Based-Trend-Following-Strategy
|
|
|
|
> Author
|
|
|
|
ChaoZhang
|
|
|
|
> Strategy Description
|
|
|
|
|
|
|
|
[trans]
|
|
|
|
## 概述
|
|
|
|
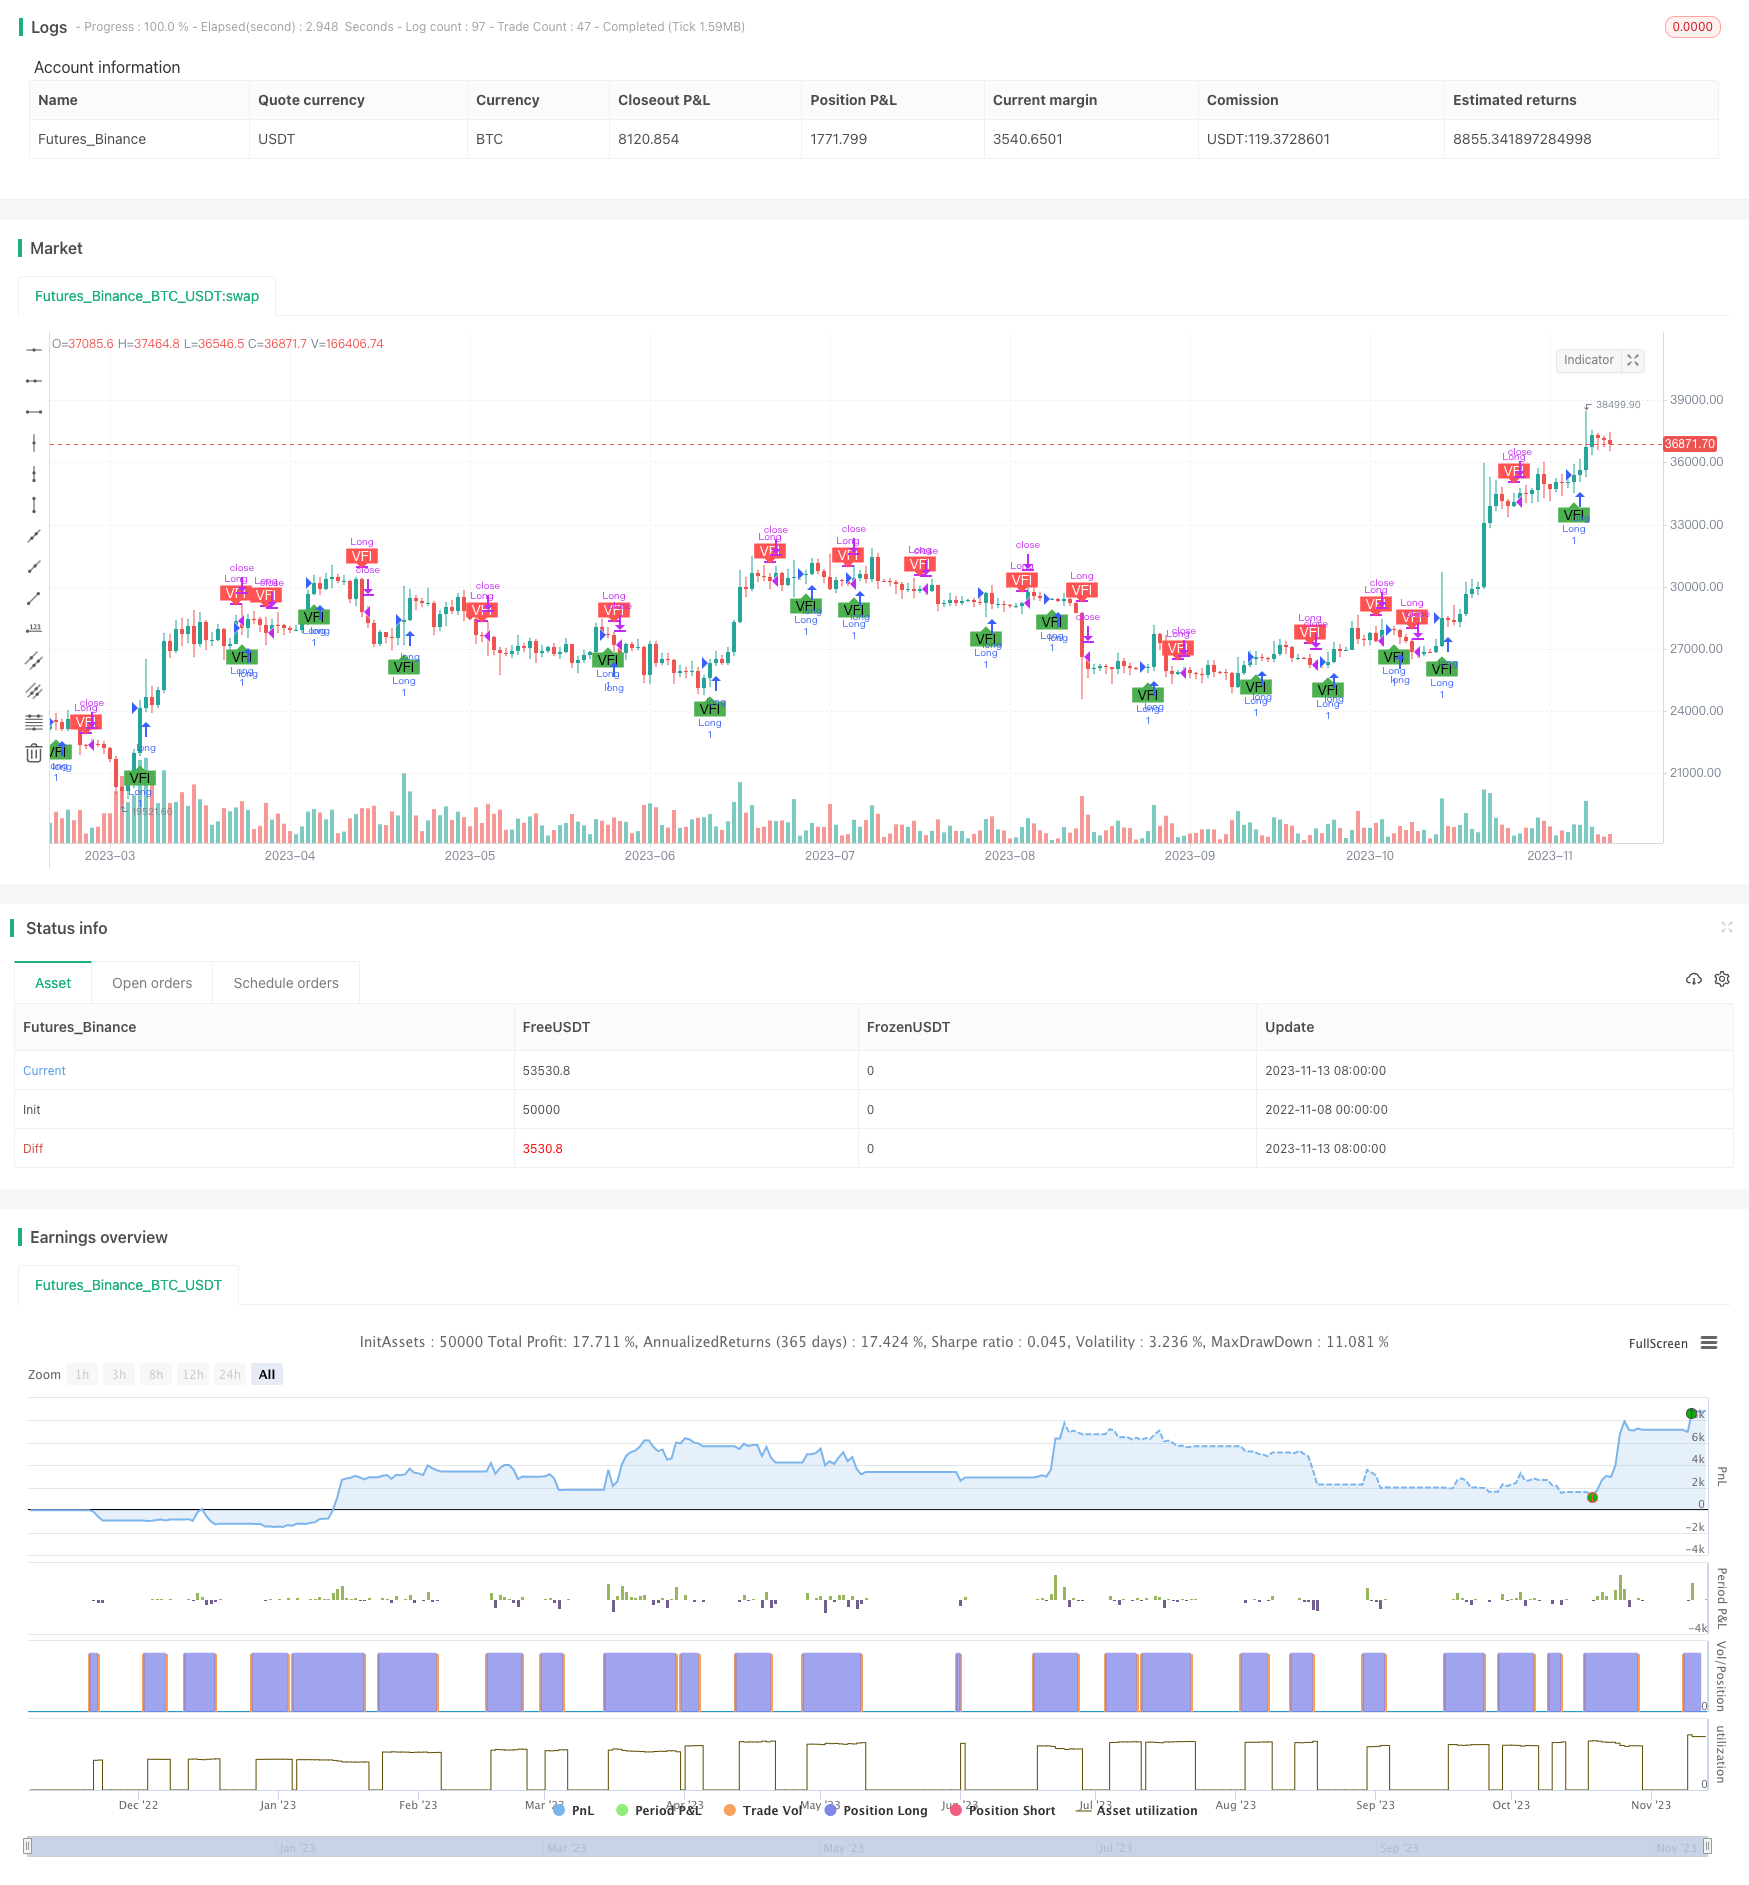
本策略通过计算交易量变化情况,判断市场趋势方向,采用趋势跟踪方式,在趋势开始阶段建立仓位,在趋势结束时平仓止损。
|
|
|
|
## 策略原理
|
|
|
|
1. 计算典型价格typical,对数收益率inter,收益率方差vinter
|
|
2. 计算交易量平均值vave,最大交易量阈值vmax
|
|
3. 计算价格变化量mf,与方差阈值cutoff比较,计算出价格驱动量vcp
|
|
4. 汇总vcp得到量价指标vfi,分别计算vfi和其均线vfima
|
|
5. 比较vfi和vfima大小,得到量价指标差值dVFI,以判定趋势方向
|
|
6. 当dVFI上穿0时为看涨信号,下穿0时为看跌信号
|
|
7. 根据dVFI形态,建立做多做空策略
|
|
|
|
## 策略优势分析
|
|
|
|
1. 该策略充分考虑了交易量变化对趋势判断的影响,通过动量指标衡量趋势强弱,可以更准确地捕捉趋势转折点。
|
|
2. 策略加入交易量阈值计算,可以过滤正常波动,只捕捉大资金的集体行为,避免被市场噪音误导。
|
|
3. 量价联动判断,综合考量价格与成交量,可以有效避免假突破。
|
|
4. 采用均线过滤和逻辑判断,可以过滤掉大部分假信号。
|
|
5. 跟踪趋势而非预测反转,非常适合中长线趋势交易,有利于把握市场主要方向。
|
|
|
|
## 策略风险分析
|
|
|
|
1. 该策略主要依赖交易量变化来判断趋势,在交易量不活跃的品种中效果会打折扣。
|
|
2. 交易量数据容易被操纵,可能产生误导性信号,需要防范量价背离的情况。
|
|
3. 量价关系经常有滞后,可能错过趋势开始的最佳入场时机。
|
|
4. 粗放的止损方式可能会过早止损,无法持续捕捉趋势。
|
|
5. 无法有效响应短期调整,对突发事件也可能反应不敏感。
|
|
|
|
可以考虑加入均线系统、波动率指标等来优化入场和止损;结合更多数据源分析量价关系,防范误导信号;加入适当技术指标提升对短期调整的响应。
|
|
|
|
## 策略优化方向
|
|
|
|
1. 优化入场条件,可以考虑加入均线、자세오극점等判断,在趋势开始后确定入场。
|
|
|
|
2. 优化止损方式,可以设定移动止损、级别止损等,让止损更贴近价格,跟踪趋势停止。
|
|
|
|
3. 加入趋势判断环节,如ADX,可以避免横盘和震荡市场的错误交易。
|
|
|
|
4. 优化参数设置,可以通过更长的数据回测寻找最优参数组合。
|
|
|
|
5. 将策略扩展到更多品种,寻找质量更好、交易量更活跃的品种。
|
|
|
|
6. 考虑加入机器学习模型,利用更多数据进行量价关系判断,提升信号质量。
|
|
|
|
## 总结
|
|
|
|
本策略整体思路清晰,核心指标直观易懂,可靠地识别趋势方向。策略优势在于强调交易量变化,适合追踪中长线趋势,但需防范误导信号。通过参数优化、止损方式改进、指标优化组合等方面进行改进,可以进一步增强策略的实盘表现。
|
|
|
|
||
|
|
|
|
## Overview
|
|
|
|
This strategy judges market trend direction by calculating changes in trading volume, and adopts a trend following approach by establishing positions at the beginning of trends and closing positions when trends end.
|
|
|
|
## Strategy Logic
|
|
|
|
1. Calculate typical price typical, logarithmic return inter, and return variance vinter
|
|
2. Calculate average trading volume vave, maximum trading volume threshold vmax
|
|
3. Calculate price change mf, compare with variance threshold cutoff to get price driven momentum vcp
|
|
4. Sum vcp to get volume price indicator vfi, calculate vfi and its moving average vfima
|
|
5. Compare vfi with vfima to get the difference dVFI and determine trend direction
|
|
6. When dVFI crosses above 0, it is a bullish signal, and when crossing below 0, it is a bearish signal
|
|
7. Establish long and short strategies based on dVFI patterns
|
|
|
|
## Advantage Analysis
|
|
|
|
1. The strategy fully considers the impact of trading volume changes on trend judgment, using momentum indicators to measure trend strength and more accurately capture trend turning points.
|
|
|
|
2. The strategy incorporates trading volume threshold calculation to filter normal fluctuations and only capture collective behavior of large funds, avoiding being misled by market noise.
|
|
|
|
3. The combined consideration of price and volume can effectively avoid false breakouts.
|
|
|
|
4. The use of moving averages and logical criteria filters out most false signals.
|
|
|
|
5. Following trends rather than predicting reversals is well suited for medium-to-long term trend trading and capturing the market's main direction.
|
|
|
|
## Risk Analysis
|
|
|
|
1. The strategy relies mainly on trading volume changes to determine trends, and its effectiveness may be compromised in products with inactive trading volume.
|
|
|
|
2. Trading volume data can be manipulated, potentially generating misleading signals, so price-volume divergences need to be watched out for.
|
|
|
|
3. Price-volume relationships are often lagging, potentially missing the optimal entry timing at the beginning of trends.
|
|
|
|
4. Crude stop loss methods may prematurely exit trades, unable to persistently capture trends.
|
|
|
|
5. Unable to respond effectively to short-term corrections, and may be insensitive to sudden events.
|
|
|
|
Consider incorporating moving averages, volatility indicators to optimize entries and stops; analyzing price-volume with more data sources to avoid misleading signals; incorporating appropriate technical indicators to improve responsiveness to short-term corrections.
|
|
|
|
## Optimization Directions
|
|
|
|
1. Optimize entry conditions by incorporating moving averages, ichimoku kinko hyo etc to confirm entries after trend starts.
|
|
|
|
2. Optimize stops with trailing stops, staged stops etc to make stops adhere closely to price and track trend stops.
|
|
|
|
3. Add trend metrics like ADX to avoid incorrect trades in range-bound and choppy markets.
|
|
|
|
4. Optimize parameters through longer backtests to find optimal parameter combinations.
|
|
|
|
5. Expand strategy to more products, searching for higher quality instruments with active volume.
|
|
|
|
6. Consider adding machine learning models to leverage more data for price-volume analysis and improve signal quality.
|
|
|
|
## Conclusion
|
|
|
|
The overall strategy logic is clear, with intuitive core indicators reliably identifying trend direction. The advantage lies in emphasizing trading volume changes, suitable for tracking medium-to-long term trends, but misleading signals need to be watched out for. Further improvements in parameters, stop losses, indicator combinations can enhance live performance.
|
|
|
|
[/trans]
|
|
|
|
|
|
|
|
> Source (PineScript)
|
|
|
|
``` pinescript
|
|
/*backtest
|
|
start: 2022-11-08 00:00:00
|
|
end: 2023-11-14 00:00:00
|
|
period: 1d
|
|
basePeriod: 1h
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
|
*/
|
|
|
|
//@version=4
|
|
strategy("Strategy for Volume Flow Indicator with alerts and markers on the chart", overlay=true)
|
|
// This indicator has been copied form Lazy Bear's code
|
|
lengthVFI = 130
|
|
coefVFI = 0.2
|
|
vcoefVFI = 2.5
|
|
signalLength= 5
|
|
smoothVFI=true
|
|
|
|
ma(x,y) => smoothVFI ? sma(x,y) : x
|
|
|
|
typical=hlc3
|
|
inter = log( typical ) - log( typical[1] )
|
|
vinter = stdev(inter, 30 )
|
|
cutoff = coefVFI * vinter * close
|
|
vave = sma( volume, lengthVFI )[1]
|
|
vmax = vave * vcoefVFI
|
|
vc = iff(volume < vmax, volume, vmax)
|
|
mf = typical - typical[1]
|
|
vcp = iff( mf > cutoff, vc, iff ( mf < -cutoff, -vc, 0 ) )
|
|
|
|
vfi = ma(sum( vcp , lengthVFI )/vave, 3)
|
|
vfima=ema( vfi, signalLength )
|
|
dVFI=vfi-vfima
|
|
|
|
bullishVFI = dVFI > 0 and dVFI[1] <=0
|
|
bearishVFI = dVFI < 0 and dVFI[1] >=0
|
|
|
|
longCondition = dVFI > 0 and dVFI[1] <=0
|
|
shortCondition = dVFI < 0 and dVFI[1] >=0
|
|
|
|
plotshape(bullishVFI, color=color.green, style=shape.labelup, textcolor=#000000, text="VFI", location=location.belowbar, transp=0)
|
|
plotshape(bearishVFI, color=color.red, style=shape.labeldown, textcolor=#ffffff, text="VFI", location=location.abovebar, transp=0)
|
|
|
|
alertcondition(bullishVFI, title='Bullish - Volume Flow Indicator', message='Bullish - Volume Flow Indicator')
|
|
alertcondition(bearishVFI, title='Bearish - Volume Flow Indicator', message='Bearish - Volume Flow Indicator')
|
|
|
|
if(year > 2018)
|
|
strategy.entry("Long", strategy.long, when=dVFI > 0 and dVFI[1] <=0)
|
|
|
|
if(shortCondition)
|
|
strategy.close(id="Long")
|
|
|
|
|
|
```
|
|
|
|
> Detail
|
|
|
|
https://www.fmz.com/strategy/432240
|
|
|
|
> Last Modified
|
|
|
|
2023-11-15 17:53:51
|