
406 lines
24 KiB
Markdown
406 lines
24 KiB
Markdown
|
|
> Name
|
|
|
|
均线突破布林带策略Moving-Average-Bollinger-Bands-Breakout-Strategy
|
|
|
|
> Author
|
|
|
|
ChaoZhang
|
|
|
|
> Strategy Description
|
|
|
|
|
|
[trans]
|
|
|
|
## 概述
|
|
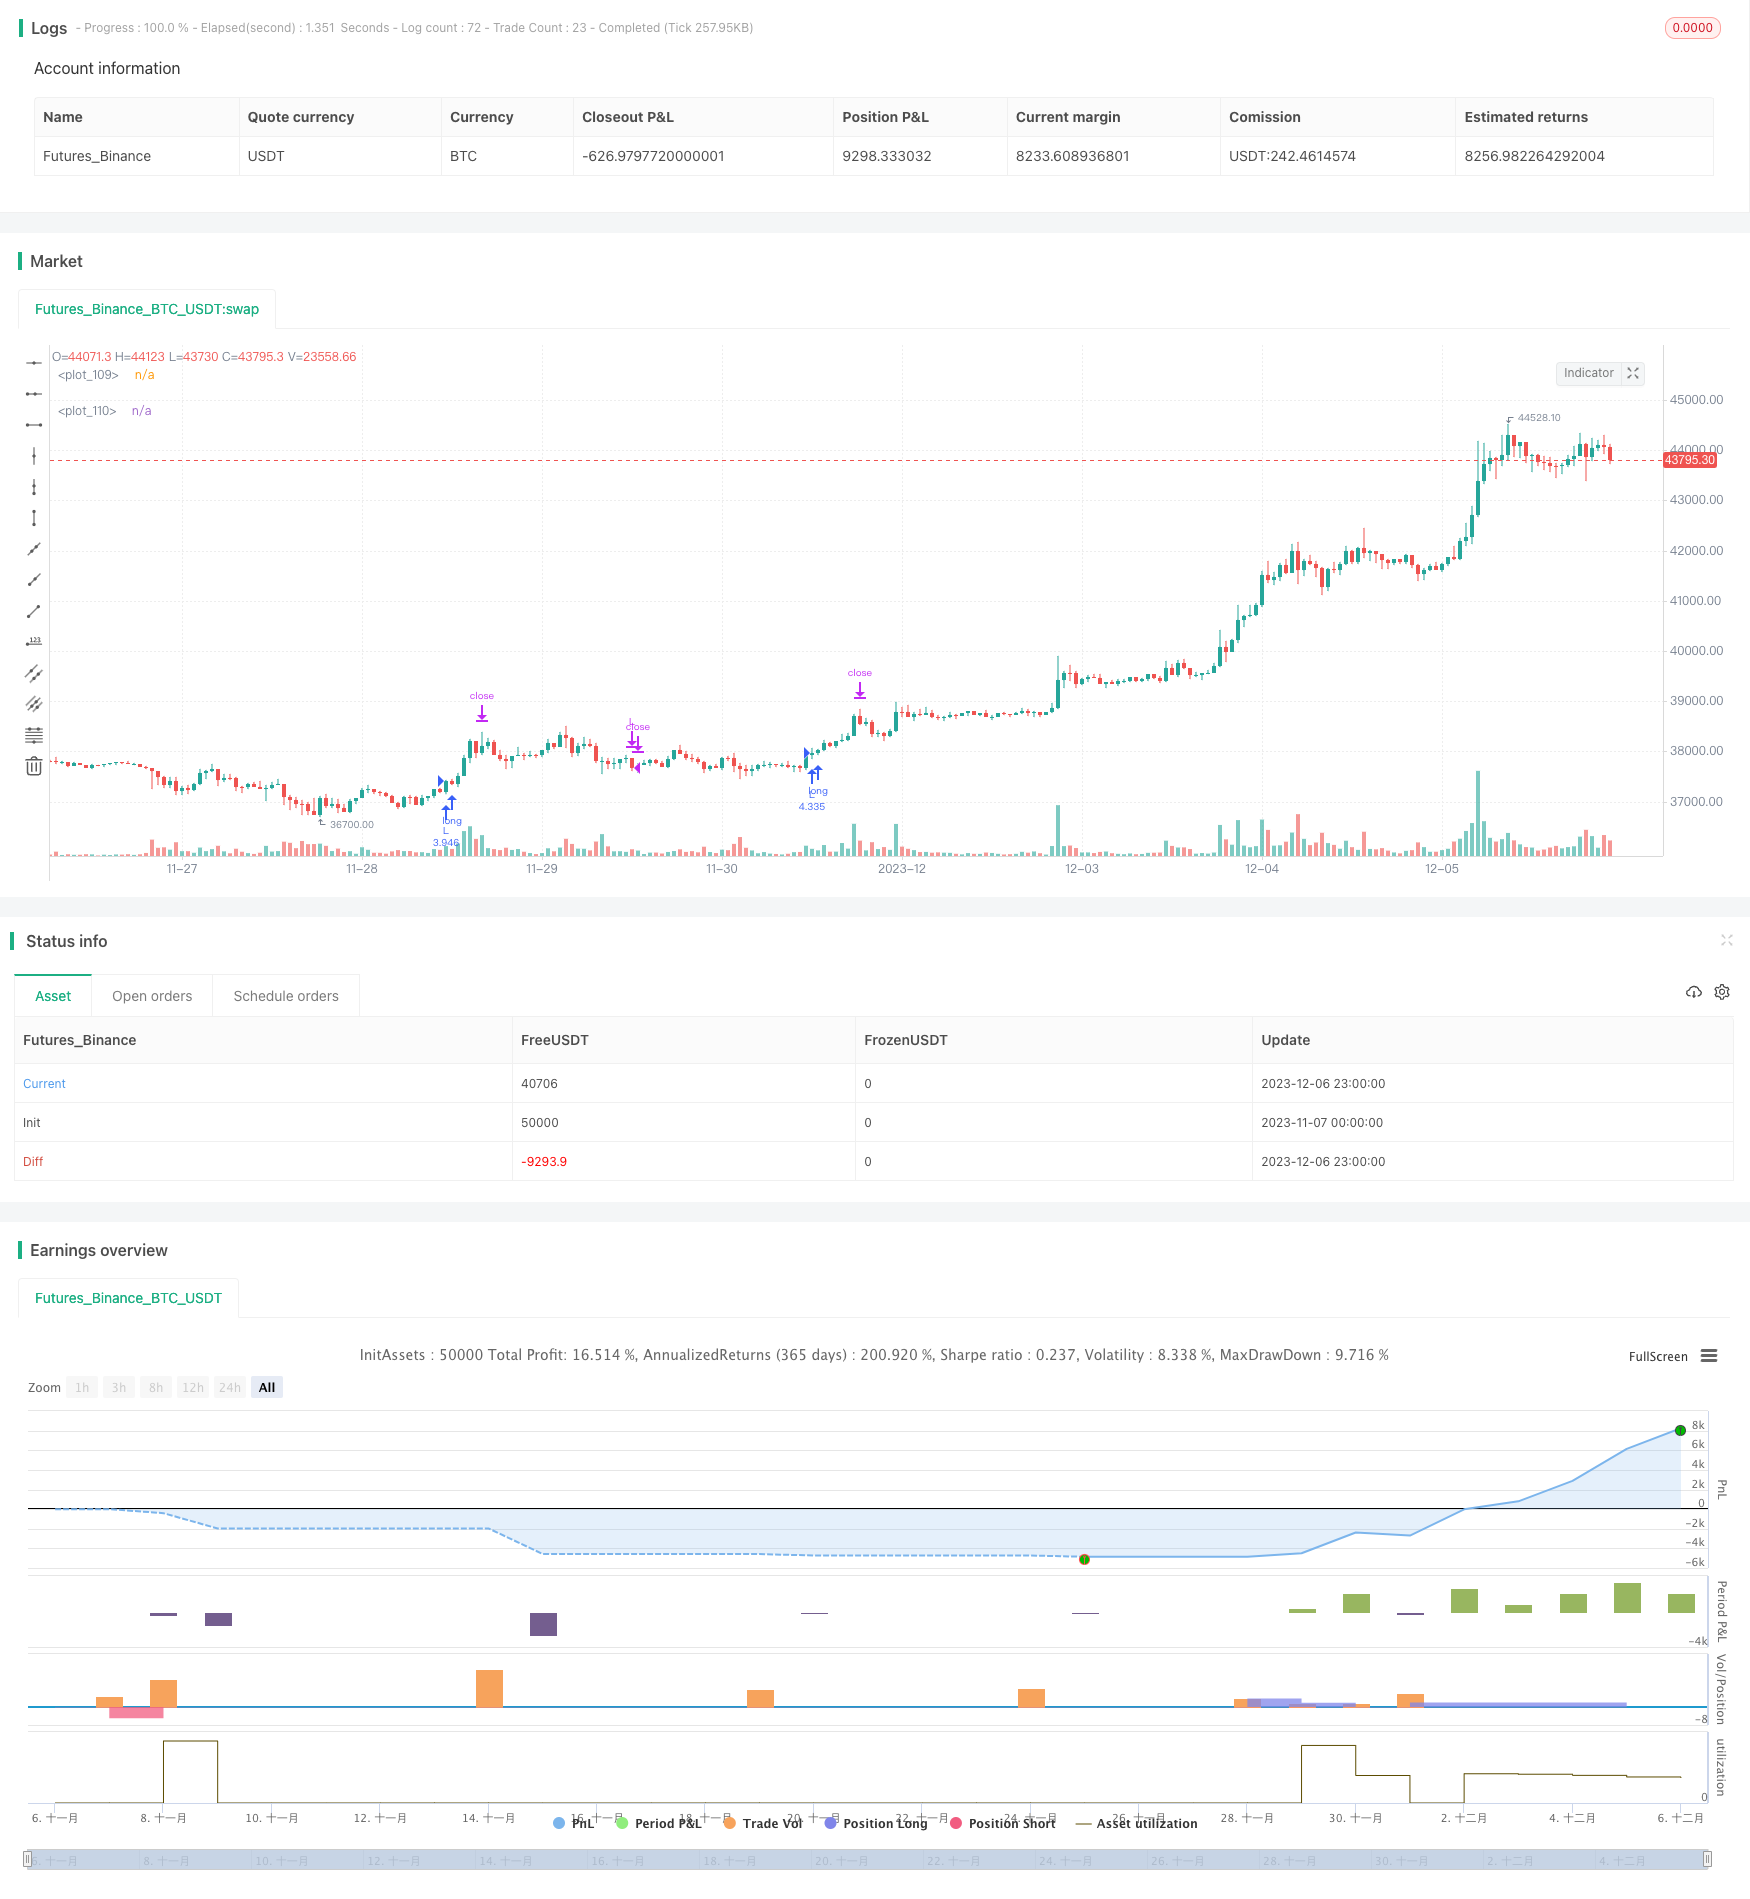
该策略结合了移动平均线指标、布林带指标和UT Bot Alerts指标,实现了一个简单的突破操作策略。当价格突破布林带上轨时,做多;当价格突破布林带下轨时,做空。
|
|
|
|
## 策略原理
|
|
1. 使用200周期的EMA作为判断趋势的中轴线。价格在EMA上方为看涨,价格在EMA下方为看跌。
|
|
2. UT Bot Alerts指标结合ATR,生成买卖信号。当价格和快速EMA交叉布林带上轨时产生做多信号;当价格和快速EMA交叉布林带下轨时产生做空信号。
|
|
3. ATR止损指标用于设置止损点。止损距离为ATR值的1.5倍。
|
|
4. 进场后通过风险回报比设置止损点、止盈点和止损移动到入场价。
|
|
|
|
## 优势分析
|
|
1. 使用布林带指标判断适合做多做空的时机,可以提高获利概率。
|
|
2. UT Bot Alerts指标可以产生比较准确的信号。
|
|
3. 采用风险回报比进行止损止盈,可以有效控制风险。
|
|
|
|
## 风险分析
|
|
1. 布林带在震荡市中容易产生错误信号。
|
|
2. ATR有滞后性,在趋势开始阶段止损距离可能过大。
|
|
3. 风险回报比设定不当也会导致过于激进或过于保守。
|
|
|
|
## 优化方向
|
|
1. 可以尝试使用别的指标代替UT Bot Alerts指标。
|
|
2. 可以对ATR的周期和倍数进行优化,使止损距离更合适。
|
|
3. 可以测试不同的风险回报比,找到最佳参数。
|
|
|
|
## 总结
|
|
该策略整合了多个指标的优点,具有较强的实用性。通过参数优化,可以成为一个稳定可靠的突破系统。但也需要注意防范指标失效和参数不当导致的风险。
|
|
|
|
|
|
||
|
|
|
|
## Overview
|
|
This strategy combines moving average, Bollinger bands and UT Bot Alerts indicators to implement a simple breakout trading strategy. It goes long when price breaks above Bollinger upper band and goes short when price breaks below Bollinger lower band.
|
|
|
|
## Strategy Logic
|
|
1. The 200-period EMA serves as the baseline for the trend. Price above EMA signifies uptrend and price below EMA signifies downtrend.
|
|
2. The UT Bot Alerts indicator generates buy and sell signals in combination with ATR. It triggers long signal when price and fast EMA cross above Bollinger upper band. And it triggers short signal when price and fast EMA cross below Bollinger lower band.
|
|
3. The ATR stop loss indicator sets the stop loss points. The stop loss distance is 1.5 times the ATR value.
|
|
4. After entry, stop loss, take profit and break even levels are determined by risk reward ratio.
|
|
|
|
## Advantage Analysis
|
|
1. Using Bollinger bands to identify appropriate long and short opportunities can improve profitability.
|
|
2. The UT Bot Alerts indicator can generate comparatively accurate signals.
|
|
3. By adopting risk reward ratio for stop loss and take profit, risk can be effectively controlled.
|
|
|
|
## Risk Analysis
|
|
1. Bollinger bands tend to produce false signals during ranging periods.
|
|
2. ATR has lagging effect. At the beginning of a trend, the stop loss distance may be too wide.
|
|
3. Improper risk reward ratio settings can also lead to over-aggressiveness or over-conservativeness.
|
|
|
|
## Optimization Guidelines
|
|
1. Try using other indicators to replace the UT Bot Alerts indicator.
|
|
2. Optimize the period and multiplier parameters of ATR to find more suitable stop loss distance.
|
|
3. Test different risk reward ratios to find the optimal parameters.
|
|
|
|
## Conclusion
|
|
This strategy integrates the strengths of multiple indicators and has considerable practicality. Through parameter optimization, it can become a steady and reliable breakout system. But the risks arising from indicator failure and improper parameters should also be watched out for.
|
|
[/trans]
|
|
|
|
> Strategy Arguments
|
|
|
|
|
|
|
|
|Argument|Default|Description|
|
|
|----|----|----|
|
|
|v_input_bool_1|false|Date background|
|
|
|v_input_bool_2|false|Session background|
|
|
|v_input_float_1|10000|(?Calculate position)Enter initial/current capital|
|
|
|v_input_bool_14|true|Use leverage ?|
|
|
|v_input_float_2|2.5|(?Position amount calculator)% account risk per trade|
|
|
|v_input_1|timestamp(10 Feb 2014 13:30 +0000)|(?Time filter)Initial date|
|
|
|v_input_2|timestamp(01 Jan 2030 19:30 +0000)|Final date|
|
|
|v_input_3|0000-2400|Time session|
|
|
|v_input_int_1|200|(?Trend)Ema length|
|
|
|v_input_bool_3|false|(?Appearance)Show ema ?|
|
|
|v_input_bool_4|false|Show atr from ut bot alerts ?|
|
|
|v_input_bool_5|false|Show ema from ut bot alerts ?|
|
|
|v_input_bool_6|true|Show signals ?|
|
|
|v_input_bool_7|false|Paint candles ?|
|
|
|v_input_bool_8|true|Show Atr stop loss ?|
|
|
|v_input_bool_12|true|Draw position on chart ?|
|
|
|v_input_bool_13|true|Draw first take profit/breakeven price on chart ?|
|
|
|v_input_4|3|(?UT BOT ALERTS)Key Vaule|
|
|
|v_input_5|true|ATR Period|
|
|
|v_input_6|false|Signals from Heikin Ashi Candles|
|
|
|v_input_7_close|0|(?Atr stop loss)Source: close|high|low|open|hl2|hlc3|hlcc4|ohlc4|
|
|
|v_input_int_2|14|Period|
|
|
|v_input_float_3|1.5|Atr multiplier|
|
|
|v_input_string_1|0|(?Risk management for trades)Source of stoploss: Current candle|Past candle|
|
|
|v_input_float_4|2.5|% Account risk per trade for backtesting|
|
|
|v_input_bool_9|true|Use leverage for backtesting ?|
|
|
|v_input_float_5|0.75|Risk/reward for breakeven long|
|
|
|v_input_float_6|3|Risk/reward for take profit long|
|
|
|v_input_float_7|0.75|Risk/reward for break even short|
|
|
|v_input_float_8|3|Risk/reward for take profit short|
|
|
|v_input_float_9|50|% of trade for first take profit|
|
|
|v_input_bool_10|true|(?Positions management)Long positions ?|
|
|
|v_input_bool_11|true|Short positions ?|
|
|
|
|
|
|
> Source (PineScript)
|
|
|
|
``` pinescript
|
|
/*backtest
|
|
start: 2023-11-07 00:00:00
|
|
end: 2023-12-07 00:00:00
|
|
period: 1h
|
|
basePeriod: 15m
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
|
*/
|
|
|
|
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
|
|
//@version=5
|
|
//Developed by StrategiesForEveryone
|
|
|
|
strategy("UT Bot alerts strategy", overlay=true, process_orders_on_close = true, initial_capital = 1000000, default_qty_type=strategy.cash, precision = 2, calc_on_every_tick = true, commission_value = 0.03)
|
|
|
|
// ------ Inputs for calculating position --------
|
|
|
|
initial_actual_capital = input.float(defval=10000, title = "Enter initial/current capital", group = "Calculate position")
|
|
risk_c = input.float(2.5, '% account risk per trade', step=1, group = "Position amount calculator", tooltip = "Percentage of total account to risk per trade. The USD value that should be used to risk the inserted percentage of the account. Appears green in the upper left corner")
|
|
|
|
// ------ Date filter (obtained from ZenAndTheArtOfTrading) ---------
|
|
|
|
initial_date = input(title="Initial date", defval=timestamp("10 Feb 2014 13:30 +0000"), group="Time filter", tooltip="Enter the start date and time of the strategy")
|
|
final_date = input(title="Final date", defval=timestamp("01 Jan 2030 19:30 +0000"), group="Time filter", tooltip="Enter the end date and time of the strategy")
|
|
dateFilter(int st, int et) => time >= st and time <= et
|
|
colorDate = input.bool(defval=false, title="Date background", tooltip = "Add color to the period of time of the strategy tester")
|
|
bgcolor(colorDate and dateFilter(initial_date, final_date) ? color.new(color.blue, transp=90) : na)
|
|
|
|
// ------ Session limits (obtained from ZenAndTheArtOfTrading) -------
|
|
|
|
timeSession = input(title="Time session", defval="0000-2400", group="Time filter", tooltip="Session time to operate. It may be different depending on your time zone, you have to find the correct hours manually.")
|
|
colorBG = input.bool(title="Session background", defval=false, tooltip = "Add color to session time background")
|
|
inSession(sess) => na(time(timeframe.period, sess + ':1234567')) == false
|
|
bgcolor(inSession(timeSession) and colorBG ? color.rgb(0, 38, 255, 84) : na)
|
|
|
|
// ----------- Ema ----------------------
|
|
|
|
ema = input.int(200, title='Ema length', minval=1, maxval=500, group = "Trend")
|
|
ema200 = ta.ema(close, ema)
|
|
bullish = close > ema200
|
|
bearish = close < ema200
|
|
show_ema = input.bool(defval=false, title="Show ema ?", group = "Appearance")
|
|
// plot(show_ema ? ema200 : na, title = "Ema", color=color.white, linewidth=2, display = display.all - display.status_line - display.price_scale)
|
|
|
|
// -------------- UT BOT ALERTS INDICATOR by @QuantNomad -------------------------
|
|
|
|
// Inputs
|
|
a = input(3, title='Key Vaule', group = "UT BOT ALERTS", tooltip = "Higher amount, less trades. Changing this could be useful in some assets or time frames")
|
|
c = input(1, title='ATR Period', group = "UT BOT ALERTS", tooltip = "Higher amount, less trades. Changing this could be useful in some assets or time frames")
|
|
h = input(false, title='Signals from Heikin Ashi Candles', group = "UT BOT ALERTS")
|
|
|
|
xATR = ta.atr(c)
|
|
nLoss = a * xATR
|
|
|
|
src = h ? request.security(ticker.heikinashi(syminfo.tickerid), timeframe.period, close, lookahead=barmerge.lookahead_off) : close
|
|
|
|
xATRTrailingStop = 0.0
|
|
iff_1 = src > nz(xATRTrailingStop[1], 0) ? src - nLoss : src + nLoss
|
|
iff_2 = src < nz(xATRTrailingStop[1], 0) and src[1] < nz(xATRTrailingStop[1], 0) ? math.min(nz(xATRTrailingStop[1]), src + nLoss) : iff_1
|
|
xATRTrailingStop := src > nz(xATRTrailingStop[1], 0) and src[1] > nz(xATRTrailingStop[1], 0) ? math.max(nz(xATRTrailingStop[1]), src - nLoss) : iff_2
|
|
show_atr_ut = input.bool(defval=false, title="Show atr from ut bot alerts ?", group = "Appearance")
|
|
// plot(show_atr_ut ? xATRTrailingStop : na, color = color.orange, linewidth = 2, display = display.all - display.price_scale - display.status_line)
|
|
|
|
pos = 0
|
|
iff_3 = src[1] > nz(xATRTrailingStop[1], 0) and src < nz(xATRTrailingStop[1], 0) ? -1 : nz(pos[1], 0)
|
|
pos := src[1] < nz(xATRTrailingStop[1], 0) and src > nz(xATRTrailingStop[1], 0) ? 1 : iff_3
|
|
|
|
xcolor = pos == -1 ? color.red : pos == 1 ? color.green : color.blue
|
|
|
|
ema_ut = ta.ema(src, 1)
|
|
show_ema_ut = input.bool(defval=false, title="Show ema from ut bot alerts ?", group = "Appearance")
|
|
// plot(show_ema_ut ? ema_ut : na, color = color.white, linewidth = 2, display = display.all - display.price_scale - display.status_line)
|
|
above = ta.crossover(ema_ut, xATRTrailingStop)
|
|
below = ta.crossover(xATRTrailingStop, ema_ut)
|
|
|
|
buy = src > xATRTrailingStop and above
|
|
sell = src < xATRTrailingStop and below
|
|
close_buy = src < xATRTrailingStop and below
|
|
close_sell = src > xATRTrailingStop and above
|
|
|
|
barbuy = src > xATRTrailingStop
|
|
barsell = src < xATRTrailingStop
|
|
|
|
show_signals = input.bool(true, title = "Show signals ?", group = "Appearance")
|
|
paint_candles = input.bool(false, title = "Paint candles ?", group = "Appearance")
|
|
|
|
// plotshape(bullish and show_signals ? buy : na, title='Buy', text='Buy', style=shape.labelup, location=location.belowbar, color=color.new(color.green, 0), textcolor=color.new(color.white, 0), size=size.tiny , display = display.all - display.price_scale - display.status_line)
|
|
// plotshape(bearish and show_signals ? sell : na, title='Sell', text='Sell', style=shape.labeldown, location=location.abovebar, color=color.new(color.red, 0), textcolor=color.new(color.white, 0), size=size.tiny, display = display.all - display.price_scale - display.status_line)
|
|
// plotshape(bullish and show_signals ? close_buy : na, title='Close Buy', text='Cl Buy', style=shape.labelup, location=location.belowbar, color=color.new(color.green, 80), textcolor=color.new(color.white, 0), size=size.tiny, display = display.all - display.price_scale - display.status_line)
|
|
// plotshape(bearish and show_signals ? close_sell : na, title='Close Sell', text='Cl Sell', style=shape.labeldown, location=location.abovebar, color=color.new(color.red, 80), textcolor=color.new(color.white, 0), size=size.tiny, display = display.all - display.price_scale - display.status_line)
|
|
|
|
barcolor(barbuy and paint_candles ? color.green : na)
|
|
barcolor(barsell and paint_candles ? color.red : na)
|
|
|
|
// -------------- Atr stop loss by garethyeo (modified) -----------------
|
|
|
|
long_condition_atr = src > xATRTrailingStop and above
|
|
short_condition_atr = src < xATRTrailingStop and below
|
|
source_atr = input(close, title='Source', group = "Atr stop loss", inline = "A")
|
|
length_atr = input.int(14, minval=1, title='Period', group = "Atr stop loss" , inline = "A")
|
|
multiplier = input.float(1.5, minval=0.1, step=0.1, title='Atr multiplier', group = "Atr stop loss", inline = "A", tooltip = "Defines the stop loss distance based on the Atr stop loss indicator")
|
|
show_atr = input.bool(defval = true, title = "Show Atr stop loss ?", group = "Appearance")
|
|
var float shortStopLoss = na
|
|
var float longStopLoss = na
|
|
var float atr_past_candle_long = na
|
|
var float atr_past_candle_short = na
|
|
//shortStopLoss = source_atr + ta.atr(length_atr) * multiplier
|
|
//longStopLoss = source_atr - ta.atr(length_atr) * multiplier
|
|
//atr_past_candle_short = close[1] + ta.atr(length_atr)[1] * multiplier[1]
|
|
//atr_past_candle_long = close[1] - ta.atr(length_atr)[1] * multiplier[1]
|
|
candle_of_stoploss = input.string(defval = "Current candle", title = "Source of stoploss", group = "Risk management for trades", options = ["Current candle","Past candle"])
|
|
if candle_of_stoploss == "Current candle"
|
|
shortStopLoss := source_atr + ta.atr(length_atr) * multiplier
|
|
longStopLoss := source_atr - ta.atr(length_atr) * multiplier
|
|
if candle_of_stoploss == "Past candle"
|
|
shortStopLoss := close[1] + ta.atr(length_atr)[1] * multiplier[1]
|
|
longStopLoss := close[1] - ta.atr(length_atr)[1] * multiplier[1]
|
|
plot(show_atr and long_condition_atr and bullish ? longStopLoss : na, color = color.white, style = plot.style_circles, linewidth = 2)
|
|
plot(show_atr and short_condition_atr and bearish ? shortStopLoss : na, color = color.white, style = plot.style_circles, linewidth = 2)
|
|
|
|
// ------------- Money management --------------
|
|
|
|
strategy_contracts = strategy.equity / close
|
|
distance_sl_atr_long = -1 * (longStopLoss - close) / close
|
|
distance_sl_atr_short = (shortStopLoss - close) / close
|
|
risk = input.float(2.5, '% Account risk per trade for backtesting', step=1, group = "Risk management for trades", tooltip = "Percentage of total account to risk per trade")
|
|
long_amount = strategy_contracts * (risk / 100) / distance_sl_atr_long
|
|
short_amount = strategy_contracts * (risk / 100) / distance_sl_atr_short
|
|
|
|
// ---- Fixed amounts ----
|
|
|
|
//fixed_amounts = input.bool(defval = false, title = "Fixed amounts ?", group = "Risk management for trades")
|
|
//fixed_amount_input = input.float(defval = 1000, title = "Fixed amount in usd", group = "Risk management for trades")
|
|
//if fixed_amounts
|
|
// long_amount := fixed_amount_input / close
|
|
//if fixed_amounts
|
|
// short_amount := fixed_amount_input / close
|
|
//
|
|
leverage=input.bool(defval=true, title="Use leverage for backtesting ?", group = "Risk management for trades", tooltip = "If it is activated, there will be no monetary units or amount of assets limit for each operation (That is, each operation will not be affected by the initial / current capital since it would be using leverage). If it is deactivated, the monetary units or the amount of assets to use for each operation will be limited by the initial/current capital.")
|
|
if not leverage and long_amount>strategy_contracts
|
|
long_amount:=strategy.equity/close
|
|
|
|
if not leverage and short_amount>strategy_contracts
|
|
short_amount:=strategy.equity/close
|
|
|
|
// ---------- Risk management ---------------
|
|
|
|
risk_reward_breakeven_long= input.float(title="Risk/reward for breakeven long", defval=0.75, step=0.1, group = "Risk management for trades")
|
|
risk_reward_take_profit_long= input.float(title="Risk/reward for take profit long", defval=3.0, step=0.1, group = "Risk management for trades")
|
|
risk_reward_breakeven_short= input.float(title="Risk/reward for break even short", defval=0.75, step=0.1, group = "Risk management for trades")
|
|
risk_reward_take_profit_short= input.float(title="Risk/reward for take profit short", defval=3.0, step=0.1, group = "Risk management for trades")
|
|
tp_percent=input.float(title="% of trade for first take profit", defval=50, step=5, group = "Risk management for trades", tooltip = "Closing percentage of the current position when the first take profit is reached.")
|
|
|
|
// ------------ Trade conditions ---------------
|
|
|
|
bullish := close > ema200
|
|
bearish := close < ema200
|
|
bought = strategy.position_size > 0
|
|
sold = strategy.position_size < 0
|
|
buy := src > xATRTrailingStop and above
|
|
sell := src < xATRTrailingStop and below
|
|
var float sl_long = na
|
|
var float sl_short = na
|
|
var float be_long = na
|
|
var float be_short = na
|
|
var float tp_long = na
|
|
var float tp_short = na
|
|
if not bought
|
|
be_long:=na
|
|
sl_long:=na
|
|
tp_long:=na
|
|
if not sold
|
|
be_short:=na
|
|
sl_short:=na
|
|
tp_short:=na
|
|
long_positions = input.bool(defval = true, title = "Long positions ?", group = "Positions management")
|
|
short_positions = input.bool(defval = true, title = "Short positions ?", group = "Positions management")
|
|
|
|
// ---------- Strategy -----------
|
|
|
|
// Long position
|
|
|
|
if not bought and buy and long_positions and bullish and inSession(timeSession)
|
|
sl_long:=longStopLoss
|
|
long_stoploss_distance = close - longStopLoss
|
|
be_long := close + long_stoploss_distance * risk_reward_breakeven_long
|
|
tp_long:=close+(long_stoploss_distance*risk_reward_take_profit_long)
|
|
strategy.entry('L', strategy.long, long_amount, alert_message = "Long")
|
|
strategy.exit("Tp", "L", stop=sl_long, limit=tp_long, qty_percent=tp_percent)
|
|
strategy.exit('Exit', 'L', stop=sl_long)
|
|
if bought and high > be_long
|
|
sl_long := strategy.position_avg_price
|
|
strategy.exit("Tp", "L", stop=sl_long, limit=tp_long, qty_percent=tp_percent)
|
|
strategy.exit('Exit', 'L', stop=sl_long)
|
|
if bought and sell and strategy.openprofit>0
|
|
strategy.close("L", comment="CL")
|
|
|
|
// Short position
|
|
|
|
if not sold and sell and short_positions and bearish and inSession(timeSession)
|
|
sl_short:=shortStopLoss
|
|
short_stoploss_distance=shortStopLoss - close
|
|
be_short:=((short_stoploss_distance*risk_reward_breakeven_short)-close)*-1
|
|
tp_short:=((short_stoploss_distance*risk_reward_take_profit_short)-close)*-1
|
|
strategy.entry("S", strategy.short, short_amount, alert_message = "Short")
|
|
strategy.exit("Tp", "S", stop=sl_short, limit=tp_short, qty_percent=tp_percent)
|
|
strategy.exit("Exit", "S", stop=sl_short)
|
|
if sold and low < be_short
|
|
sl_short:=strategy.position_avg_price
|
|
strategy.exit("Tp", "S", stop=sl_short, limit=tp_short, qty_percent=tp_percent)
|
|
strategy.exit("Exit", "S", stop=sl_short)
|
|
if sold and buy and strategy.openprofit>0
|
|
strategy.close("S", comment="CS")
|
|
|
|
// ---------- Draw positions and signals on chart (strategy as an indicator) -------------
|
|
|
|
if high>tp_long
|
|
tp_long:=na
|
|
if low<tp_short
|
|
tp_short:=na
|
|
if high>be_long
|
|
be_long:=na
|
|
if low<be_short
|
|
be_short:=na
|
|
|
|
show_position_on_chart = input.bool(defval=true, title="Draw position on chart ?", group = "Appearance", tooltip = "Activate to graphically display profit, stop loss and break even")
|
|
// position_price = plot(show_position_on_chart? strategy.position_avg_price : na, style=plot.style_linebr, color = color.new(#ffffff, 10), linewidth = 1, display = display.all - display.status_line - display.price_scale)
|
|
|
|
// sl_long_price = plot(show_position_on_chart and bought ? sl_long : na, style = plot.style_linebr, color = color.new(color.red, 10), linewidth = 1, display = display.all - display.status_line - display.price_scale)
|
|
// sl_short_price = plot(show_position_on_chart and sold ? sl_short : na, style = plot.style_linebr, color = color.new(color.red, 10), linewidth = 1, display = display.all - display.status_line - display.price_scale)
|
|
|
|
// tp_long_price = plot(strategy.position_size>0 and show_position_on_chart? tp_long : na, style = plot.style_linebr, color = color.new(#4cd350, 10), linewidth = 1, display = display.all - display.status_line - display.price_scale)
|
|
// tp_short_price = plot(strategy.position_size<0 and show_position_on_chart? tp_short : na, style = plot.style_linebr, color = color.new(#4cd350, 10), linewidth = 1, display = display.all - display.status_line - display.price_scale)
|
|
|
|
// breakeven_long = plot(strategy.position_size>0 and high<be_long and show_position_on_chart ? be_long : na , style = plot.style_linebr, color = color.new(#1fc9fd, 60), linewidth = 1, display = display.all - display.status_line - display.price_scale)
|
|
// breakeven_short = plot(strategy.position_size<0 and low>be_short and show_position_on_chart ? be_short : na , style = plot.style_linebr, color = color.new(#1fc9fd, 60), linewidth = 1, display = display.all - display.status_line - display.price_scale)
|
|
|
|
show_break_even_on_chart = input.bool(defval=true, title="Draw first take profit/breakeven price on chart ?", group = "Appearance", tooltip = "Activate to display take profit and breakeven price. It appears as a green point in the chart")
|
|
long_stoploss_distance = close - longStopLoss
|
|
short_stoploss_distance=shortStopLoss - close
|
|
be_long_plot = close + long_stoploss_distance * risk_reward_breakeven_long
|
|
be_short_plot =((short_stoploss_distance*risk_reward_breakeven_short)-close)*-1
|
|
// plot(show_break_even_on_chart and buy and bullish? be_long_plot : na, color=color.new(#1fc9fd, 10), style = plot.style_circles, linewidth = 2, display = display.all - display.price_scale)
|
|
// plot(show_break_even_on_chart and sell and bearish? be_short_plot : na, color=color.new(#1fc9fd, 10), style = plot.style_circles, linewidth = 2, display = display.all - display.price_scale)
|
|
|
|
// position_profit_long = plot(bought and show_position_on_chart and strategy.openprofit>0 ? close : na, style = plot.style_linebr, color = color.new(#4cd350, 10), linewidth = 1, display = display.all - display.status_line - display.price_scale)
|
|
// position_profit_short = plot(sold and show_position_on_chart and strategy.openprofit>0 ? close : na, style = plot.style_linebr, color = color.new(#4cd350, 10), linewidth = 1, display = display.all - display.status_line - display.price_scale)
|
|
|
|
// fill(plot1 = position_price, plot2 = position_profit_long, color = color.new(#4cd350, 90))
|
|
// fill(plot1 = position_price, plot2 = position_profit_short, color = color.new(#4cd350, 90))
|
|
|
|
// fill(plot1 = position_price, plot2 = sl_long_price, color = color.new(color.red,90))
|
|
// fill(plot1 = position_price, plot2 = sl_short_price, color = color.new(color.red,90))
|
|
|
|
// fill(plot1 = position_price, plot2 = tp_long_price, color = color.new(color.green,90))
|
|
// fill(plot1 = position_price, plot2 = tp_short_price, color = color.new(color.green,90))
|
|
|
|
// --------------- Positions amount calculator -------------
|
|
|
|
contracts_amount_c = initial_actual_capital / close
|
|
distance_sl_long_c = -1 * (longStopLoss - close) / close
|
|
distance_sl_short_c = (shortStopLoss - close) / close
|
|
long_amount_c = close * (contracts_amount_c * (risk_c / 100) / distance_sl_long_c)
|
|
short_amount_c = close * (contracts_amount_c * (risk_c / 100) / distance_sl_short_c)
|
|
long_amount_lev = close * (contracts_amount_c * (risk_c / 100) / distance_sl_long_c)
|
|
short_amount_lev = close * (contracts_amount_c * (risk_c / 100) / distance_sl_short_c)
|
|
|
|
leverage_for_calculator=input.bool(defval=true, title="Use leverage ?", group = "Calculate position", tooltip = "If it is activated, there will be no monetary units or amount of assets limit for each operation (That is, each operation will not be affected by the initial / current capital since it would be using leverage). If it is deactivated, the monetary units or the amount of assets to use for each operation will be limited by the initial/current capital.")
|
|
|
|
if not leverage_for_calculator and long_amount_lev>initial_actual_capital
|
|
long_amount_lev:=initial_actual_capital
|
|
|
|
if not leverage_for_calculator and short_amount_lev>initial_actual_capital
|
|
short_amount_lev:=initial_actual_capital
|
|
|
|
// plot(buy and leverage_for_calculator ? long_amount_c : na, color = color.rgb(136, 255, 0), display = display.all - display.pane - display.price_scale)
|
|
// plot(sell and leverage_for_calculator ? short_amount_c : na, color = color.rgb(136, 255, 0), display = display.all - display.pane - display.price_scale)
|
|
// plot(buy and not leverage_for_calculator ? long_amount_lev : na, color = color.rgb(136, 255, 0), display = display.all - display.pane - display.price_scale)
|
|
// plot(sell and not leverage_for_calculator ? short_amount_lev : na, color = color.rgb(136, 255, 0), display = display.all - display.pane - display.price_scale)
|
|
|
|
|
|
```
|
|
|
|
> Detail
|
|
|
|
https://www.fmz.com/strategy/434686
|
|
|
|
> Last Modified
|
|
|
|
2023-12-08 12:11:15
|