
275 lines
9.5 KiB
Markdown
275 lines
9.5 KiB
Markdown
|
||
> Name
|
||
|
||
四重指标均线回转策略Four-Indicator-Momentum-Reversal-Strategy
|
||
|
||
> Author
|
||
|
||
ChaoZhang
|
||
|
||
> Strategy Description
|
||
|
||
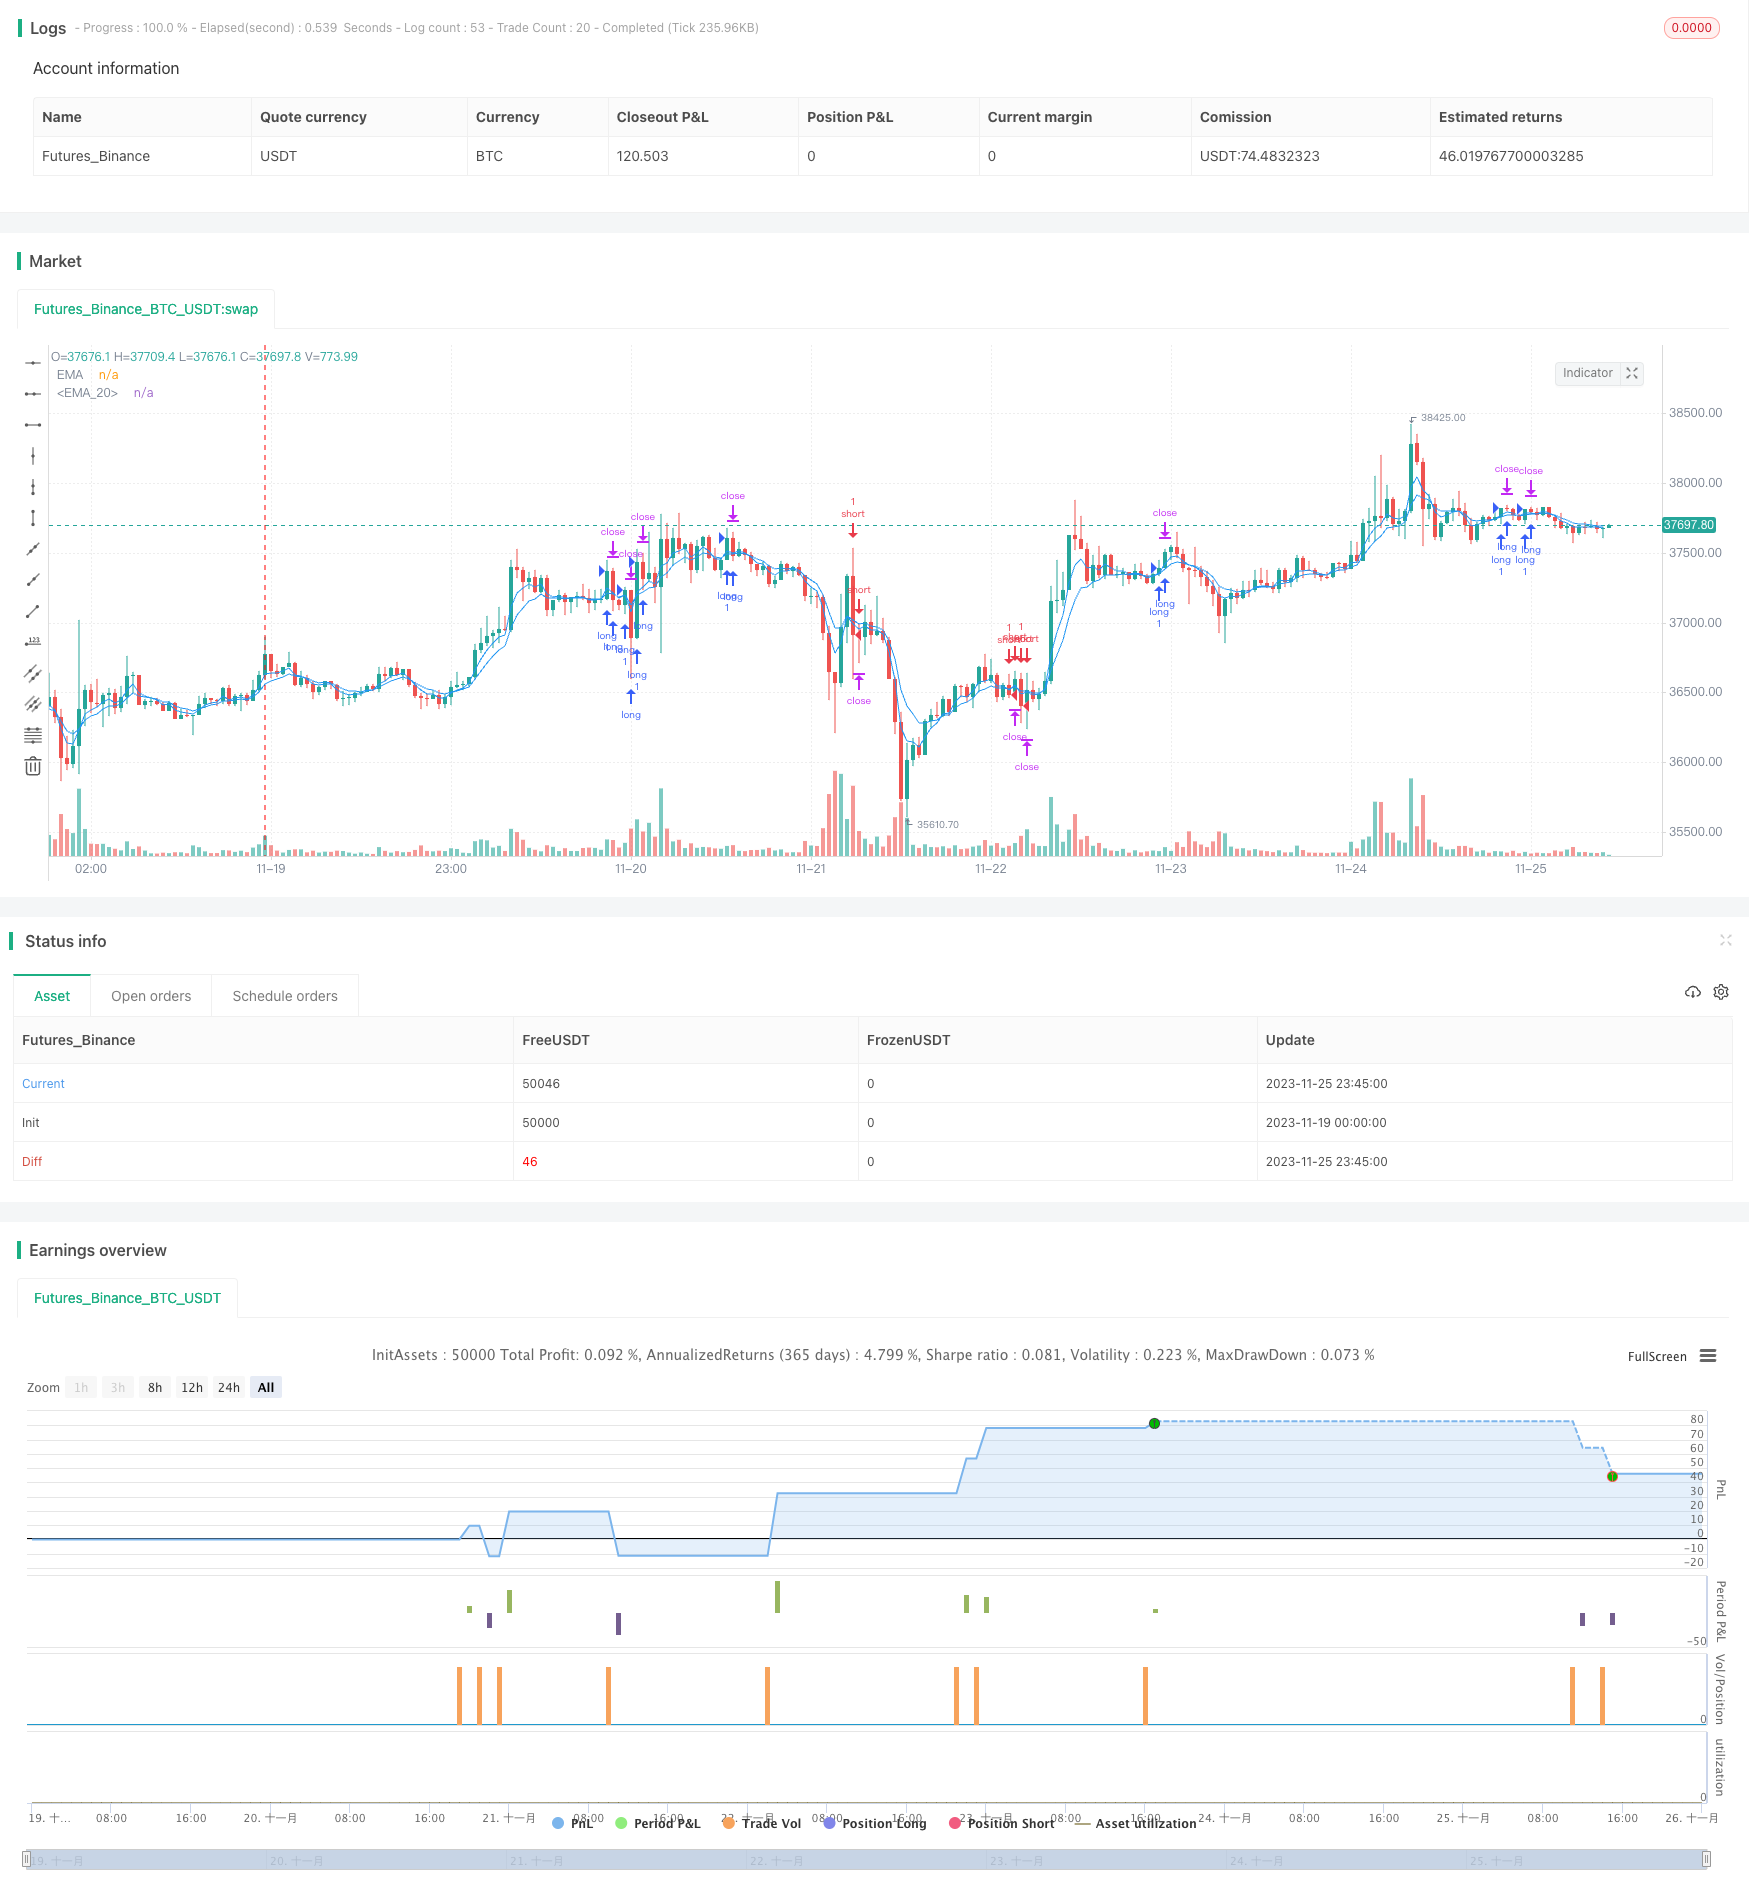
|
||
[trans]
|
||
|
||
## 概述
|
||
|
||
该策略利用了移动平均线EMA、相对强弱指标RSI、商品信道指标CCI三大主流指标结合,通过EMA均线是否回转识别价格趋势,然后使用过买过卖的RSI和CCI指标进行辅助判断,形成交易信号。属于中间期交易策略。
|
||
|
||
## 策略原理
|
||
|
||
1. 用4周期和8周期的EMA均线交叉来判断价格趋势,4周期快速判断,8周期慢速确定;
|
||
|
||
2. EMA均线向上回转时,即4周期线上穿8周期线,再辅助判断RSI指标高于65(相对超买区)和CCI指标高于0(代表没有超买超卖),满足则产生做多信号;
|
||
|
||
3. EMA均线向下回转时,即4周期线下穿8周期线,再辅助判断RSI指标低于35(相对超卖区)和CCI指标低于0(代表没有超买超卖),满足则产生做空信号;
|
||
|
||
4. 形成信号后,根据输入的止损距离和止盈距离来设置止损和止盈价格。
|
||
|
||
总体来说,该策略综合考量了中短期价格趋势和短期指标超买超卖区间避让,比较稳定,同时止损止盈设置也会有效控制单次交易的最大损失。
|
||
|
||
## 优势分析
|
||
|
||
1. 多指标综合判断,避免误判概率较大的单一指标交易策略;
|
||
|
||
2. EMA均线判断主趋势,避免被短期波动误导判断;RSI和CCI指标避让超买超卖区,增加胜率;
|
||
|
||
3. 自动设置止损和止盈控制单笔交易风险,有效防止极端行情导致亏损扩大;
|
||
|
||
4. 该策略属于技术面交易策略,不受基本面影响,市场任何단位周期都可以使用,易于实盘。
|
||
|
||
## 风险分析
|
||
|
||
1. 突发重大利空/利好消息面前技术指标容易失效;
|
||
|
||
2. 股价剧烈波动时,止损可能被突破,应适当放宽止损幅度;
|
||
|
||
3. 该策略属于短线频繁交易策略,交易成本会对盈利造成一定影响,适合具有成本优势的高频策略。
|
||
|
||
## 优化方向
|
||
|
||
1. 增加机器学习算法,结合股票基本面情况自动调整参数;
|
||
|
||
2. 增加自适应止损机制,而不是固定的止损距离。
|
||
|
||
## 总结
|
||
|
||
该交易策略综合多个指标判断,在合理参数设置下,可以获得比较稳定的中短期交易盈利,属于易于实盘的技术面策略。但同时也应注意防范突发重大基本消息,适当放宽止损距离等风险防范措施,这也是未来可以进一步优化的方向。
|
||
||
|
||
|
||
|
||
## Overview
|
||
|
||
This strategy utilizes three mainstream technical indicators: the moving average EMA, the relative strength index RSI and the commodity channel index CCI to identify price momentum through EMA crossovers and further entries confirmed by oversold/overbought readings from RSI and CCI. This intermediate-term trading strategy aims to capture momentum reversals.
|
||
|
||
## Strategy Logic
|
||
|
||
1. Use crossovers between 4-period and 8-period EMA to determine price momentum – the faster 4-period EMA to swiftly react and the slower 8-period EMA to confirm;
|
||
|
||
2. When EMAs turn upward, i.e. the 4-period EMA crossing above the 8-period EMA, check that RSI (over 65) and CCI (above 0) are not overbought to give a long signal;
|
||
|
||
3. When EMAs turn downward, i.e. the 4-period EMA crossing below the 8-period EMA, check that RSI (below 35) and CCI (below 0) are oversold to give a short signal;
|
||
|
||
4. Set stop loss and take profit prices based on input distances once trade signals are triggered.
|
||
|
||
In summary, this strategy considers medium-term trend and short-term overbought/oversold levels to form relatively stable signals, while stop losses and take profits effectively limit loss per trade.
|
||
|
||
## Advantage Analysis
|
||
|
||
1. Multiple indicators mitigate false signals from individual oscillators;
|
||
|
||
2. EMAs determine the main trend while RSI and CCI avoid overheated areas to improve win rate;
|
||
|
||
3. Automatic stop loss and take profit setup constrains loss in extreme moves;
|
||
|
||
4. Purely technical nature makes this strategy easily implementable across any timeframe.
|
||
|
||
## Risk Analysis
|
||
|
||
1. Major fundamental news can override technical levels;
|
||
|
||
2. Stop loss may be taken out by huge volatility calls for wider stops;
|
||
|
||
3. Frequent trading drives higher transaction costs thus best left for high frequency algorithms.
|
||
|
||
## Enhancement Opportunities
|
||
|
||
1. Incorporate machine learning models to auto-adjust parameters based on fundamentals;
|
||
|
||
2. Build adaptive stops reacting to volatility rather than fixed distances.
|
||
|
||
## Conclusion
|
||
|
||
This multifaceted strategy can deliver consistent medium-term profits under optimized parameters, making it an accessible technical system. Still, allowance needs to be given to black swan events via expanded stops etc, presenting areas for ongoing refinements.
|
||
|
||
[/trans]
|
||
|
||
> Strategy Arguments
|
||
|
||
|
||
|
||
|Argument|Default|Description|
|
||
|----|----|----|
|
||
|v_input_1|4|Length_MA4|
|
||
|v_input_2_close|0|Source: close|high|low|open|hl2|hlc3|hlcc4|ohlc4|
|
||
|v_input_3|false|Offset|
|
||
|v_input_4|8|Length_MA8|
|
||
|v_input_5_close|0|Source: close|high|low|open|hl2|hlc3|hlcc4|ohlc4|
|
||
|v_input_6|false|Offset|
|
||
|v_input_7|14|Length|
|
||
|v_input_8|6|CCI Turbo Length|
|
||
|v_input_9|14|CCI 14 Length|
|
||
|v_input_10|12|a|
|
||
|v_input_11|15|b|
|
||
|v_input_12|120|tp|
|
||
|v_input_13|96|sl|
|
||
|
||
|
||
> Source (PineScript)
|
||
|
||
``` pinescript
|
||
/*backtest
|
||
start: 2023-11-19 00:00:00
|
||
end: 2023-11-26 00:00:00
|
||
period: 45m
|
||
basePeriod: 5m
|
||
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
||
*/
|
||
|
||
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
|
||
// © SoftKill21
|
||
|
||
//@version=4
|
||
|
||
|
||
strategy(title="Moving Average Exponential", shorttitle="EMA", overlay=true)
|
||
|
||
|
||
len4 = input(4, minval=1, title="Length_MA4")
|
||
src4 = input(close, title="Source")
|
||
offset4 = input(title="Offset", type=input.integer, defval=0, minval=-500, maxval=500)
|
||
out4 = ema(src4, len4)
|
||
plot(out4, title="EMA", color=color.blue, offset=offset4)
|
||
|
||
len8 = input(8, minval=1, title="Length_MA8")
|
||
src8 = input(close, title="Source")
|
||
offset8 = input(title="Offset", type=input.integer, defval=0, minval=-500, maxval=500)
|
||
out8 = ema(src8, len8)
|
||
plot(out8, title="EMA", color=color.blue, offset=offset8)
|
||
|
||
|
||
//rsioma
|
||
src = close, len = input(14, minval=1, title="Length")
|
||
up = rma(max(change(ema(src, len)), 0), len)
|
||
down = rma(-min(change(ema(src, len)), 0), len)
|
||
rsi = down == 0 ? 100 : up == 0 ? 0 : 100 - (100 / (1 + up / down))
|
||
//plot(rsi, color=color.blue)
|
||
//band1 = hline(80)
|
||
//band0 = hline(20)
|
||
//fill(band1, band0, color=color.purple, transp=90)
|
||
//hline(50, color=color.gray, linestyle=plot.style_line)
|
||
sig = ema(rsi, 21)
|
||
//plot(sig, color=color.purple)
|
||
|
||
//woodie
|
||
cciTurboLength = input(title="CCI Turbo Length", type=input.integer, defval=6, minval=3, maxval=14)
|
||
cci14Length = input(title="CCI 14 Length", type=input.integer, defval=14, minval=7, maxval=20)
|
||
|
||
source = close
|
||
|
||
cciTurbo = cci(source, cciTurboLength)
|
||
cci14 = cci(source, cci14Length)
|
||
|
||
last5IsDown = cci14[5] < 0 and cci14[4] < 0 and cci14[3] < 0 and cci14[2] < 0 and cci14[1] < 0
|
||
last5IsUp = cci14[5] > 0 and cci14[4] > 0 and cci14[3] > 0 and cci14[2] > 0 and cci14[1] > 0
|
||
histogramColor = last5IsUp ? color.green : last5IsDown ? color.red : cci14 < 0 ? color.green : color.red
|
||
|
||
|
||
// Exit Condition
|
||
// Exit Condition
|
||
a = input(12)*10
|
||
b = input(15)*10
|
||
c = a*syminfo.mintick
|
||
d = b*syminfo.mintick
|
||
|
||
|
||
longCondition = crossover(out4, out8) and (rsi >= 65 and cci14>=0)
|
||
shortCondition = crossunder(out4, out8) and (rsi <=35 and cci14<=0)
|
||
|
||
|
||
long_stop_level = float(na)
|
||
long_profit_level1 = float(na)
|
||
long_profit_level2 = float(na)
|
||
long_even_level = float(na)
|
||
|
||
short_stop_level = float(na)
|
||
short_profit_level1 = float(na)
|
||
short_profit_level2 = float(na)
|
||
short_even_level = float(na)
|
||
|
||
long_stop_level := longCondition ? close - c : long_stop_level [1]
|
||
long_profit_level1 := longCondition ? close + d : long_profit_level1 [1]
|
||
//long_profit_level2 := longCondition ? close + d : long_profit_level2 [1]
|
||
//long_even_level := longCondition ? close + 0 : long_even_level [1]
|
||
|
||
short_stop_level := shortCondition ? close + c : short_stop_level [1]
|
||
short_profit_level1 := shortCondition ? close - d : short_profit_level1 [1]
|
||
//short_profit_level2 := shortCondition ? close - d : short_profit_level2 [1]
|
||
//short_even_level := shortCondition ? close + 0 : short_even_level [1]
|
||
|
||
|
||
//ha
|
||
// === Input ===
|
||
//ma1_len = input(1, title="MA 01")
|
||
//ma2_len = input(40, title="MA 02")
|
||
|
||
// === MA 01 Filter ===
|
||
//o=ema(open,ma1_len)
|
||
//cc=ema(close,ma1_len)
|
||
//h=ema(high,ma1_len)
|
||
//l=ema(low,ma1_len)
|
||
|
||
// === HA calculator ===
|
||
//ha_t = heikinashi(syminfo.tickerid)
|
||
//ha_o = security(ha_t, timeframe.period, o)
|
||
//ha_c = security(ha_t, timeframe.period, cc)
|
||
//ha_h = security(ha_t, timeframe.period, h)
|
||
//ha_l = security(ha_t, timeframe.period, l)
|
||
|
||
// === MA 02 Filter ===
|
||
//o2=ema(ha_o, ma2_len)
|
||
//c2=ema(ha_c, ma2_len)
|
||
//h2=ema(ha_h, ma2_len)
|
||
//l2=ema(ha_l, ma2_len)
|
||
|
||
// === Color def ===
|
||
//ha_col=o2>c2 ? color.red : color.lime
|
||
|
||
// === PLOTITING===
|
||
//plotcandle(o2, h2, l2, c2, title="HA Smoothed", color=ha_col)
|
||
|
||
tp=input(120)
|
||
sl=input(96)
|
||
|
||
strategy.entry("long", strategy.long, when = longCondition)
|
||
//strategy.close("long", when = o2>c2 , comment="ha_long")
|
||
strategy.entry("short", strategy.short , when =shortCondition )
|
||
//strategy.close("short", when = o2<=c2 , comment = "ha_short" )
|
||
|
||
//strategy.close("long",when=long_profit_level1 or long_stop_level , comment="tp/sl")
|
||
//strategy.close("short",when=short_profit_level1 or short_stop_level , comment="tp/sl")
|
||
|
||
strategy.exit("x_long","long",profit = tp, loss = sl) //when = o2>c2)
|
||
strategy.exit("x_short","short",profit = tp, loss = sl) //when = o2<c2)
|
||
|
||
|
||
```
|
||
|
||
> Detail
|
||
|
||
https://www.fmz.com/strategy/433431
|
||
|
||
> Last Modified
|
||
|
||
2023-11-27 15:51:01
|