
273 lines
14 KiB
Markdown
273 lines
14 KiB
Markdown
|
|
> Name
|
|
|
|
双向网格K线追踪交易策略Grid-Trading-Strategy-Based-on-Real-time-K-line-Tracking
|
|
|
|
> Author
|
|
|
|
ChaoZhang
|
|
|
|
> Strategy Description
|
|
|
|
|
|
[trans]
|
|
### 概述
|
|
|
|
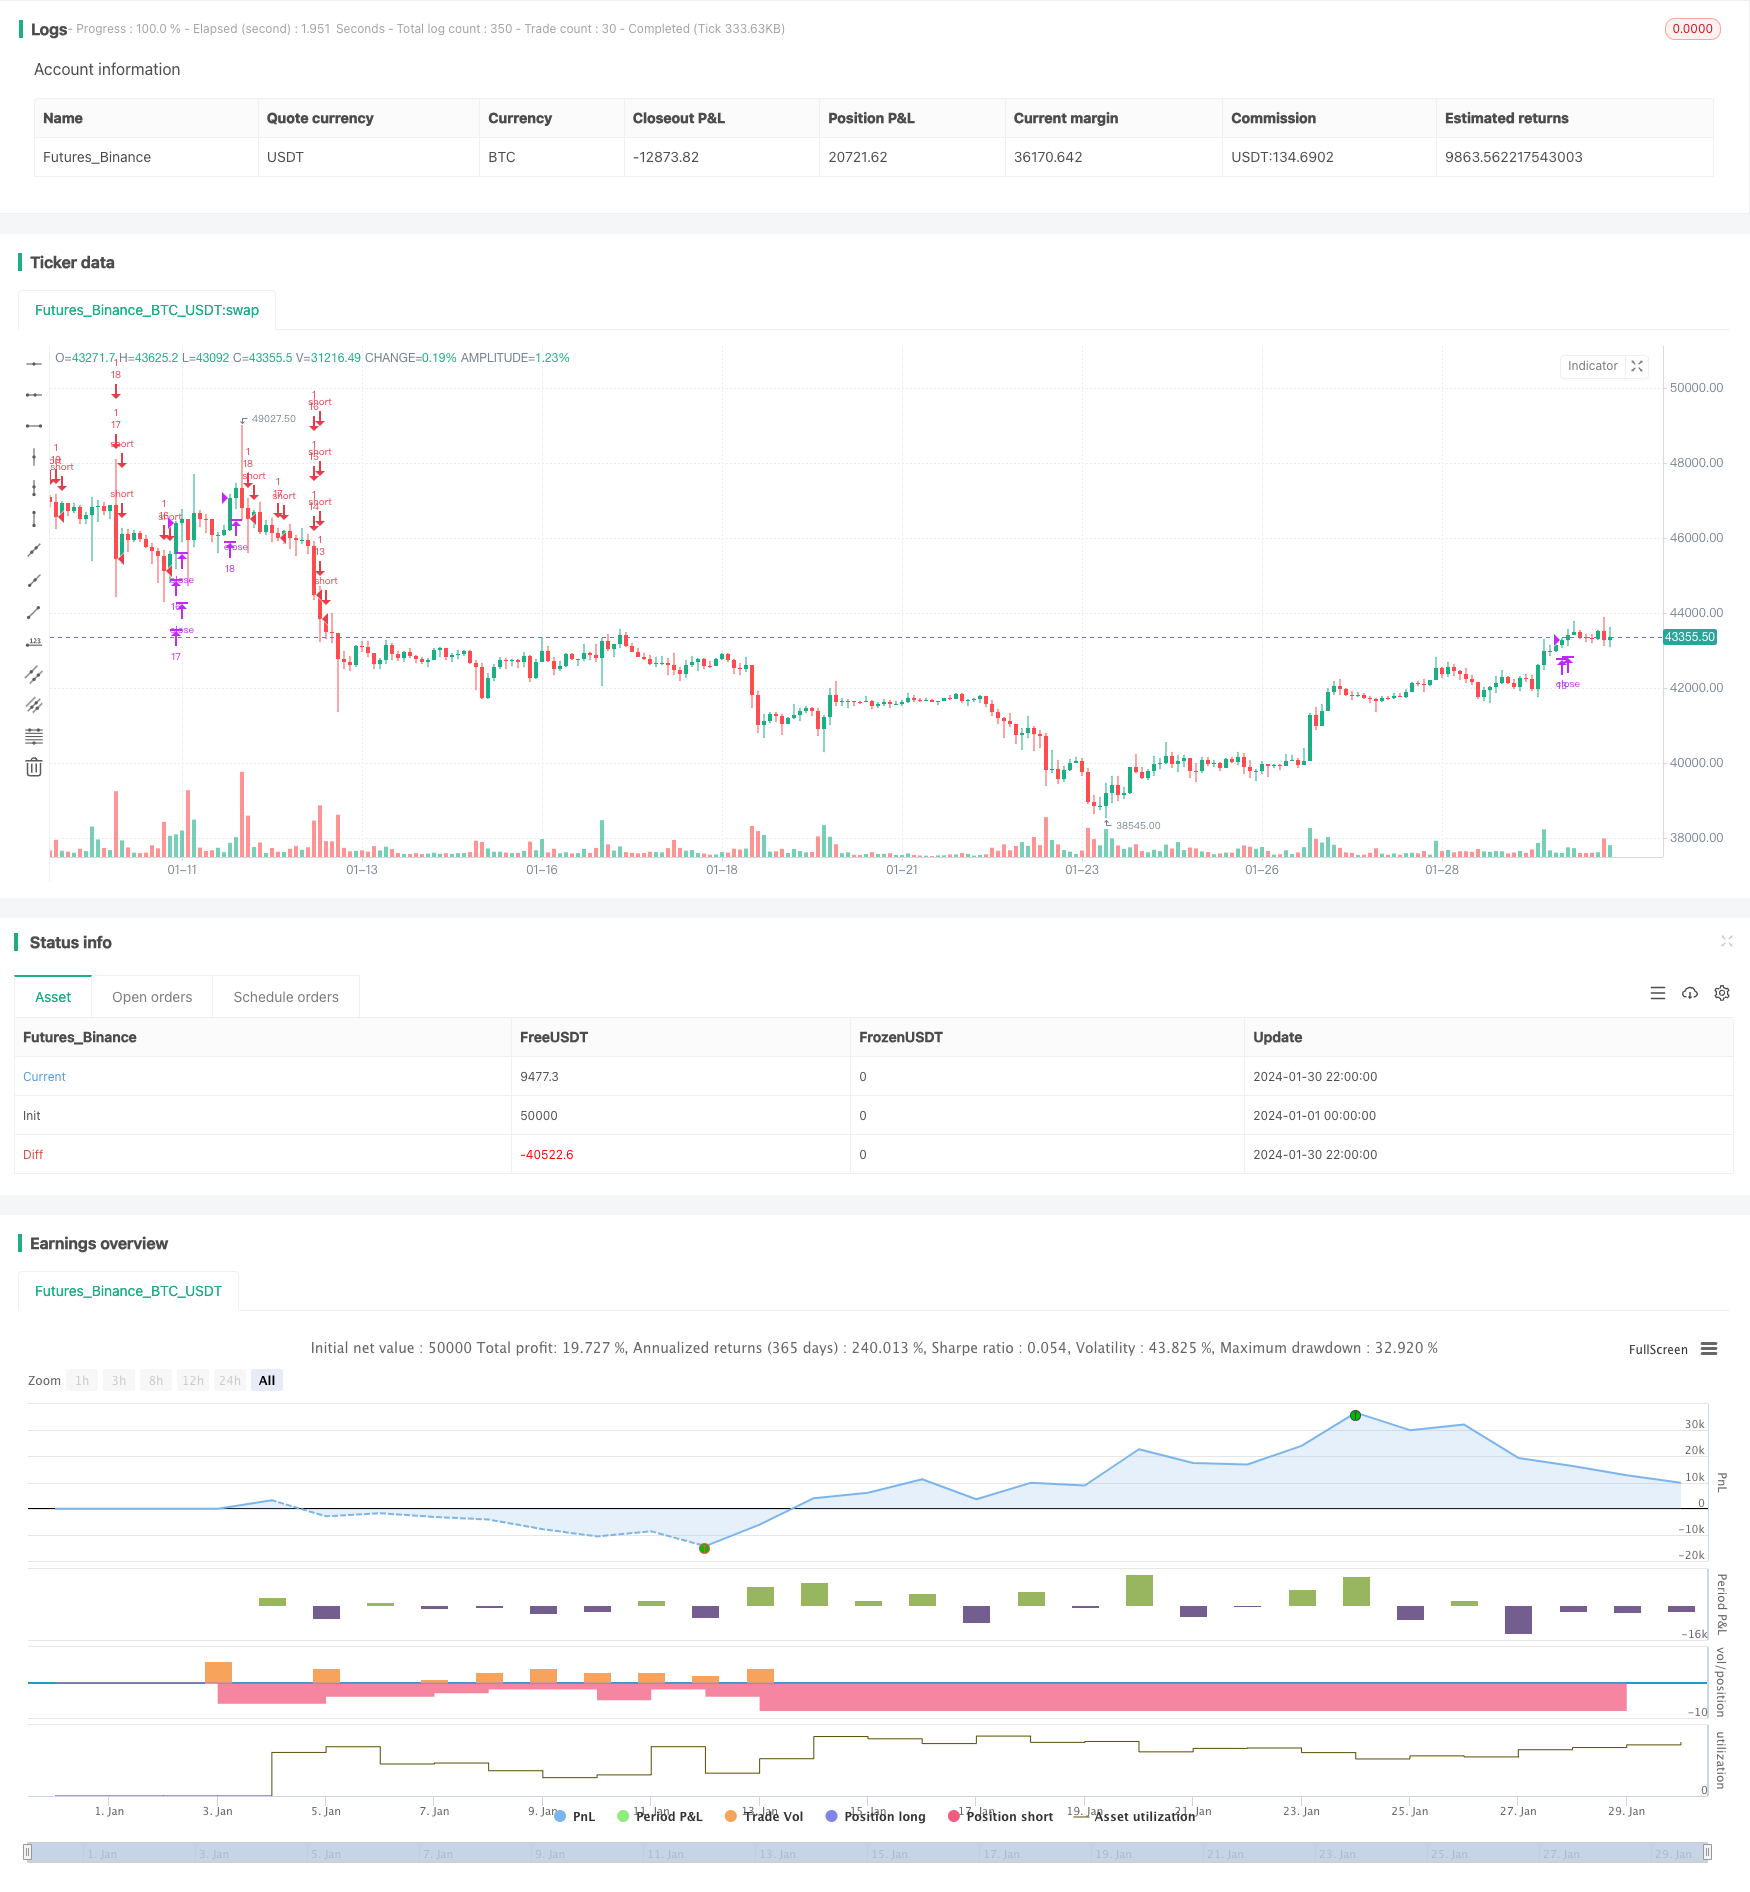
本策略是一个基于K线实时变化的双向追踪网格交易策略。它可以在牛市和熊市中都获得稳定的利润。
|
|
|
|
### 策略原理
|
|
|
|
1. 根据用户设置的网格数量,自动计算价格网格区间和每个网格价格。
|
|
|
|
2. 当价格突破网格价格时,按照固定数量开仓做多;当价格跌破网格价格时,平仓做多仓位,做空开仓。
|
|
|
|
3. 这样,价格在网格区间震荡时,可以通过追踪价格变化来获得利润。
|
|
|
|
### 优势分析
|
|
|
|
1. 自动计算合理的网格区间,无需人工确定支持阻力。
|
|
|
|
2. 双向交易,可适应行情多变的市场环境。
|
|
|
|
3. 固定开仓数量,有利于风险控制。
|
|
|
|
4. 代码直观简洁,容易理解和修改。
|
|
|
|
### 风险分析
|
|
|
|
1. 行情剧烈波动可能导致亏损扩大。
|
|
|
|
2. 交易费用的累积也会影响最终利润。
|
|
|
|
3. 需要合理确定网格数量,太多网格交易次数增多但每次利润有限。
|
|
|
|
### 优化方向
|
|
|
|
1. 加入止损策略,避免亏损扩大。
|
|
|
|
2. 增加网格数量动态调整功能。
|
|
|
|
3. 考虑加入杠杆,放大交易量。
|
|
|
|
### 总结
|
|
|
|
本策略整体思路清晰简洁,通过双向追踪网格交易获得稳定收益,同时也存在一定的交易风险。通过不断优化,可望获得更好的效果。
|
|
|
|
||
|
|
|
|
### Overview
|
|
|
|
This strategy is a bi-directional grid trading strategy based on real-time tracking of K-line changes. It can generate steady profits in both bull and bear markets.
|
|
|
|
### Strategy Logic
|
|
|
|
1. Automatically calculate the price range and each grid price based on the number of grids set by users.
|
|
|
|
2. When price breaks through a grid price, open long position with fixed quantity; when price falls below a grid price, close long position and open short position.
|
|
|
|
3. By tracking price changes, profits can be obtained when price fluctuates within the grid range.
|
|
|
|
### Advantage Analysis
|
|
|
|
1. Automatically calculate a reasonable grid range without needing to determine support and resistance manually.
|
|
|
|
2. Bi-directional trading adapts to changing market conditions.
|
|
|
|
3. Fixed open position size facilitates risk control.
|
|
|
|
4. Simple and straightforward code that is easy to understand and modify.
|
|
|
|
### Risk Analysis
|
|
|
|
1. Significant price swings may lead to expanding losses.
|
|
|
|
2. Accumulated trading fees also impact final profits.
|
|
|
|
3. Need to reasonably determine number of grids. More grids means more trades but each with limited profits.
|
|
|
|
### Optimization Directions
|
|
|
|
1. Incorporate stop loss strategy to limit losses.
|
|
|
|
2. Add dynamic adjustment of number of grids.
|
|
|
|
3. Consider adding leverage to amplify trading volume.
|
|
|
|
### Summary
|
|
|
|
The strategy has an overall clear and simple logic to generate steady income through bi-directional grid trading, but also bears certain trading risks. Further optimizations may lead to better results.
|
|
|
|
[/trans]
|
|
|
|
> Strategy Arguments
|
|
|
|
|
|
|
|
|Argument|Default|Description|
|
|
|----|----|----|
|
|
|v_input_1|true|(?Grid Bounds)Use Auto Bounds?|
|
|
|v_input_2|0|(Auto) Bound Source: Hi & Low|Average|
|
|
|v_input_3|250|(Auto) Bound Lookback|
|
|
|v_input_4|0.1|(Auto) Bound Deviation|
|
|
|v_input_5|0.285|(Manual) Upper Boundry(상단 가격)|
|
|
|v_input_6|0.225|(Manual) Lower Boundry(하단 가격)|
|
|
|v_input_7|30|(?Grid Lines)Grid Line Quantity(그리드 수)|
|
|
|v_input_8|100|(?Trading option)Initial balance(투자금액)|
|
|
|v_input_9|timestamp(15 March 2023 06:00)|Start Time|
|
|
|v_input_10|timestamp(31 Dec 2035 20:00)|End Time|
|
|
|
|
|
|
> Source (PineScript)
|
|
|
|
``` pinescript
|
|
/*backtest
|
|
start: 2024-01-01 00:00:00
|
|
end: 2024-01-31 00:00:00
|
|
period: 2h
|
|
basePeriod: 15m
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
|
*/
|
|
|
|
//@version=4
|
|
|
|
//hk4jerry
|
|
|
|
strategy("Grid Bot Backtesting", overlay=false, pyramiding=3000, close_entries_rule="ANY", default_qty_type=strategy.cash, initial_capital=100.0, currency="USD", commission_type=strategy.commission.percent, commission_value=0.025)
|
|
i_autoBounds = input(group="Grid Bounds", title="Use Auto Bounds?", defval=true, type=input.bool) // calculate upper and lower bound of the grid automatically? This will theorhetically be less profitable, but will certainly require less attention
|
|
i_boundSrc = input(group="Grid Bounds", title="(Auto) Bound Source", defval="Hi & Low", options=["Hi & Low", "Average"]) // should bounds of the auto grid be calculated from recent High & Low, or from a Simple Moving Average
|
|
i_boundLookback = input(group="Grid Bounds", title="(Auto) Bound Lookback", defval=250, type=input.integer, maxval=500, minval=0) // when calculating auto grid bounds, how far back should we look for a High & Low, or what should the length be of our sma
|
|
i_boundDev = input(group="Grid Bounds", title="(Auto) Bound Deviation", defval=0.10, type=input.float, maxval=1, minval=-1) // if sourcing auto bounds from High & Low, this percentage will (positive) widen or (negative) narrow the bound limits. If sourcing from Average, this is the deviation (up and down) from the sma, and CANNOT be negative.
|
|
i_upperBound = input(group="Grid Bounds", title="(Manual) Upper Boundry(상단 가격)", defval=0.285, type=input.float) // for manual grid bounds only. The upperbound price of your grid
|
|
i_lowerBound = input(group="Grid Bounds", title="(Manual) Lower Boundry(하단 가격)", defval=0.225, type=input.float) // for manual grid bounds only. The lowerbound price of your grid.
|
|
i_gridQty = input(group="Grid Lines", title="Grid Line Quantity(그리드 수)", defval=30, maxval=999, minval=1, type=input.integer) // how many grid lines are in your grid
|
|
initial_balance = input(group="Trading option", title="Initial balance(투자금액)", defval=100, step=0.01)
|
|
|
|
|
|
start_time = input(group="Trading option",defval=timestamp('15 March 2023 06:00'), title='Start Time', type = input.time)
|
|
end_time = input(group="Trading option",defval=timestamp('31 Dec 2035 20:00'), title='End Time', type = input.time)
|
|
isAfterStartDate = true
|
|
|
|
tradingtime= (timenow - start_time)/(86400000*30)
|
|
yeartime=tradingtime/12
|
|
|
|
|
|
f_getGridBounds(_bs, _bl, _bd, _up) =>
|
|
if _bs == "Hi & Low"
|
|
_up ? highest(close, _bl) * (1 + _bd) : lowest(close, _bl) * (1 - _bd)
|
|
else
|
|
avg = sma(close, _bl)
|
|
_up ? avg * (1 + _bd) : avg * (1 - _bd)
|
|
|
|
f_buildGrid(_lb, _gw, _gq) =>
|
|
gridArr = array.new_float(0)
|
|
for i=0 to _gq-1
|
|
array.push(gridArr, _lb+(_gw*i))
|
|
gridArr
|
|
|
|
f_getNearGridLines(_gridArr, _price) =>
|
|
arr = array.new_int(3)
|
|
for i = 0 to array.size(_gridArr)-1
|
|
if array.get(_gridArr, i) > _price
|
|
array.set(arr, 0, i == array.size(_gridArr)-1 ? i : i+1)
|
|
array.set(arr, 1, i == 0 ? i : i-1)
|
|
break
|
|
arr
|
|
|
|
var upperBound = i_autoBounds ? f_getGridBounds(i_boundSrc, i_boundLookback, i_boundDev, true) : i_upperBound // upperbound of our grid
|
|
var lowerBound = i_autoBounds ? f_getGridBounds(i_boundSrc, i_boundLookback, i_boundDev, false) : i_lowerBound // lowerbound of our grid
|
|
var gridWidth = (upperBound - lowerBound)/(i_gridQty-1) // space between lines in our grid
|
|
var gridLineArr = f_buildGrid(lowerBound, gridWidth, i_gridQty) // an array of prices that correspond to our grid lines
|
|
var orderArr = array.new_bool(i_gridQty, false) // a boolean array that indicates if there is an open order corresponding to each grid line
|
|
|
|
var closeLineArr = f_getNearGridLines(gridLineArr, close) // for plotting purposes - an array of 2 indices that correspond to grid lines near price
|
|
var nearTopGridLine = array.get(closeLineArr, 0) // for plotting purposes - the index (in our grid line array) of the closest grid line above current price
|
|
var nearBotGridLine = array.get(closeLineArr, 1) // for plotting purposes - the index (in our grid line array) of the closest grid line below current price
|
|
if isAfterStartDate
|
|
for i = 0 to (array.size(gridLineArr) - 1)
|
|
if close < array.get(gridLineArr, i) and not array.get(orderArr, i) and i < (array.size(gridLineArr) - 1)
|
|
buyId = i
|
|
array.set(orderArr, buyId, true)
|
|
strategy.entry(id=tostring(buyId), long=true, qty=(initial_balance/(i_gridQty-1))/close, comment="#"+tostring(buyId))
|
|
if close > array.get(gridLineArr, i) and i != 0
|
|
if array.get(orderArr, i-1)
|
|
sellId = i-1
|
|
array.set(orderArr, sellId, false)
|
|
strategy.close(id=tostring(sellId), comment="#"+tostring(sellId))
|
|
|
|
if i_autoBounds
|
|
upperBound := f_getGridBounds(i_boundSrc, i_boundLookback, i_boundDev, true)
|
|
lowerBound := f_getGridBounds(i_boundSrc, i_boundLookback, i_boundDev, false)
|
|
gridWidth := (upperBound - lowerBound)/(i_gridQty-1)
|
|
gridLineArr := f_buildGrid(lowerBound, gridWidth, i_gridQty)
|
|
|
|
closeLineArr := f_getNearGridLines(gridLineArr, close)
|
|
nearTopGridLine := array.get(closeLineArr, 0)
|
|
nearBotGridLine := array.get(closeLineArr, 1)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
var table table = table.new(position.top_right,6,8, frame_color = color.rgb(255, 255, 255),frame_width = 2,border_width = 2, border_color=color.rgb(255, 255, 255))
|
|
|
|
|
|
|
|
//제목
|
|
table.cell(table,0,0,"Upper limit price :", bgcolor=color.new(color.black,0),text_color =color.white)
|
|
table.cell(table,0,1,"Lower limit price :",bgcolor=color.new(color.black,0),text_color =color.white)
|
|
table.cell(table,0,2,"Grids quantity :",bgcolor=color.new(color.black,0),text_color =color.white)
|
|
table.cell(table,0,3,"Investment :",text_color =color.white,bgcolor=color.new(color.black,0))
|
|
table.cell(table,0,4,"USDT per grid :",text_color =color.white,bgcolor=color.new(color.black,0))
|
|
//수치
|
|
table.cell(table,1,0, tostring(upperBound, '###.#####')+ " USDT", bgcolor=color.new(#5a637e, 0),text_color =color.white)
|
|
table.cell(table,1,1, tostring(lowerBound, '###.#####')+ " USDT", bgcolor=color.new(#5a637e, 0),text_color =color.white)
|
|
table.cell(table,1,2, tostring(i_gridQty, '###'), bgcolor=color.new(#5a637e, 0),text_color =color.white)
|
|
table.cell(table,1,3, tostring(initial_balance,'###.##')+ " USDT", bgcolor=color.new(#5a637e, 0),text_color =color.white)
|
|
table.cell(table,1,4, tostring(initial_balance/i_gridQty,'###.##')+ " USDT", bgcolor=color.new(#5a637e, 0),text_color =color.white)
|
|
|
|
//제목
|
|
table.cell(table,2,0,"Current position :",text_color =color.white,bgcolor=color.new(color.black,0))
|
|
table.cell(table,2,1,"Position cost price :",text_color =color.white,bgcolor=color.new(color.black,0))
|
|
table.cell(table,2,2,"Unrealized profit :",bgcolor=color.new(color.black,0),text_color =color.white)
|
|
table.cell(table,2,3,"Unrealized profit % :",bgcolor=color.new(color.black,0),text_color =color.white)
|
|
table.cell(table,2,4,"Fee :",text_color =color.white,bgcolor=color.new(color.black,0))
|
|
|
|
//수치
|
|
table.cell(table,3,0, tostring(strategy.position_size) + syminfo.basecurrency + "\n" + tostring(strategy.position_size*strategy.position_avg_price/1, '###.##') + "USDT" ,text_color =color.white,bgcolor=color.new(#5a637e, 0))
|
|
table.cell(table,3,1, text=strategy.position_size>0 ? tostring(strategy.position_avg_price,'###.####')+ " USDT" : "NOT TRADING",text_color =color.white,bgcolor=color.new(#5a637e, 0))
|
|
table.cell(table,3,2, tostring(strategy.openprofit, '###.##')+ " USDT",text_color =color.white,bgcolor=strategy.openprofit > 0 ? color.teal : color.maroon)
|
|
table.cell(table,3,3, tostring(strategy.openprofit/initial_balance*100, '###.##')+ "%",text_color =color.white,bgcolor=strategy.openprofit > 0 ? color.teal : color.maroon)
|
|
table.cell(table,3,4, "-" + tostring(strategy.position_avg_price*strategy.position_size*0.025/100,'###.##')+ " USDT",text_color =color.white,bgcolor=color.new(#5a637e, 0))
|
|
|
|
//제목
|
|
table.cell(table,4,0,"Grid profit :",text_color =color.white,bgcolor=color.new(color.black,0))
|
|
table.cell(table,4,1,"Grid profit % :",text_color =color.white,bgcolor=color.new(color.black,0))
|
|
table.cell(table,4,2,"Net profit :", bgcolor=color.new(color.black,0),text_color =color.white)
|
|
table.cell(table,4,3,"Net profit % :",bgcolor=color.new(color.black,0),text_color =color.white)
|
|
table.cell(table,4,4,"Balance USDT :",bgcolor=color.new(color.black,0),text_color =color.white)
|
|
|
|
|
|
//수치
|
|
table.cell(table,5,0, tostring(strategy.netprofit, '###.#####')+ "USDT", text_color =color.white,bgcolor=strategy.netprofit > 0 ? color.teal : color.maroon)
|
|
table.cell(table,5,1, tostring((strategy.netprofit)/initial_balance*100/tradingtime, '####.##') + "%",text_color =color.white,bgcolor=strategy.netprofit > 0 ? color.teal : color.maroon)
|
|
table.cell(table,5,2, tostring(strategy.netprofit+strategy.openprofit, '###.##') + " USDT",text_color =color.white,bgcolor=strategy.netprofit+strategy.openprofit > 0 ? color.teal : color.maroon)
|
|
table.cell(table,5,3, tostring((strategy.netprofit+strategy.openprofit)/initial_balance*100, '####.##') + "%",text_color =color.white,bgcolor=strategy.netprofit+strategy.openprofit > 0 ? color.teal : color.maroon)
|
|
table.cell(table,5,4, tostring(initial_balance+strategy.netprofit+strategy.openprofit, '###.##')+ " USDT", text_color =color.white,bgcolor=color.new(#3d4d7c, 0))
|
|
|
|
|
|
|
|
|
|
|
|
// plot(strategy.initial_capital+ strategy.netprofit+strategy.openprofit, "Current Balance",color=color.rgb(81, 137, 128))
|
|
// plot(initial_balance, "Investment",color=color.rgb(81, 137, 128))
|
|
```
|
|
|
|
> Detail
|
|
|
|
https://www.fmz.com/strategy/440716
|
|
|
|
> Last Modified
|
|
|
|
2024-02-01 14:40:22
|