
155 lines
9.1 KiB
Markdown
155 lines
9.1 KiB
Markdown
|
|
> Name
|
|
|
|
动态仓位管理RSI超买反转策略-Dynamic-Position-Management-RSI-Overbought-Reversal-Strategy
|
|
|
|
> Author
|
|
|
|
ChaoZhang
|
|
|
|
> Strategy Description
|
|
|
|
|
|
|
|
[trans]
|
|
#### 概述
|
|
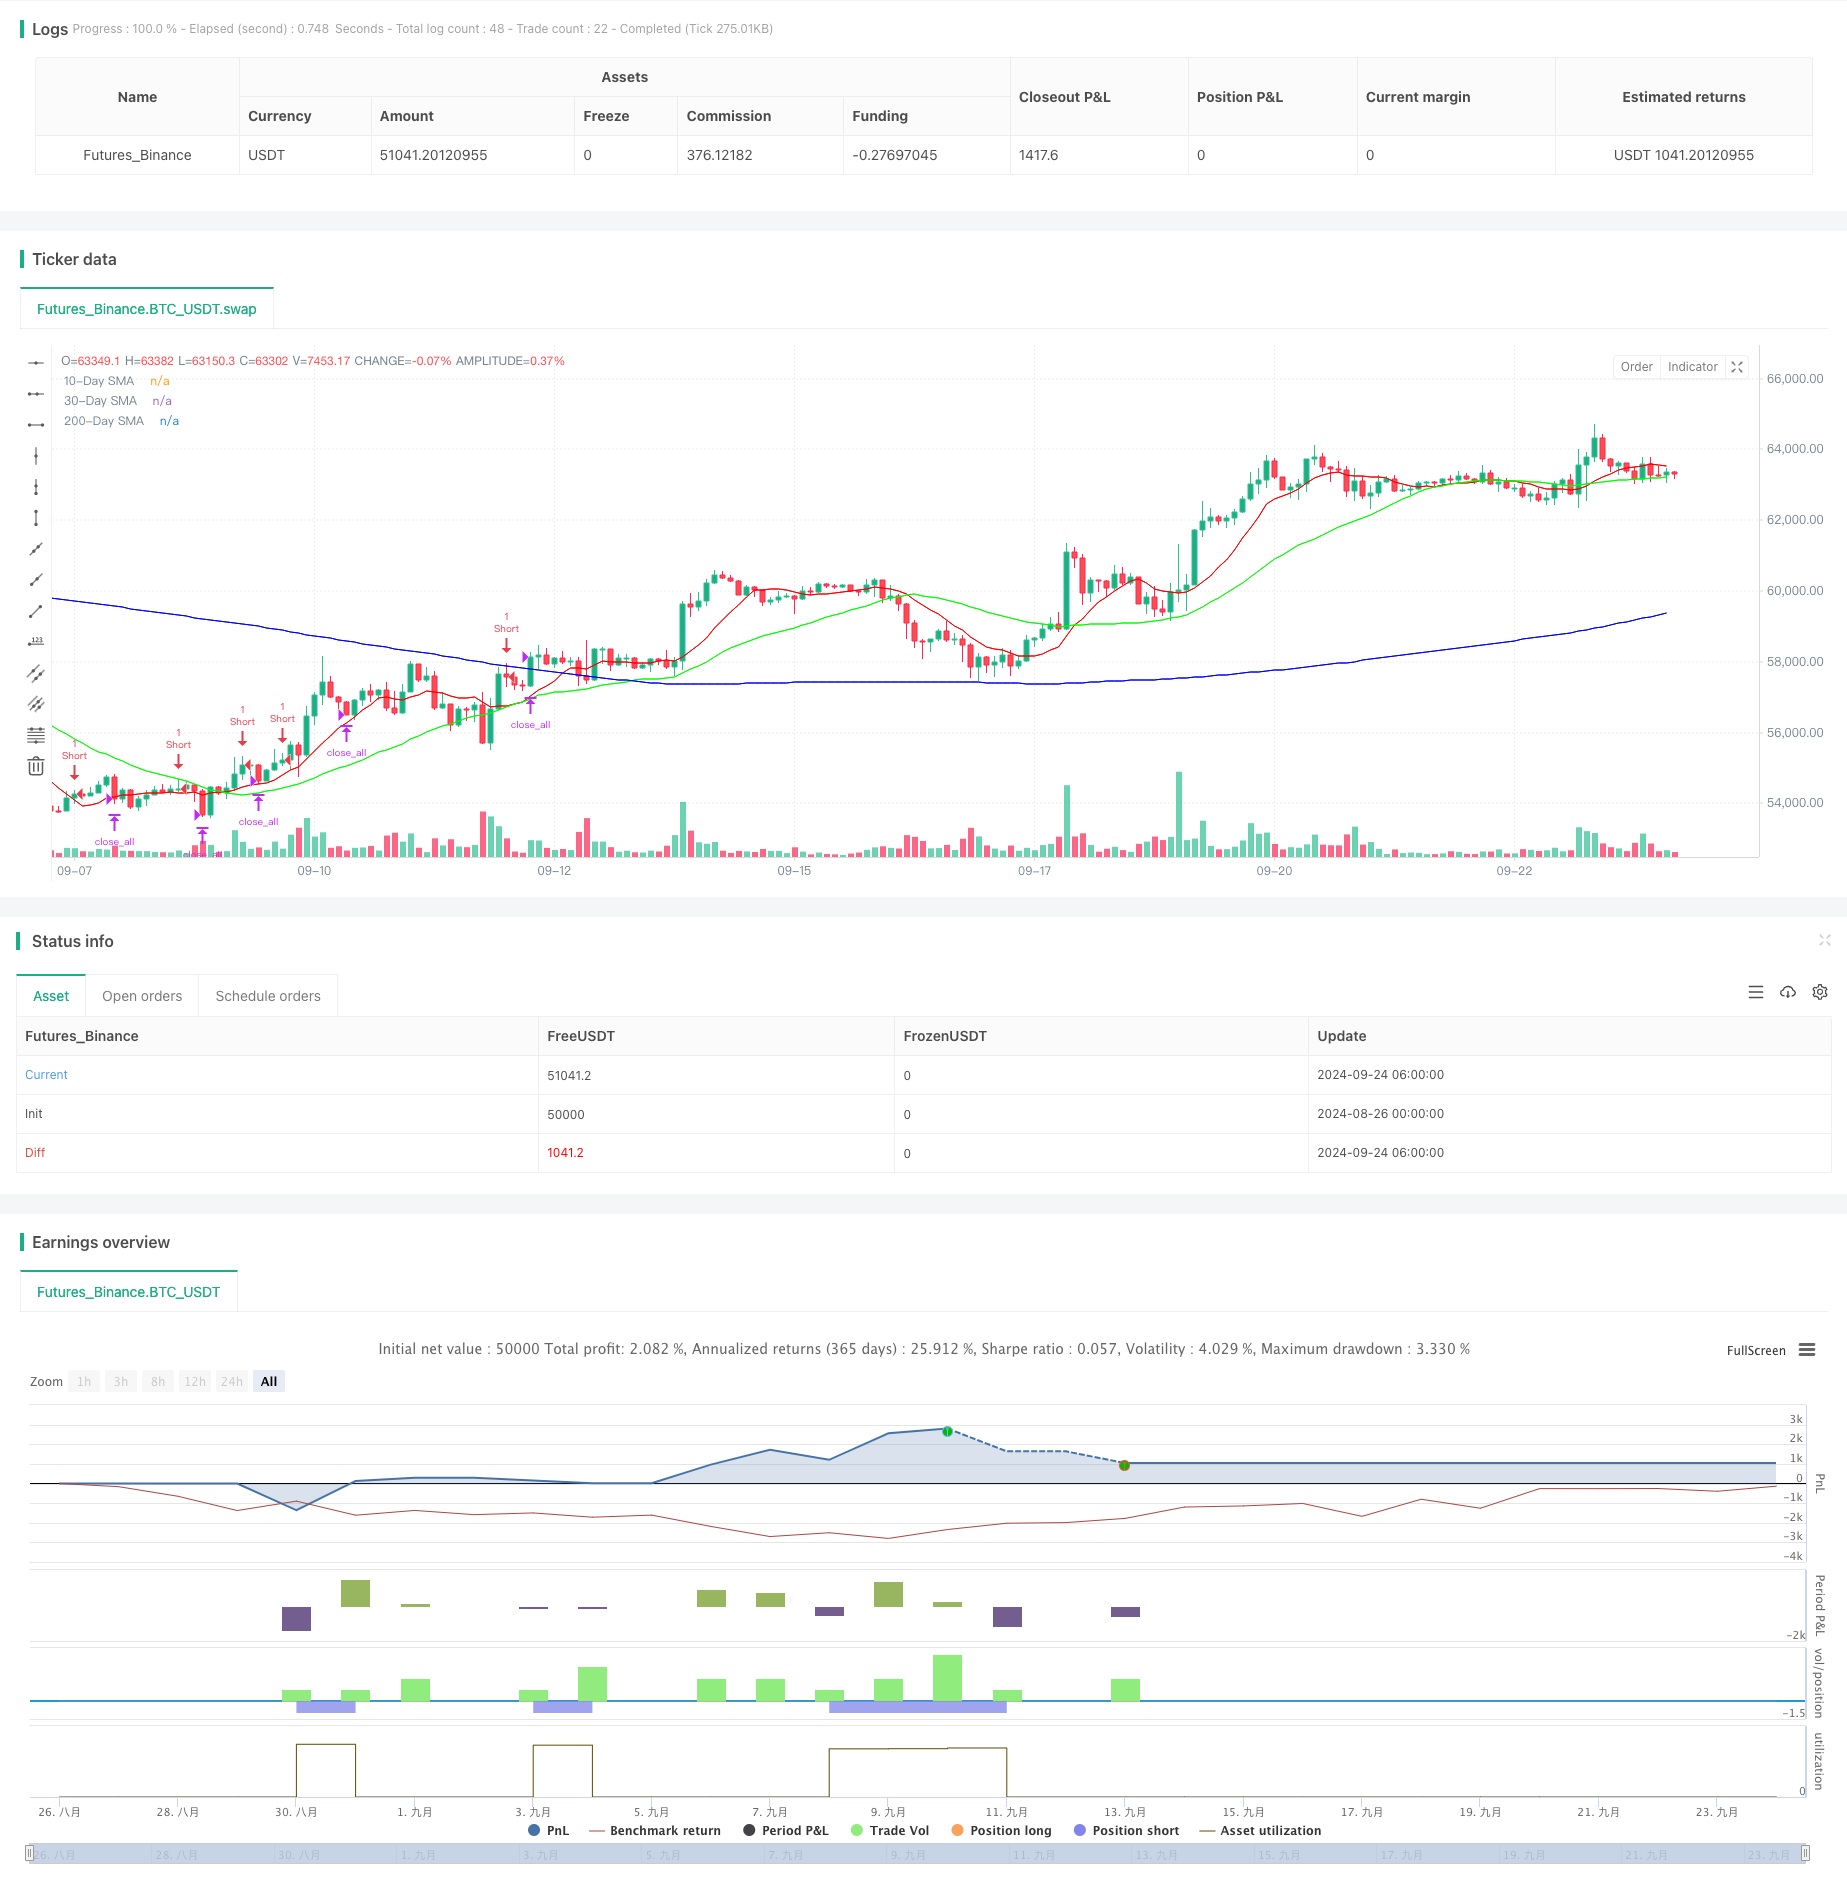
动态仓位管理RSI超买反转策略是一种结合了技术指标和动态仓位管理的短线交易策略。该策略主要利用相对强弱指标(RSI)和简单移动平均线(SMA)来识别潜在的超买状态和反转机会,并通过分批建仓的方式来优化风险收益比。策略的核心思想是在资产价格处于长期下降趋势且出现短期超买时入场做空,并在市场出现超卖或趋势转变信号时平仓。
|
|
|
|
#### 策略原理
|
|
该策略的运作原理包括以下几个关键步骤:
|
|
1. 长期趋势判断:使用200日简单移动平均线(SMA)作为长期趋势过滤器。只有当价格低于200日SMA时,策略才会考虑做空机会。
|
|
2. 超买状态识别:利用2周期RSI指标连续两天高于75来判断短期超买状态。
|
|
3. 分批建仓:初始建仓为10%仓位,随后根据价格走势逐步加仓。当价格高于上一次建仓价时,分别增加20%、30%和40%的仓位。
|
|
4. 退出条件:当2周期RSI低于30(表示可能进入超卖状态)或10日SMA上穿30日SMA(表示可能出现趋势反转)时,平掉所有仓位。
|
|
|
|
#### 策略优势
|
|
1. 风险控制:通过分批建仓和动态仓位管理,有效控制单笔交易的风险敞口。
|
|
2. 趋势跟踪:利用长短期移动平均线组合,既能捕捉长期趋势,又能识别短期反转机会。
|
|
3. 灵活性:策略参数可根据不同市场环境和交易品种进行调整,适应性强。
|
|
4. 自动化执行:策略逻辑清晰,易于编程实现自动化交易。
|
|
|
|
#### 策略风险
|
|
1. 市场风险:在强势上涨行情中,可能面临持续亏损的风险。
|
|
2. 过度加仓风险:分批加仓机制可能导致在错误信号下过度暴露于市场。
|
|
3. 流动性风险:在流动性较差的市场中,大额交易可能造成滑点增加。
|
|
4. 技术指标局限性:RSI和SMA等技术指标可能产生假信号,导致错误交易决策。
|
|
|
|
#### 策略优化方向
|
|
1. 引入波动率指标:结合ATR(平均真实波幅)等波动率指标,动态调整建仓和平仓阈值。
|
|
2. 优化加仓逻辑:可考虑根据市场波动程度动态调整加仓比例,避免在高波动期过度加仓。
|
|
3. 增加基本面过滤:结合基本面因素,如市场情绪指标或宏观经济数据,提高入场信号的可靠性。
|
|
4. 回测优化:通过大量历史数据回测,优化各项参数设置,提高策略的稳定性和盈利能力。
|
|
|
|
#### 总结
|
|
动态仓位管理RSI超买反转策略是一种结合了技术分析和风险管理的短线交易策略。通过利用RSI超买信号和SMA趋势判断,该策略旨在捕捉市场潜在的反转机会。其分批建仓和动态退出机制有助于优化风险收益比。然而,投资者在使用该策略时需注意市场风险和技术指标的局限性,并根据实际交易环境不断优化策略参数和逻辑。通过合理的风险控制和持续的策略优化,该策略有潜力成为一种有效的量化交易工具。
|
|
|
|
||
|
|
|
|
#### Overview
|
|
The Dynamic Position Management RSI Overbought Reversal Strategy is a short-term trading approach that combines technical indicators with dynamic position management. This strategy primarily utilizes the Relative Strength Index (RSI) and Simple Moving Averages (SMA) to identify potential overbought conditions and reversal opportunities, while optimizing risk-reward ratio through a scaled entry mechanism. The core idea is to enter short positions when an asset is in a long-term downtrend and showing short-term overbought signals, then exit when the market indicates oversold conditions or a trend reversal.
|
|
|
|
#### Strategy Principles
|
|
The strategy operates based on the following key steps:
|
|
1. Long-term Trend Assessment: Uses a 200-day Simple Moving Average (SMA) as a long-term trend filter. Short entries are only considered when the price is below the 200-day SMA.
|
|
2. Overbought Condition Identification: Employs a 2-period RSI indicator to detect short-term overbought conditions when it exceeds 75 for two consecutive days.
|
|
3. Scaled Position Building: Initiates with a 10% position size, then gradually increases the position as price moves higher. Additional 20%, 30%, and 40% positions are added when price exceeds previous entry points.
|
|
4. Exit Conditions: Closes all positions when the 2-period RSI drops below 30 (indicating potential oversold conditions) or when the 10-day SMA crosses above the 30-day SMA (signaling a potential trend reversal).
|
|
|
|
#### Strategy Advantages
|
|
1. Risk Management: Effectively controls risk exposure per trade through scaled entries and dynamic position management.
|
|
2. Trend Following: Utilizes a combination of long and short-term moving averages to capture long-term trends while identifying short-term reversal opportunities.
|
|
3. Flexibility: Strategy parameters can be adjusted to adapt to different market environments and trading instruments.
|
|
4. Automation Potential: Clear strategy logic facilitates easy implementation for automated trading systems.
|
|
|
|
#### Strategy Risks
|
|
1. Market Risk: Potential for sustained losses in strongly bullish market conditions.
|
|
2. Over-exposure Risk: The scaling mechanism may lead to excessive market exposure if triggered by false signals.
|
|
3. Liquidity Risk: In less liquid markets, large trades may result in increased slippage.
|
|
4. Technical Indicator Limitations: RSI and SMA indicators may generate false signals, leading to incorrect trading decisions.
|
|
|
|
#### Strategy Optimization Directions
|
|
1. Incorporate Volatility Indicators: Integrate ATR (Average True Range) or other volatility indicators to dynamically adjust entry and exit thresholds.
|
|
2. Refine Scaling Logic: Consider dynamically adjusting scaling ratios based on market volatility to avoid over-exposure during highly volatile periods.
|
|
3. Add Fundamental Filters: Incorporate fundamental factors, such as market sentiment indicators or macroeconomic data, to enhance the reliability of entry signals.
|
|
4. Backtesting and Optimization: Conduct extensive historical data backtests to optimize parameter settings and improve strategy stability and profitability.
|
|
|
|
#### Conclusion
|
|
The Dynamic Position Management RSI Overbought Reversal Strategy is a short-term trading approach that combines technical analysis with risk management principles. By leveraging RSI overbought signals and SMA trend determination, the strategy aims to capture potential market reversals. Its scaled entry and dynamic exit mechanisms help optimize the risk-reward profile. However, investors should be aware of market risks and technical indicator limitations when employing this strategy, and continually optimize strategy parameters and logic based on actual trading environments. With proper risk control and ongoing strategy refinement, this approach has the potential to become an effective quantitative trading tool.
|
|
|
|
[/trans]
|
|
|
|
|
|
|
|
> Source (PineScript)
|
|
|
|
``` pinescript
|
|
/*backtest
|
|
start: 2024-08-26 00:00:00
|
|
end: 2024-09-24 08:00:00
|
|
period: 2h
|
|
basePeriod: 2h
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
|
*/
|
|
|
|
//@version=5
|
|
strategy("TPS Short Strategy by Larry Conners", overlay=true)
|
|
|
|
// Define parameters as inputs
|
|
sma_length_200 = input.int(200, title="200-Day SMA Length")
|
|
rsi_length_2 = input.int(2, title="2-Period RSI Length")
|
|
sma_length_10 = input.int(10, title="10-Day SMA Length")
|
|
sma_length_30 = input.int(30, title="30-Day SMA Length")
|
|
|
|
// Define colors as RGB values
|
|
color_sma_200 = input.color(color.rgb(0, 0, 255), title="200-Day SMA Color") // Blue
|
|
color_sma_10 = input.color(color.rgb(255, 0, 0), title="10-Day SMA Color") // Red
|
|
color_sma_30 = input.color(color.rgb(0, 255, 0), title="30-Day SMA Color") // Green
|
|
|
|
// Calculate indicators
|
|
sma_200 = ta.sma(close, sma_length_200)
|
|
rsi_2 = ta.rsi(close, rsi_length_2)
|
|
sma_10 = ta.sma(close, sma_length_10)
|
|
sma_30 = ta.sma(close, sma_length_30)
|
|
|
|
// Define conditions
|
|
below_sma_200 = close < sma_200
|
|
rsi_2_above_75_two_days = rsi_2[1] > 75 and rsi_2 > 75
|
|
price_higher_than_entry = na(strategy.opentrades.entry_price(0)) ? false : close > strategy.opentrades.entry_price(0)
|
|
|
|
// Entry conditions
|
|
if (below_sma_200 and rsi_2_above_75_two_days and na(strategy.opentrades.entry_price(0)))
|
|
strategy.entry("Short", strategy.short, qty=1) // Short 10% of the position
|
|
|
|
// Scaling in conditions
|
|
if (price_higher_than_entry)
|
|
strategy.entry("Short2", strategy.short, qty=2) // Short 20% more of the position
|
|
|
|
if (price_higher_than_entry)
|
|
strategy.entry("Short3", strategy.short, qty=3) // Short 30% more of the position
|
|
|
|
if (price_higher_than_entry)
|
|
strategy.entry("Short4", strategy.short, qty=4) // Short 40% more of the position
|
|
|
|
// Exit conditions
|
|
exit_condition_rsi_below_30 = rsi_2 < 30
|
|
exit_condition_sma_cross = ta.crossover(sma_10, sma_30)
|
|
|
|
if (exit_condition_rsi_below_30 or exit_condition_sma_cross)
|
|
strategy.close_all() // Close all positions
|
|
|
|
// Plot indicators
|
|
plot(sma_200, color=color_sma_200, title="200-Day SMA")
|
|
plot(sma_10, color=color_sma_10, title="10-Day SMA")
|
|
plot(sma_30, color=color_sma_30, title="30-Day SMA")
|
|
|
|
|
|
```
|
|
|
|
> Detail
|
|
|
|
https://www.fmz.com/strategy/468316
|
|
|
|
> Last Modified
|
|
|
|
2024-09-26 15:29:24
|