
13 KiB
Name
跨时间轴双向突破系统Cross-Period-Breakthrough-System
Author
ChaoZhang
Strategy Description
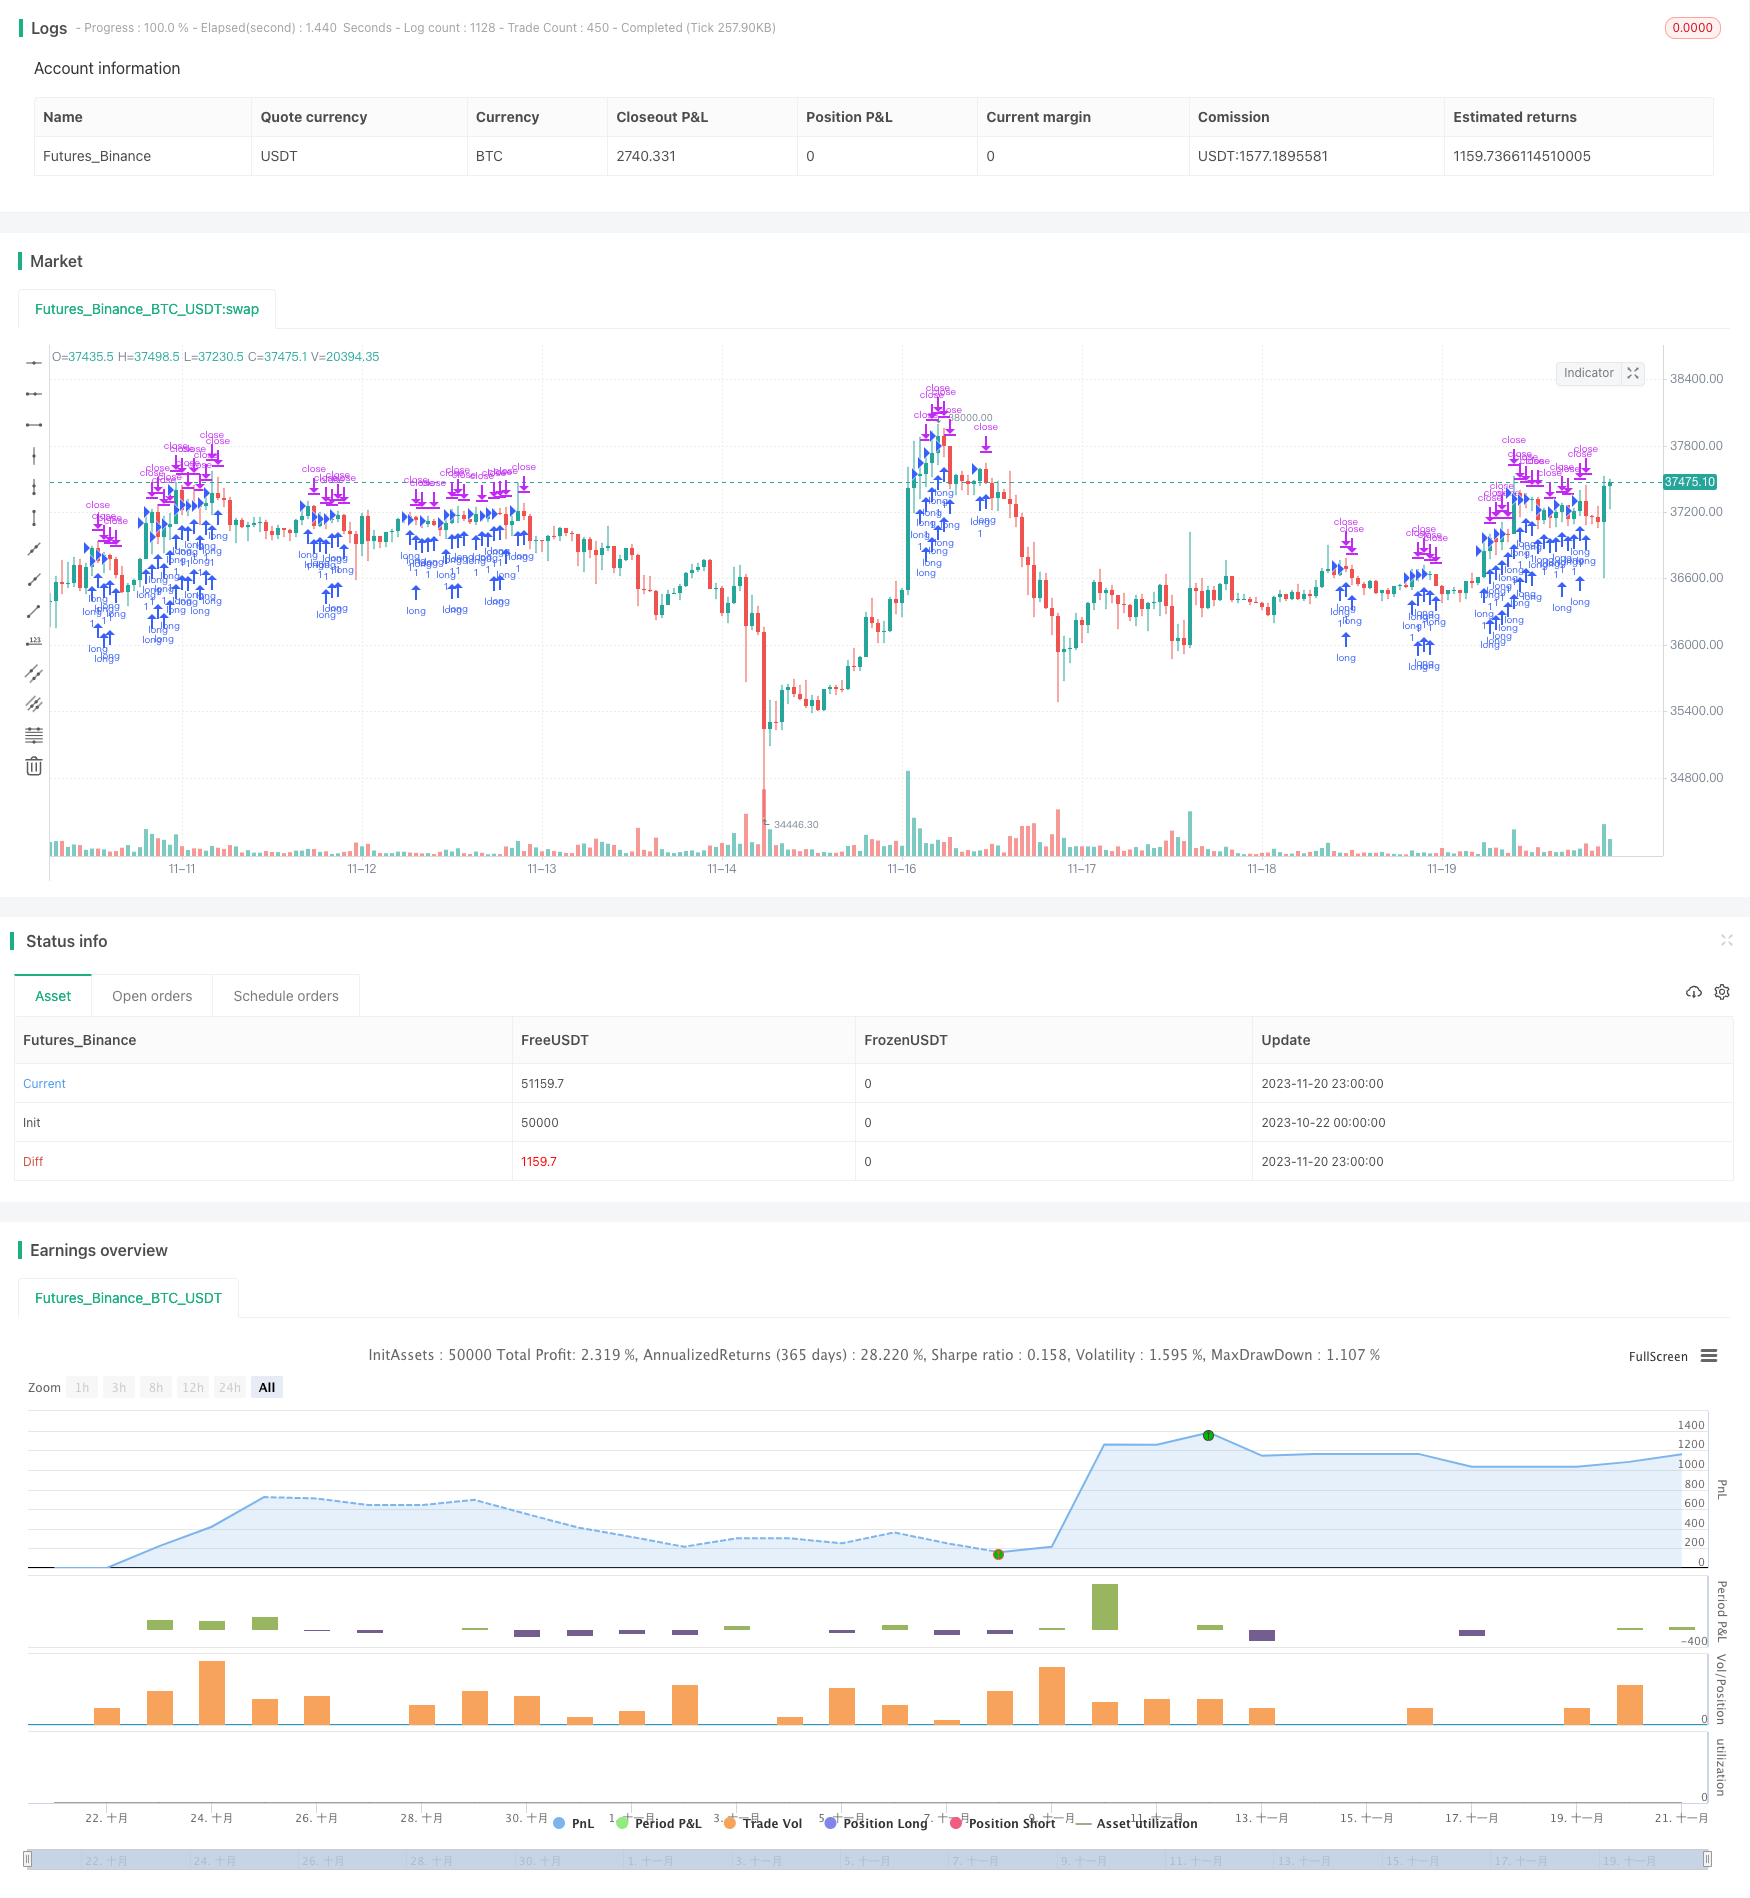
[trans]
概述
这是一个利用移动平均线和MACD指标进行双向突破操作的量化交易策略。它具有跨时间轴操作的特点,即在较长时间周期判断趋势方向,在较短时间周期寻找入场机会的优势。
策略原理
该策略使用3条不同长度期的SMMA均线以及一条EMA均线判断趋势方向。同时,它结合MACD指标判断短期趋势和入场时机。具体来说,它的买入条件是:价格上穿所有均线,且短均线在长均线之上时触发;而卖出条件则是相反,价格下穿所有均线,短均线在长均线之下时触发。
可以看出,该策略同时利用了移动平均线判断中长期趋势方向,以及MACD判断短期反转来捕捉较优的入场时机。这种多时间轴联合操作是该策略的重要特点。
优势分析
这种跨时间轴操作的优势在于,可以在高概率的趋势方向中,选择合适的短期反转点入场,从而获得较优的风险回报比。具体来说,主要有以下3点优势:
-
3条SMMA均线加1条EMA均线多级滤波,可以有效判断中长期趋势方向,避免逆势操作。
-
MACD指标判断短期反转点入场,可以获得较优的入场价位。
-
严格的移动平均线顺序关系作为过滤条件,可以减少误操作的概率。
风险分析
该策略的主要风险在于:
-
移动平均线本身滞后性较强,可能错过短期趋势反转机会。
-
MACD指标容易产生假Signals,需要结合价位过滤。
-
多时间轴判断增加了策略复杂度,容易产生失效的情况。
针对风险1和风险2,可以通过适当缩短均线周期和Signal周期来优化,快速响应短期趋势反转。针对风险3,则需要针对不同品种和周期进行优化测试,使策略参数严格适配该品种的特点。
优化方向
该策略主要可以从以下几个方面进行优化:
-
优化移动平均线和MACD的参数,使其最佳匹配不同周期和品种特点。例如缩短均线长度,加大Signal 参数等。
-
增加止损策略,利用ATR 或其它指标设置合理的移动止损。这可以显著改善策略的风险控制。
-
寻找替代MACD信号的更好指标或过滤方式。例如引入波动率指标,对 Signals 进行过滤等。
-
测试不同的止盈止损比例关系,以获取风险回报比更优的参数组合。
总结
总体来说,这是一个具有独特跨时间轴思路的突破系统。它同时利用移动平均线和 MACD 的优势,实现了多时间段联合判断操作策略。通过对参数和过滤条件进行优化调整,该策略可以成为一个非常实用的量化交易方案。
||
Overview
This is a quantitative trading strategy that utilizes moving averages and MACD indicators for breakthrough operations in both directions. It has the feature of cross-period operations, that is, judging the trend direction on longer time frames and looking for opportunities on shorter time frames.
Strategy Principle
The strategy uses 3 SMMA moving averages of different lengths and 1 EMA moving average to determine the trend direction. At the same time, it combines the MACD indicator to judge short-term trends and entry opportunities. Specifically, the buy trigger condition is: the price breaks through all moving averages upwards, and the shorter averages are above the longer ones; while the sell trigger condition is the opposite, the price breaks through all moving averages downwards, and the shorter averages are below the longer ones.
It can be seen that this strategy utilizes moving averages to judge medium and long term trend directions, and MACD to catch better entry opportunities by judging short term reversals. This multi time frame joint operation is an important feature of the strategy.
Advantage Analysis
The advantage of this cross-period operation is that it can select suitable short-term reversal points to enter in the high-probability trend direction, thus obtaining a better risk-reward ratio. Specifically, there are mainly the following 3 advantages:
-
The 3 SMMA averages plus 1 EMA line multi-level filtering can effectively determine the medium and long term trend direction to avoid trading against the trend.
-
MACD indicator judging short-term reversal points for entering can obtain better entry price levels.
-
The strict moving average sequence relationship as a filtering condition can reduce the probability of mis-operations.
Risk Analysis
The main risks of this strategy are:
-
Moving averages themselves have greater lagging properties, which may miss short-term trend reversal opportunities.
-
MACD indicators are prone to generate false signals and need to be filtered in combination with price levels.
-
Multi time frame judgments increase the complexity of the strategy and are prone to failure.
To address risk 1 and risk 2, we can optimize by appropriately shortening the moving average and signal cycle to respond quickly to short-term trend reversals. For risk 3, we need to optimize and test for different varieties and cycles to strictly adapt the strategy parameters to the characteristics of that variety.
Optimization Directions
The main aspects that this strategy can be optimized include:
-
Optimize the parameters of moving averages and MACD to best match the characteristics of different cycles and varieties. Such as shortening the length of the moving averages, increasing the signal parameter, etc.
-
Increase stop loss strategies using ATR or other indicators to set reasonable moving stops. This can significantly improve the risk control of the strategy.
-
Look for better indicators or filtering methods to replace MACD signals. For example, introduce volatility indicators and filter signals accordingly.
-
Test different profit and loss ratio relationships to obtain parameter combinations with better risk-reward ratios.
Summary
In general, this is a unique breakthrough system with cross-timeframe thinking. It utilizes the advantages of both moving averages and MACD to achieve a joint judgment operation strategy across multiple time frames. By optimizing and adjusting parameters and filtering criteria, this strategy can become a very practical quantitative trading solution.
[/trans]
Strategy Arguments
| Argument | Default | Description |
|---|---|---|
| v_input_1 | true | From Day |
| v_input_2 | true | From Month |
| v_input_3 | 2000 | From Year |
| v_input_4 | true | To Day |
| v_input_5 | 8 | To Month |
| v_input_6 | 2031 | To Year |
| v_input_7 | 3 | Length |
| v_input_8_hl2 | 0 | Source: hl2 |
| v_input_9 | 6 | Length |
| v_input_10_hl2 | 0 | Source: hl2 |
| v_input_11 | 9 | Length |
| v_input_12_hl2 | 0 | Source: hl2 |
| v_input_13 | 50 | Length |
| v_input_14_close | 0 | Source: close |
| v_input_15 | 200 | Length |
| v_input_16_close | 0 | Source: close |
| v_input_17 | 12 | Fast Length |
| v_input_18 | 26 | Slow Length |
| v_input_19_close | 0 | Source: close |
| v_input_20 | 9 | Signal Smoothing |
| v_input_21 | false | Simple MA(Oscillator) |
| v_input_22 | false | Simple MA(Signal Line) |
| v_input_23 | 14 | ATR Length |
| v_input_24 | true | Percentage Multiplier (for ex., 0.7 = 70%) |
| v_input_25 | false | Show actual ATR |
| v_input_26 | 300 | tp |
| v_input_27 | 300 | sl |
| v_input_28 | 3 | Risk % |
| v_input_29 | 2 | max entries |
Source (PineScript)
/*backtest
start: 2023-10-22 00:00:00
end: 2023-11-21 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © SoftKill21

//@version=4
strategy("Koala Script",initial_capital=1000,
     commission_type=strategy.commission.cash_per_contract,
     commission_value=0.000065,
     slippage=3)
fromDay = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
fromMonth = input(defval = 1, title = "From Month", minval = 1, maxval = 12)
fromYear = input(defval = 2000, title = "From Year", minval = 1970)

// To Date Inputs
toDay = input(defval = 1, title = "To Day", minval = 1, maxval = 31)
toMonth = input(defval = 8, title = "To Month", minval = 1, maxval = 12)
toYear = input(defval = 2031, title = "To Year", minval = 1970)


startDate = timestamp(fromYear, fromMonth, fromDay, 00, 00)
finishDate = timestamp(toYear, toMonth, toDay, 00, 00)


len = input(3, minval=1, title="Length")
src = input(hl2, title="Source")
smma = 0.0
sma1 = sma(src, len)
smma := na(smma[1]) ? sma1 : (smma[1] * (len - 1) + src) / len

len2 = input(6, minval=1, title="Length")
src2 = input(hl2, title="Source")
smma2 = 0.0
sma2 = sma(src2, len2)
smma2 := na(smma2[1]) ? sma2 : (smma2[1] * (len2 - 1) + src2) / len2

len3 = input(9, minval=1, title="Length")
src3 = input(hl2, title="Source")
smma3 = 0.0
sma3 = sma(src3, len3)
smma3 := na(smma3[1]) ? sma3 : (smma3[1] * (len3 - 1) + src3) / len3

len4 = input(50, minval=1, title="Length")
src4 = input(close, title="Source")
smma4 = 0.0
sma4 = sma(src4, len4)
smma4 := na(smma4[1]) ? sma4  : (smma4[1] * (len4 - 1) + src4) / len4

len5 = input(200, minval=1, title="Length")
src5 = input(close, title="Source")
out5 = ema(src5, len5)

timeinrange(res, sess) => time(res, sess) != 0
london=timeinrange(timeframe.period, "0300-1045")
londonEntry=timeinrange(timeframe.period, "0300-0845")

time_cond = time >= startDate and time <= finishDate and londonEntry

fast_length = input(title="Fast Length", type=input.integer, defval=12)
slow_length = input(title="Slow Length", type=input.integer, defval=26)
srcc = input(title="Source", type=input.source, defval=close)
signal_length = input(title="Signal Smoothing", type=input.integer, minval = 1, maxval = 50, defval = 9)
sma_source = input(title="Simple MA(Oscillator)", type=input.bool, defval=false)
sma_signal = input(title="Simple MA(Signal Line)", type=input.bool, defval=false)


// Calculating
fast_ma = sma_source ? sma(srcc, fast_length) : ema(srcc, fast_length)
slow_ma = sma_source ? sma(srcc, slow_length) : ema(srcc, slow_length)
macd = fast_ma - slow_ma
signal = sma_signal ? sma(macd, signal_length) : ema(macd, signal_length)
hist = macd - signal


longCond = close > out5 and close > smma4 and close > smma3 and close > smma2 and close > smma and londonEntry and smma > smma2 and smma2>smma3 and smma3>smma4 and smma4>out5
shortCond = close < out5 and close < smma4 and close < smma3 and close < smma2 and close < smma and londonEntry and smma < smma2 and smma2<smma3 and smma3<smma4 and smma4<out5
//longCond2 = crossover(close,out5) and crossover(close,smma4) and crossover(close,smma3) and crossover(close,smma2) and crossover(close,smma) and time_cond
//shortCond2 = crossunder(close,out5) and crossunder(close,smma4) and crossunder(close,smma3) and crossunder(close,smma2) and crossunder(close,smma) and time_cond

length=input(14, title="ATR Length")
mult=input(1.0, title="Percentage Multiplier (for ex., 0.7 = 70%)", step=0.1, minval=0.1, maxval=5.0)

oa=input(false, title="Show actual ATR")

ii=syminfo.pointvalue==0
s=ii?na:oa?atr(length):(syminfo.pointvalue * mult * atr(length))

tp=input(300,title="tp")
sl=input(300,title="sl")


//tp = s*10000
//sl= s*10000


//if(tp>300)
//    tp:=300
//if(sl>300)
//    sl:=300
//if(sl<150)
//    sl:=150
//if(tp<150)
//    tp:=150
strategy.initial_capital = 50000
//MONEY MANAGEMENT--------------------------------------------------------------''
balance = strategy.netprofit + strategy.initial_capital //current balance
floating = strategy.openprofit          //floating profit/loss
risk = input(3,type=input.float,title="Risk %")/100           //risk % per trade


    //Calculate the size of the next trade
temp01 = balance * risk     //Risk in USD
temp02 = temp01/sl        //Risk in lots
temp03 = temp02*100000      //Convert to contracts
size = temp03 - temp03%1000 //Normalize to 1000s (Trade size)
if(size < 10000)
    size := 10000           //Set min. lot size


strategy.entry("long",1,when=longCond )
strategy.exit("closelong","long", profit=tp,loss=sl)
//strategy.close("long",when= crossunder(close[4],smma4) and close[4] > close[3] and close[3]>close[2] and close[2] > close[1] and close[1] > close)
strategy.entry("short",0,when=shortCond )
strategy.exit("closeshort","short", profit=tp,loss=sl)
//strategy.close("short",when= crossover(close[4],smma4) and close[4] < close[3] and close[3]< close[2] and close[2] < close[1] and close[1] < close)

strategy.close_all(when = not london)

maxEntry=input(2,title="max entries")
// strategy.risk.max_intraday_filled_orders(maxEntry)
Detail
https://www.fmz.com/strategy/432890
Last Modified
2023-11-22 15:22:49