
8.0 KiB
Name
跟踪长期趋势的简单拉回策略Simple-Pullback-Strategy-Tracking-Long-Term-Trends
Author
ChaoZhang
Strategy Description
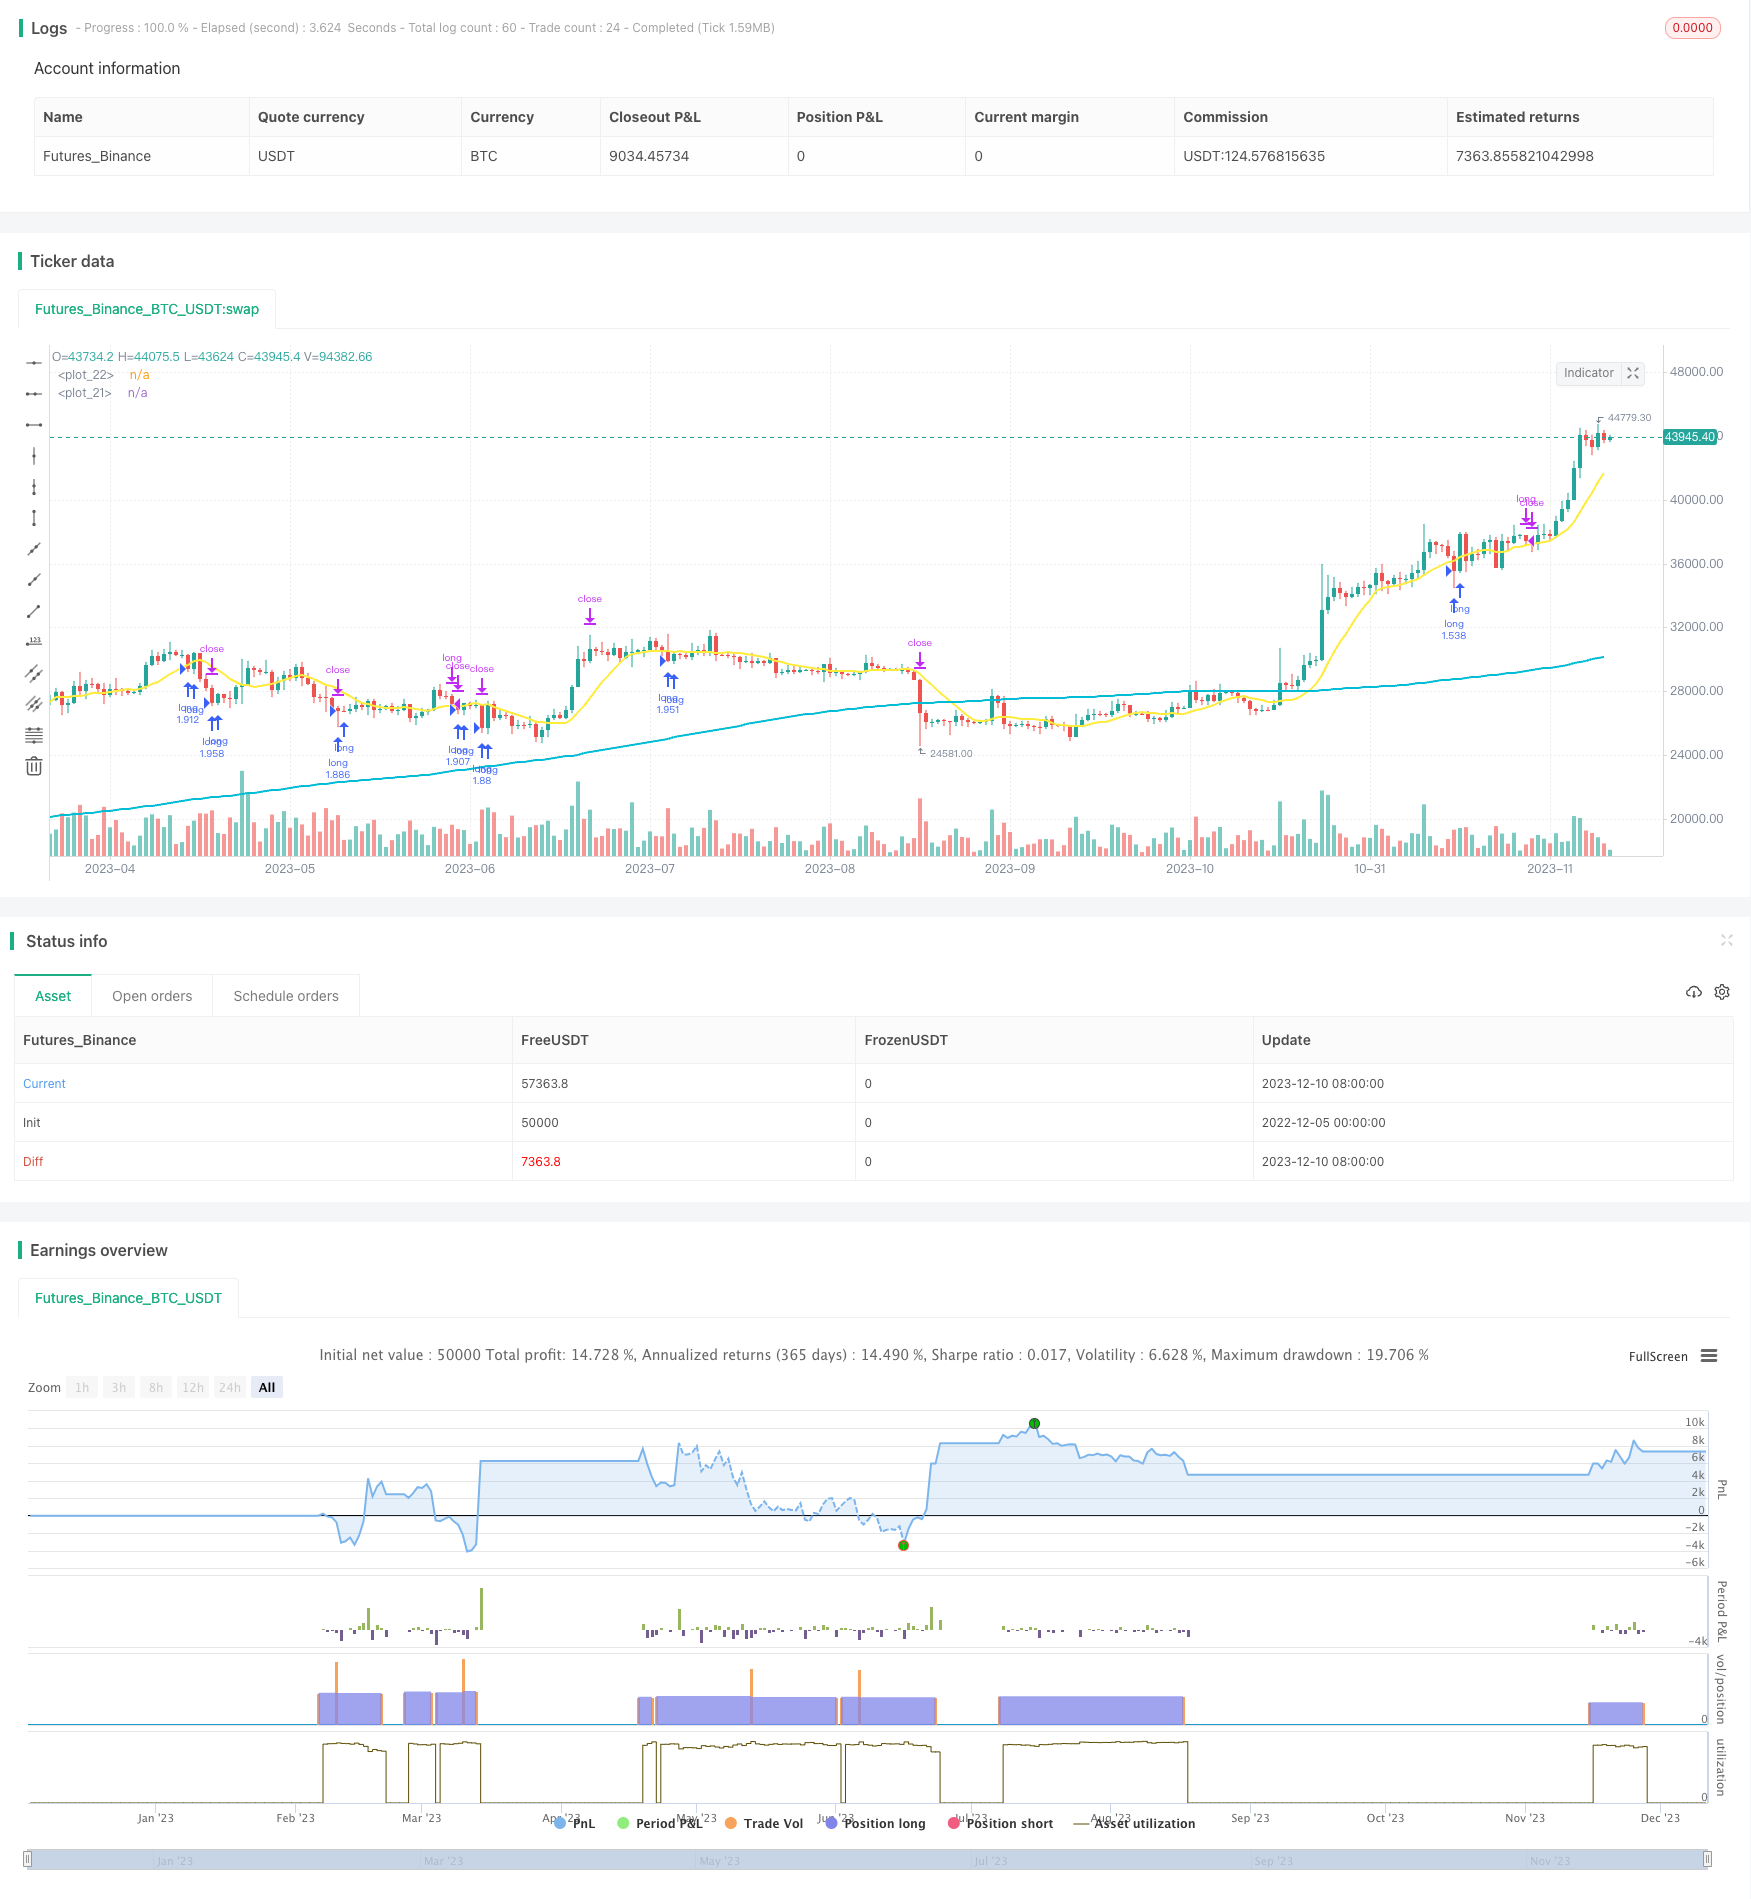 [trans]
该策略通过跟踪长期趋势,在短期拉回时进入场内,实现低买高卖的简单交易逻辑。
策略原理
当收盘价高于200日简单移动平均线时,表示目前处于长期上涨趋势中。当收盘价低于10日简单移动平均线且RSI(3)低于30时,表示价格短期内出现了较大幅度的拉回。这时入场做多,可以以较好的价格跟踪长期上涨趋势。
当做多头仓位后,设置止损线和止盈线。具体来说,止损线为入场价格的95%,止盈线为入场价格的120%。当价格上涨突破10日线时止盈;当价格跌破前一根K线的最低价时止损。
优势分析
该策略最大的优势在于,通过跟踪长期趋势,在短期调整时选择较好的入场点位。从长期来看,股票指数整体处于上涨通道,该策略可以有效跟踪长期上涨趋势。
从短期来看,该策略选择的入场时机处于短期超跌阶段,具有一定的低吸效应。RSI(3)低于30表示价格出现了三根K线的连续下跌,这为 Entry 提供了更好的时点。
风险分析
尽管有止损机制的保护,该策略最大的风险还是来自趋势判断错误。如果判断长期趋势错了,那么入场之后可能会遭遇较大的亏损。此外,止损位置设置过于接近也可能增加风险。
解决方法之一是加入更多的趋势判断指标,如ADX,确保入场时确实处于趋势状态。此外,可以适当放宽止损范围,例如扩大至入场价的90%。
优化方向
该策略可以从以下几个方面进行优化:
-
加入更多的趋势判断指标,确保更准确判断长短期趋势;
-
优化移动平均线的周期参数,寻找最佳的参数组合;
-
测试不同的止盈止损参数设置,找到最优的参数组合;
-
尝试在入场时加入其他因子判断,如成交量放大等,以提高入场的效率。
总结
该策略主要思路是跟踪长期趋势,在短期调整时选择较好的入场点位。它最大的优势是入场价格优化,能够实现低买高卖,长期跟踪上涨趋势。同时,策略也考虑了风险控制,设置了止损机制。总的来说,这是一个非常简单直接、容易理解和实现的趋势跟踪策略。通过一些参数和规则的优化,可以进一步提高策略的效果。
||
This strategy tracks long term trends and enters the market during short term pullbacks, achieving a simple trading logic of buying low and selling high.
Strategy Principle
When the close price is above the 200-day simple moving average, it indicates that the current market is in a long-term upward trend. When the close price is below the 10-day simple moving average and the RSI(3) is below 30, it indicates that the price has pulled back sharply in the short term. At this time, go long to track the long-term upward trend at a better price.
After taking a long position, set a stop loss and take profit. Specifically, the stop loss is set at 95% of the entry price, and the take profit is set at 120% of the entry price. When the price breaks through the 10-day line on the upside, take profit; when the price breaks below the low of the previous K-line, stop loss.
Advantage Analysis
The biggest advantage of this strategy is that by tracking long-term trends and choosing better entry points during short-term adjustments, it can achieve low-buying and high-selling. In the long run, stock indices are generally in an upward channel, and this strategy can effectively track long-term upward trends.
In the short term, the entry point selected by this strategy is in a short-term oversold stage, with a certain low-buying effect. RSI (3) below 30 indicates that the price has fallen continuously for three K-lines, which provides a better timing for entry.
Risk Analysis
Despite the protection of the stop loss mechanism, the biggest risk of this strategy still comes from the wrong judgment of the trend. If the long-term trend is judged wrong, it may encounter greater losses after entering the market. In addition, if the stop loss position is set too close, the risk may also increase.
One solution is to add more trend judgment indicators, such as ADX, to ensure that it is indeed in a trend state when entering the market. In addition, appropriately relax the stop loss range, such as expanding it to 90% of the entry price.
Optimization Directions
This strategy can be optimized in the following aspects:
-
Add more trend judgment indicators to ensure more accurate judgments of short-term and long-term trends;
-
Optimize the cycle parameters of the moving average to find the best parameter combination;
-
Test different take profit and stop loss parameter settings to find the optimal parameter combination;
-
Try adding other factors when entering the market, such as trading volume amplification, to improve entry efficiency.
Summary
The main idea of this strategy is to choose a better entry point during short-term adjustments while tracking long-term trends. Its biggest advantage is the optimization of entry price, which can achieve low-buying and high-selling to track long-term upward trends. At the same time, the strategy also considers risk control by setting a stop loss mechanism. Overall, this is a very simple, straightforward and easy to understand and implement trend tracking strategy. By optimizing some parameters and rules, the effect of the strategy can be further improved.[/trans]
Strategy Arguments
| Argument | Default | Description |
|---|---|---|
| v_input_int_1 | 200 | (?パラメータ)長期移動平均BASE200/period of long term sma |
| v_input_int_2 | 10 | 長期移動平均BASE10/period of short term sma |
| v_input_int_3 | 5 | 損切の割合%/stoploss percentages |
| v_input_int_4 | 20 | 利食いの割合%/take profit percentages |
| v_input_1 | timestamp(01 Jan 2000 13:30 +0000) | (?期間)バックテストを始める日/start trade day |
| v_input_2 | timestamp(1 Jan 2099 19:30 +0000) | バックテスを終わる日/finish date day |
Source (PineScript)
/*backtest
start: 2022-12-05 00:00:00
end: 2023-12-11 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © tsujimoto0403

//@version=5
strategy("simple pull back", overlay=true,default_qty_type=strategy.percent_of_equity,
     default_qty_value=100)

//input value
malongperiod=input.int(200,"長期移動平均BASE200/period of long term sma",group = "パラメータ")
mashortperiod=input.int(10,"長期移動平均BASE10/period of short term sma",group = "パラメータ")
stoprate=input.int(5,title = "損切の割合%/stoploss percentages",group = "パラメータ")
profit=input.int(20,title = "利食いの割合%/take profit percentages",group = "パラメータ")
startday=input(title="バックテストを始める日/start trade day", defval=timestamp("01 Jan 2000 13:30 +0000"), group="期間")
endday=input(title="バックテスを終わる日/finish date day", defval=timestamp("1 Jan 2099 19:30 +0000"), group="期間")


//polt indicators that we use
malong=ta.sma(close,malongperiod)
mashort=ta.sma(close,mashortperiod)

plot(malong,color=color.aqua,linewidth = 2)
plot(mashort,color=color.yellow,linewidth = 2)

//date range
datefilter = true

//open conditions
if close>malong and close<mashort and strategy.position_size == 0 and datefilter and ta.rsi(close,3)<30
    strategy.entry(id="long", direction=strategy.long)

//sell conditions
strategy.exit(id="cut",from_entry="long",stop=(1-0.01*stoprate)*strategy.position_avg_price,limit=(1+0.01*profit)*strategy.position_avg_price)


if close>mashort and close<low[1] and strategy.position_size>0
    strategy.close(id ="long")
Detail
https://www.fmz.com/strategy/435128
Last Modified
2023-12-12 15:32:15