
7.5 KiB
Name
快速RSI反转策略Fast-RSI-Reversal-Strategy
Author
ChaoZhang
Strategy Description
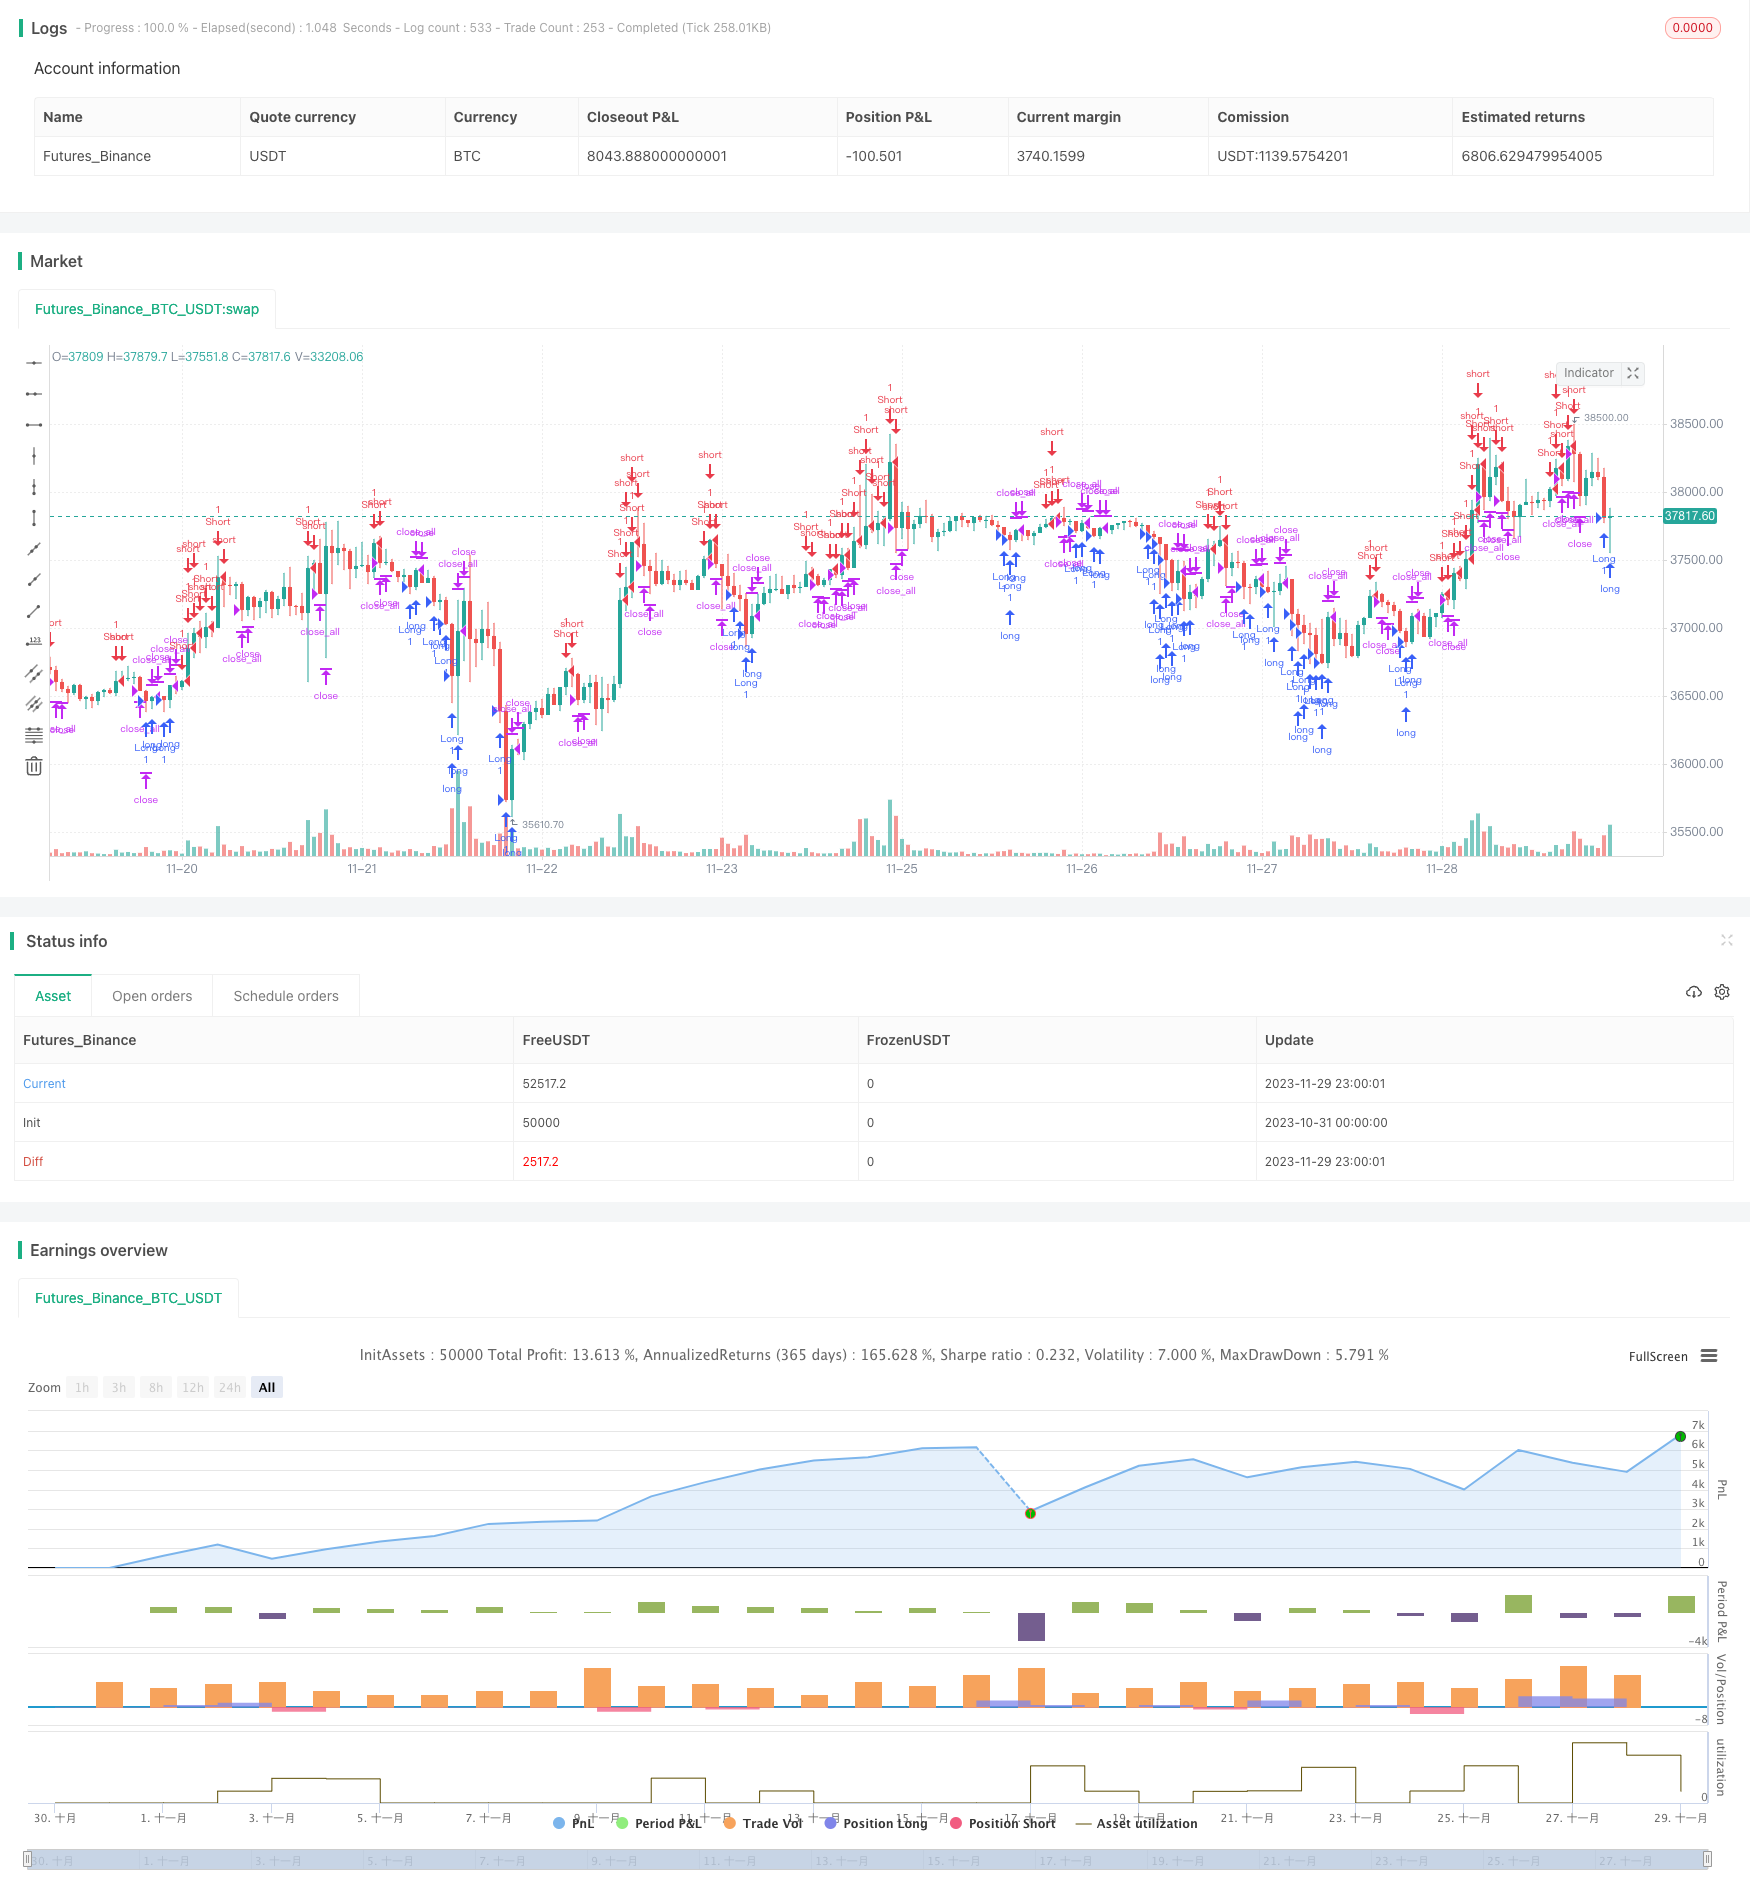 这里是我根据你提供的代码和要求写的SEO文章,包含了策略名称、概述、策略原理、优势分析、风险分析、优化方向和总结等部分:
[trans]
概述
本策略是一种快速RSI反转交易策略,主要思想是当RSI指标超买超卖时,判断短期反转机会。它使用3日RSI作为指标判断超买超卖,并结合30日均线判断突破信号,在超买超卖发生反转时打开仓位。
策略原理
该策略使用两个指标:
-
3日RSI指标判断超买超卖。
-
30日均线判断反转信号强度。当反转K线实体大于30日均线一半时,作为入场信号。
具体交易规则:
多头信号:RSI指标小于低位(默认25),并且当前K线实体大于30日均线的一半,做多。
空头信号:RSI指标大于高位(默认75),并且当前K线实体大于30日均线的一半,做空。
止损信号:持有多头时RSI指标上穿高位,或持有空头时RSI指标下穿低位,同时K线实体大于30日均线一半,平仓。
优势分析
该策略具有以下优势:
-
使用短周期RSI判断超买超卖,能快速捕捉短期反转机会。
-
结合均线过滤增加信号的可靠性,避免在震荡行情中被套。
-
回撤可控,最大回撤不会太大。
-
仓位控制规则清晰,不会频繁开仓。
风险分析
该策略也存在以下风险:
-
反转失败的风险。超买超卖不一定会发生反转。
-
趋势行情中逆势操作亏损风险。
-
实体过滤条件过于严格,容易漏入场机会。
-
参数灵敏度较高,RSI周期和实体周期需要调整。
优化方向
该策略可以从以下方面进行优化:
-
优化RSI参数,寻找最佳周期。
-
优化均线参数,寻找最佳实体过滤周期。
-
增加止损策略,如移动止损、曲线止损等,控制单笔亏损。
-
增加趋势判断规则,避免逆势操作。
总结
本策略整体来说是一个短期反转为主的RSI策略,通过快速RSI判断超买超卖捕捉反转,并用均线实体过滤确认,具有回撤可控、仓位控制明确的优点,适合短线操作,但需要注意反转失败和逆势操作的风险,可从优化参数、止损和趋势判断等方面进行改进。
||
Overview
This strategy is a fast RSI reversal trading strategy that mainly captures reversal opportunities when RSI is overbought or oversold. It uses 3-day RSI to judge overbought and oversold levels, and combines 30-day MA to determine breakthrough signals, opening positions when reversals occur after overbought or oversold status.
Strategy Logic
The strategy uses two indicators:
-
3-day RSI to judge overbought and oversold levels.
-
30-day MA to determine the strength of reversal signals. When the reversal bar body is greater than half of the 30-day MA, it is used as the entry signal.
Specific trading rules:
Long signal: When RSI is below the lower limit (default 25) and the current bar body is greater than half of the 30-day MA, go long.
Short signal: When RSI is above the upper limit (default 75) and the current bar body is greater than half of the 30-day MA, go short.
Exit signal: When holding long positions, if RSI crosses above the upper limit, or when holding short positions, if RSI crosses below the lower limit, meanwhile the bar body is greater than half of the 30-day MA, close positions.
Advantage Analysis
The advantages of this strategy include:
-
Using short-period RSI to capture short-term reversal opportunities quickly.
-
Increasing signal reliability by combining with MA filter, avoiding whipsaws in range-bound markets.
-
Controllable drawdowns, maximum drawdown won't be too large.
-
Clear position control rules, avoids over-trading.
Risk Analysis
The risks of this strategy include:
-
Failed reversal risk. Overbought and oversold does not necessarily lead to reversals.
-
Loss risk by trading against the trend in trending markets.
-
Missing opportunities due to too strict bar filter rules.
-
High parameter sensitivity, RSI and MA periods need adjustment.
Optimization Directions
The strategy can be optimized from the following aspects:
-
Optimize RSI parameters to find the optimal period.
-
Optimize MA parameters to determine the best bar filter period.
-
Add stop loss strategies like trailing stop loss, to control single trade loss.
-
Add trend determination rules to avoid trading against trends.
Conclusion
In conclusion, this is a short-term reversal-focused RSI strategy. It captures reversals by identifying quick RSI overbought and oversold levels, and uses MA bar filter to confirm entries. The advantages are controllable drawdowns and clear position controls. It is suitable for short-term trading but should watch out risks of failed reversals and trading against trends. It can be improved by parameter optimization, adding stop loss, and judging trends.
[/trans]
Strategy Arguments
| Argument | Default | Description |
|---|---|---|
| v_input_1 | true | Long |
| v_input_2 | true | Short |
| v_input_3 | 25 | RSI limit |
| v_input_4 | 1900 | From Year |
| v_input_5 | 2100 | To Year |
| v_input_6 | true | From Month |
| v_input_7 | 12 | To Month |
| v_input_8 | true | From day |
| v_input_9 | 31 | To day |
Source (PineScript)
/*backtest
start: 2023-10-31 00:00:00
end: 2023-11-30 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy(title = "Noro's Fast RSI Strategy v1.0", shorttitle = "Fast RSI str 1.0", overlay = true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 5)

//Settings
needlong = input(true, defval = true, title = "Long")
needshort = input(true, defval = true, title = "Short")
limit = input(25, defval = 25, minval = 1, maxval = 100, title = "RSI limit")
fromyear = input(1900, defval = 1900, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To day")

//Fast RSI
src = close
fastup = rma(max(change(src), 0), 3)
fastdown = rma(-min(change(src), 0), 3)
fastrsi = fastdown == 0 ? 100 : fastup == 0 ? 0 : 100 - (100 / (1 + fastup / fastdown))
uplimit = 100 - limit
dnlimit = limit

//Body
body = abs(close - open)
emabody = ema(body, 30) / 2

//Signals
bar = close > open ? 1 : close < open ? -1 : 0
up = bar == -1 and fastrsi < dnlimit and body > emabody
dn = bar == 1 and fastrsi > uplimit and body > emabody
exit = ((strategy.position_size > 0 and fastrsi > dnlimit) or (strategy.position_size < 0 and fastrsi < uplimit)) and body > emabody

//Trading
if up
    strategy.entry("Long", strategy.long, needlong == false ? 0 : na, when=(time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 00, 00)))

if dn
    strategy.entry("Short", strategy.short, needshort == false ? 0 : na, when=(time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 00, 00)))

if time > timestamp(toyear, tomonth, today, 00, 00) or exit
    strategy.close_all()
Detail
https://www.fmz.com/strategy/433901
Last Modified
2023-12-01 13:37:20