
8.7 KiB
Name
多重RSI指标交易策略Multi-RSI-Indicators-Trading-Strategy
Author
ChaoZhang
Strategy Description
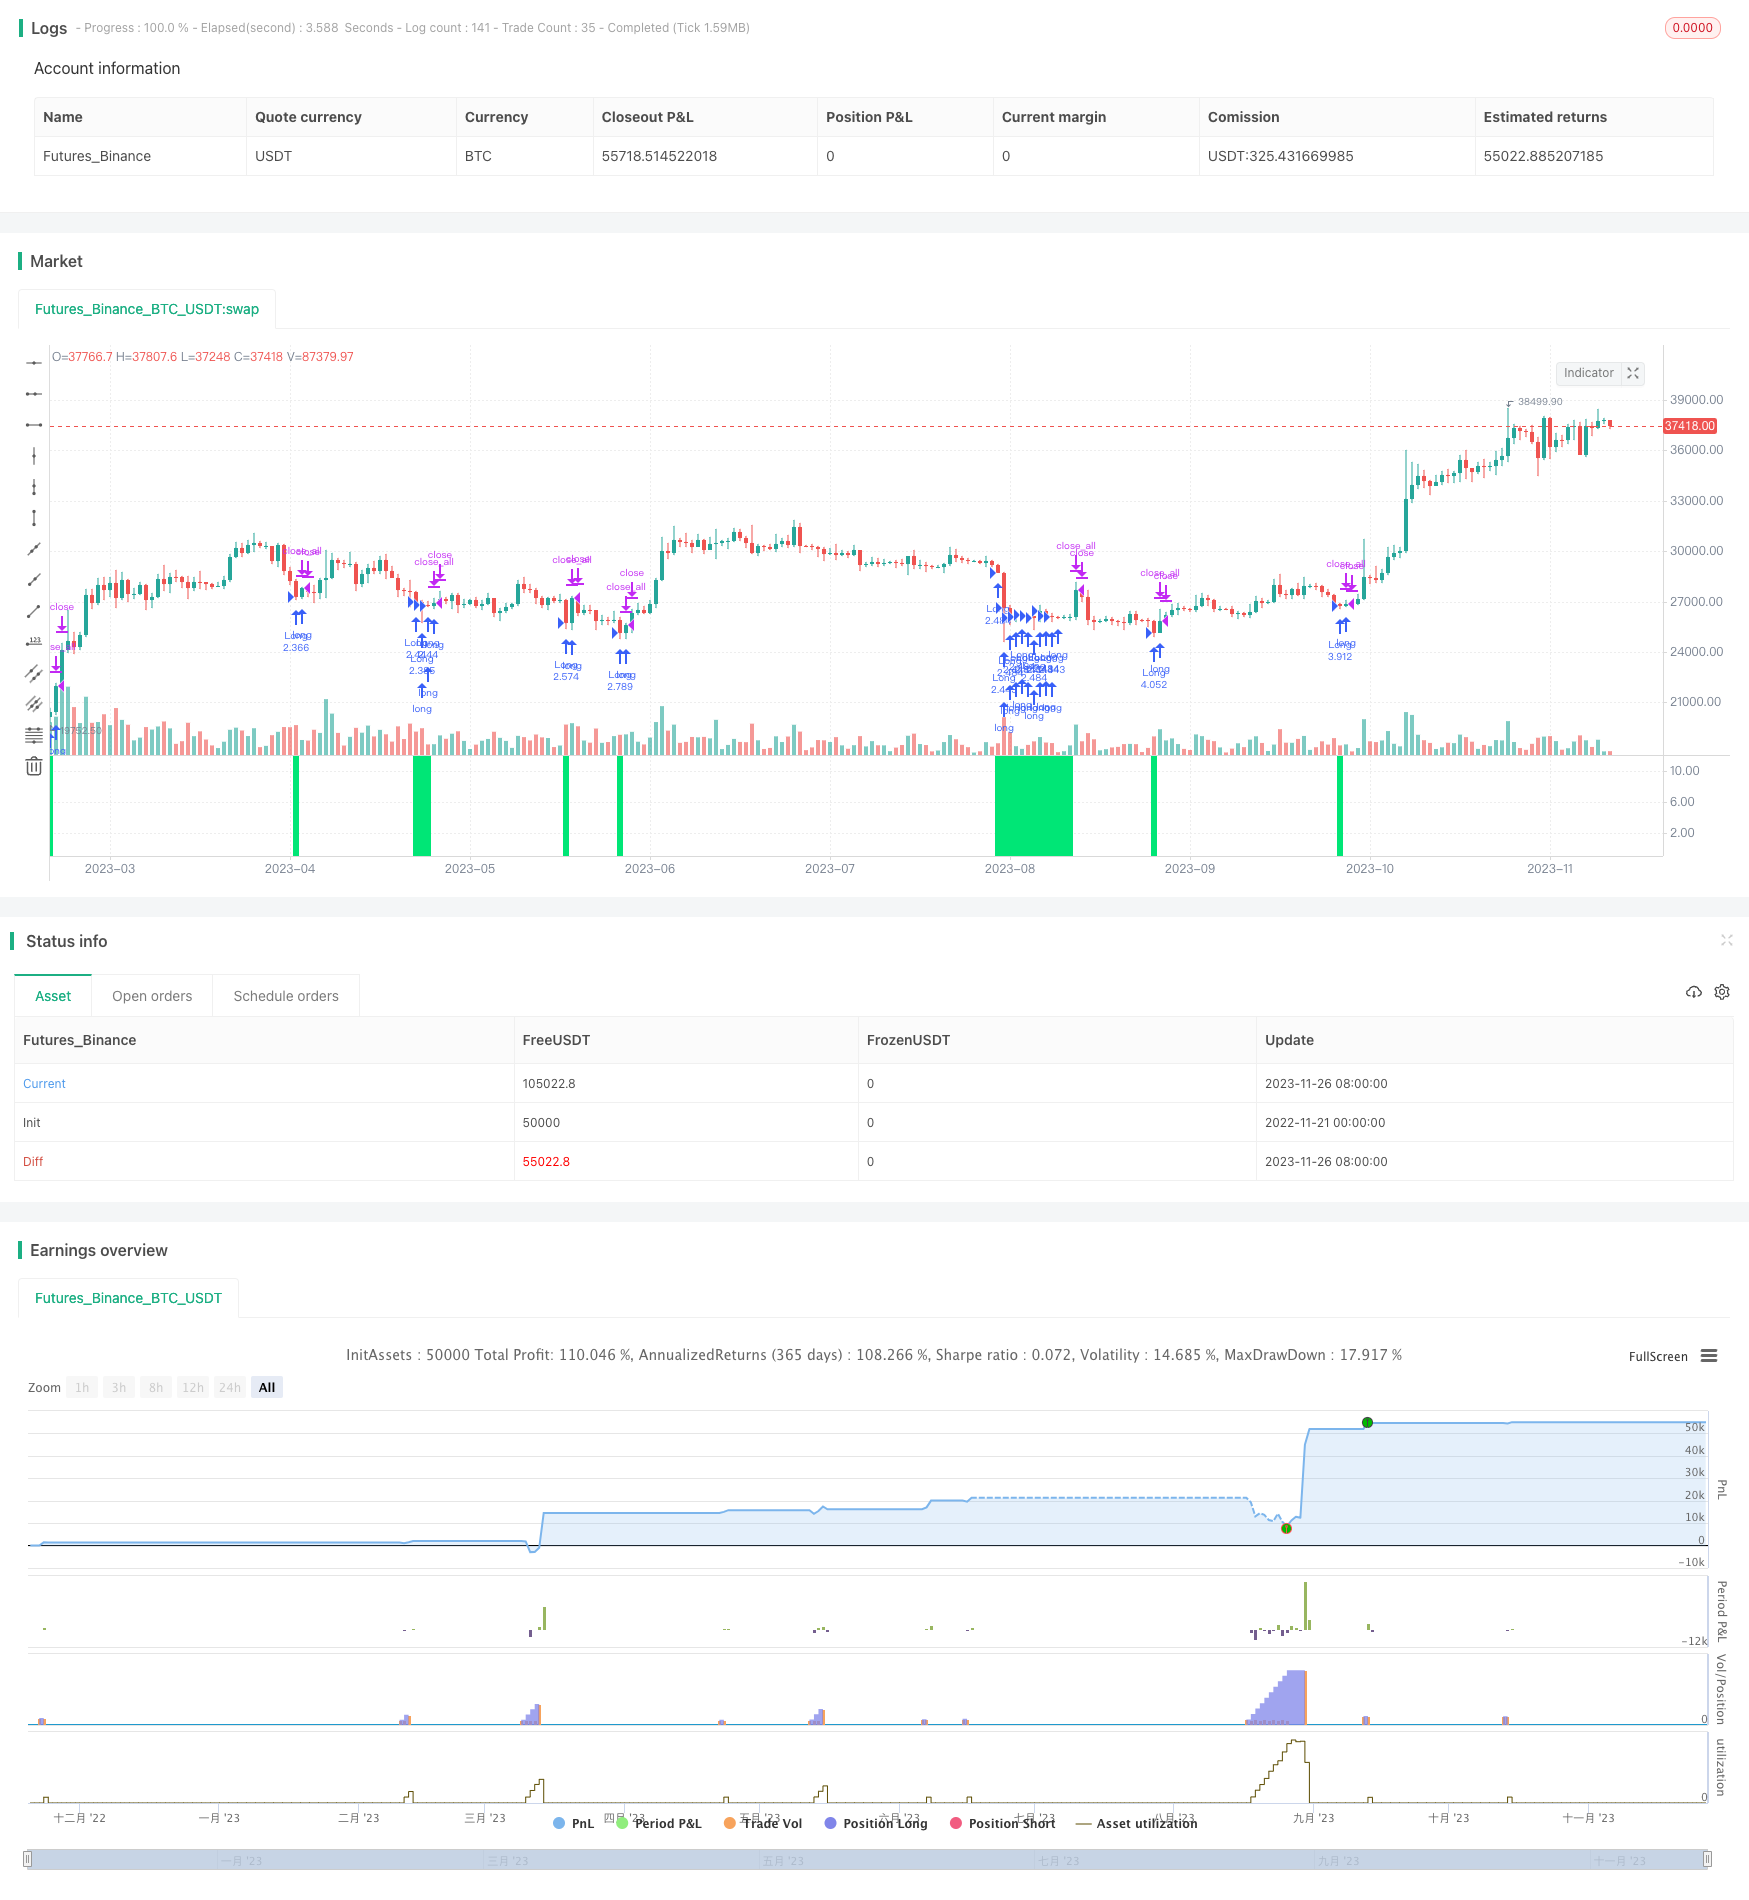
[trans]
概述
多重RSI指标交易策略通过组合使用多个RSI指标来识别交易机会,实现趋势跟踪。策略灵活运用1-5个RSI指标,根据指标数值判断入场和出场时机。
策略原理
该策略通过输入参数选择使用1-5个RSI指标,每个RSI指标都可以独立配置参数期数和限值。当任意一个RSI指标数值低于对应限值时产生买入信号,信号强度由触发信号的RSI指标期数决定,期数越高信号越强。当RSI指标回升超过限值时产生平仓信号。策略可以灵活使用颜色过滤器,以及设置交易时间段进行限制。
优势分析
该策略最大优势在于可以同时评估多个周期的RSI指标,从长短多个维度判断趋势和反转机会,提高交易决策的准确性。另外,策略允许自由配置各RSI指标的参数,可以针对不同市场调整,可以大大扩展策略的适应性。通过颜色过滤,也可以有效过滤假突破。此外,还加入了交易时间和仓位控制模块,可以有效控制风险。
风险分析
该策略主要风险在于多重RSI指标组合判断时,可能会出现信号冲突的情况。例如短周期RSI产生买入信号,但长周期RSI仍处于超卖状态,这时究竟以哪个信号为准需要结合交易者自己的经验进行决策。此外,RSI指标容易受到震荡行情的误导,这点需要通过辅助指标或大资金的账户进行验证。
优化方向
该策略可以考虑加入移动平均线或布林带等趋势辅助指标来验证RSI信号,提高判断的准确性。此外,也可以思考加入一定的机器学习算法,利用多因子评分的方法来自动判断Entry和Close信号的可靠性。从风险控制角度考虑,也可以设置浮亏线或最大回撤线来止损。
总结
多重RSI指标交易策略整体来说非常有创新性,其指标组合和参数设置的灵活性为快速适应市场变化提供了可能。加入的模块化功能设计也使得策略优化空间很大。如果再配合机器学习或风险控制手段,效果可以进一步提升。 ||
Overview
The multi RSI indicators trading strategy identifies trading opportunities by combining multiple RSI indicators to track trends. The strategy flexibly utilizes 1-5 RSI indicators and determines entry and exit timing according to the indicator values.
Strategy Logic
The strategy allows selecting 1-5 RSI indicators through input parameters. Each RSI indicator can be configured independently with period and limit values. When any RSI drops below the limit value, a buy signal is triggered. The signal strength is determined by the period of the triggered RSI indicator, with higher period meaning stronger signal. When RSI rises back above the limit, a close position signal is triggered. The strategy also provides flexibility to use color filter and restrict trading hours.
Advantage Analysis
The biggest advantage of this strategy is the capability to assess multiple timeframes using various RSIs, judging both trend and reversal opportunities from long and short dimensions to improve accuracy. In addition, the flexible configuration of each RSI indicator greatly expands the adaptivity across different markets. Fake breakouts can also be efficiently filtered out using color filters. Risk control modules like trading hours and position sizing provide effective risk management.
Risk Analysis
The major risk is conflicting signals when combining multiple RSI judgments. For instance, shorter RSI produces a buy whilst longer RSI is still oversold. One must rely on experience to determine which signal takes precedence. Also, RSI is prone to whipsaws which requires validation using other indicators or large accounts.
Optimization Directions
The strategy can consider adding trend assisting indicators like moving averages or Bollinger bands to validate RSI signals and improve accuracy. Additionally, certain machine learning algorithms can also be explored, using multi-factor scoring to automatically determine signal reliability. For risk control, floating loss or maximum drawdown stop lines can be implemented for stop loss purposes.
Summary
In summary, the multi RSI indicators trading strategy is very innovative. Its flexibility in indicators combination and parameters makes it adaptable to evolving markets. Further improvements can be achieved by incorporating machine learning algorithms and more risk control measures given its modular design. [/trans]
Strategy Arguments
| Argument | Default | Description |
|---|---|---|
| v_input_1 | 100 | Lot, % |
| v_input_2 | true | Use RSI 1 |
| v_input_3 | 4 | RSI 1 Period |
| v_input_4 | 20 | RSI 1 Limit |
| v_input_5 | true | Use RSI 2 |
| v_input_6 | 7 | RSI 2 Period |
| v_input_7 | 25 | RSI 2 Limit |
| v_input_8 | true | Use RSI 3 |
| v_input_9 | 14 | RSI 3 Period |
| v_input_10 | 30 | RSI 3 Limit |
| v_input_11 | false | Use RSI 4 |
| v_input_12 | 21 | RSI 4 Period |
| v_input_13 | 35 | RSI 4 Limit |
| v_input_14 | false | Use RSI 5 |
| v_input_15 | 28 | RSI 5 Period |
| v_input_16 | 40 | RSI 5 Limit |
| v_input_17 | false | Use color filter |
| v_input_18 | 1900 | From Year |
| v_input_19 | 2100 | To Year |
| v_input_20 | true | From Month |
| v_input_21 | 12 | To Month |
| v_input_22 | true | From Day |
| v_input_23 | 31 | To Day |
Source (PineScript)
/*backtest
start: 2022-11-21 00:00:00
end: 2023-11-27 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Noro
//2018
//@version=2

strategy(title = "Noro's Symphony Strategy v1.1", shorttitle = "Symphony str 1.1", overlay = false, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 20)

//Settings

//needlong = input(true, defval = true, title = "Long")
//needshort = input(true, defval = true, title = "Short")

capital = input(100, defval = 100, minval = 1, maxval = 10000, title = "Lot, %")
usersi1 = input(true, defval = true, title = "Use RSI 1")
rsiperiod1 = input(4, defval = 4, minval = 2, maxval = 100, title = "RSI 1 Period")
rsilimit1 = input(20, defval = 20, minval = 2, maxval = 50, title = "RSI 1 Limit")
usersi2 = input(true, defval = true, title = "Use RSI 2")
rsiperiod2 = input(7, defval = 7, minval = 2, maxval = 100, title = "RSI 2 Period")
rsilimit2 = input(25, defval = 25, minval = 2, maxval = 50, title = "RSI 2 Limit")
usersi3 = input(true, defval = true, title = "Use RSI 3")
rsiperiod3 = input(14, defval = 14, minval = 2, maxval = 100, title = "RSI 3 Period")
rsilimit3 = input(30, defval = 30, minval = 2, maxval = 50, title = "RSI 3 Limit")
usersi4 = input(false, defval = false, title = "Use RSI 4")
rsiperiod4 = input(21, defval = 21, minval = 2, maxval = 100, title = "RSI 4 Period")
rsilimit4 = input(35, defval = 35, minval = 2, maxval = 50, title = "RSI 4 Limit")
usersi5 = input(false, defval = false, title = "Use RSI 5")
rsiperiod5 = input(28, defval = 28, minval = 2, maxval = 100, title = "RSI 5 Period")
rsilimit5 = input(40, defval = 40, minval = 2, maxval = 50, title = "RSI 5 Limit")
cf = input(false, defval = false, title = "Use color filter")
fromyear = input(1900, defval = 1900, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From Day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To Day")

//RSI
rsi1 = rsi(close, rsiperiod1)
rsi2 = rsi(close, rsiperiod2)
rsi3 = rsi(close, rsiperiod3)
rsi4 = rsi(close, rsiperiod4)
rsi5 = rsi(close, rsiperiod5)

//Signals
up1 = rsi1 < rsilimit1 and usersi1
up2 = rsi2 < rsilimit2 and usersi2
up3 = rsi3 < rsilimit3 and usersi3
up4 = rsi4 < rsilimit4 and usersi4
up5 = rsi5 < rsilimit5 and usersi5

str = up5 ? 5 : up4 ? 4 : up3 ? 3 : up2 ? 2 : up1 ? 1 : str[1]
up = up1 or up2 or up3 or up4 or up5
exit = (rsi1 > rsilimit1 and str == 1) or (rsi2 > rsilimit2 and str == 2) or (rsi3 > rsilimit3 and str == 3) or (rsi4 > rsilimit4 and str == 4) or (rsi5 > rsilimit5 and str == 5)
lot = strategy.position_size == 0 ? strategy.equity / close * capital / 100 : lot[1]

//Background
col = up ? lime : na
bgcolor(col, transp = 0)

//Trading
if up and (close < open or cf == false)
    strategy.entry("Long", strategy.long, lot, when=(time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if time > timestamp(toyear, tomonth, today, 23, 59) or exit
    strategy.close_all()
Detail
https://www.fmz.com/strategy/433559
Last Modified
2023-11-28 15:03:53