
10 KiB
Name
个性化动量交易策略Personalized-Momentum-Trading-Strategy
Author
ChaoZhang
Strategy Description
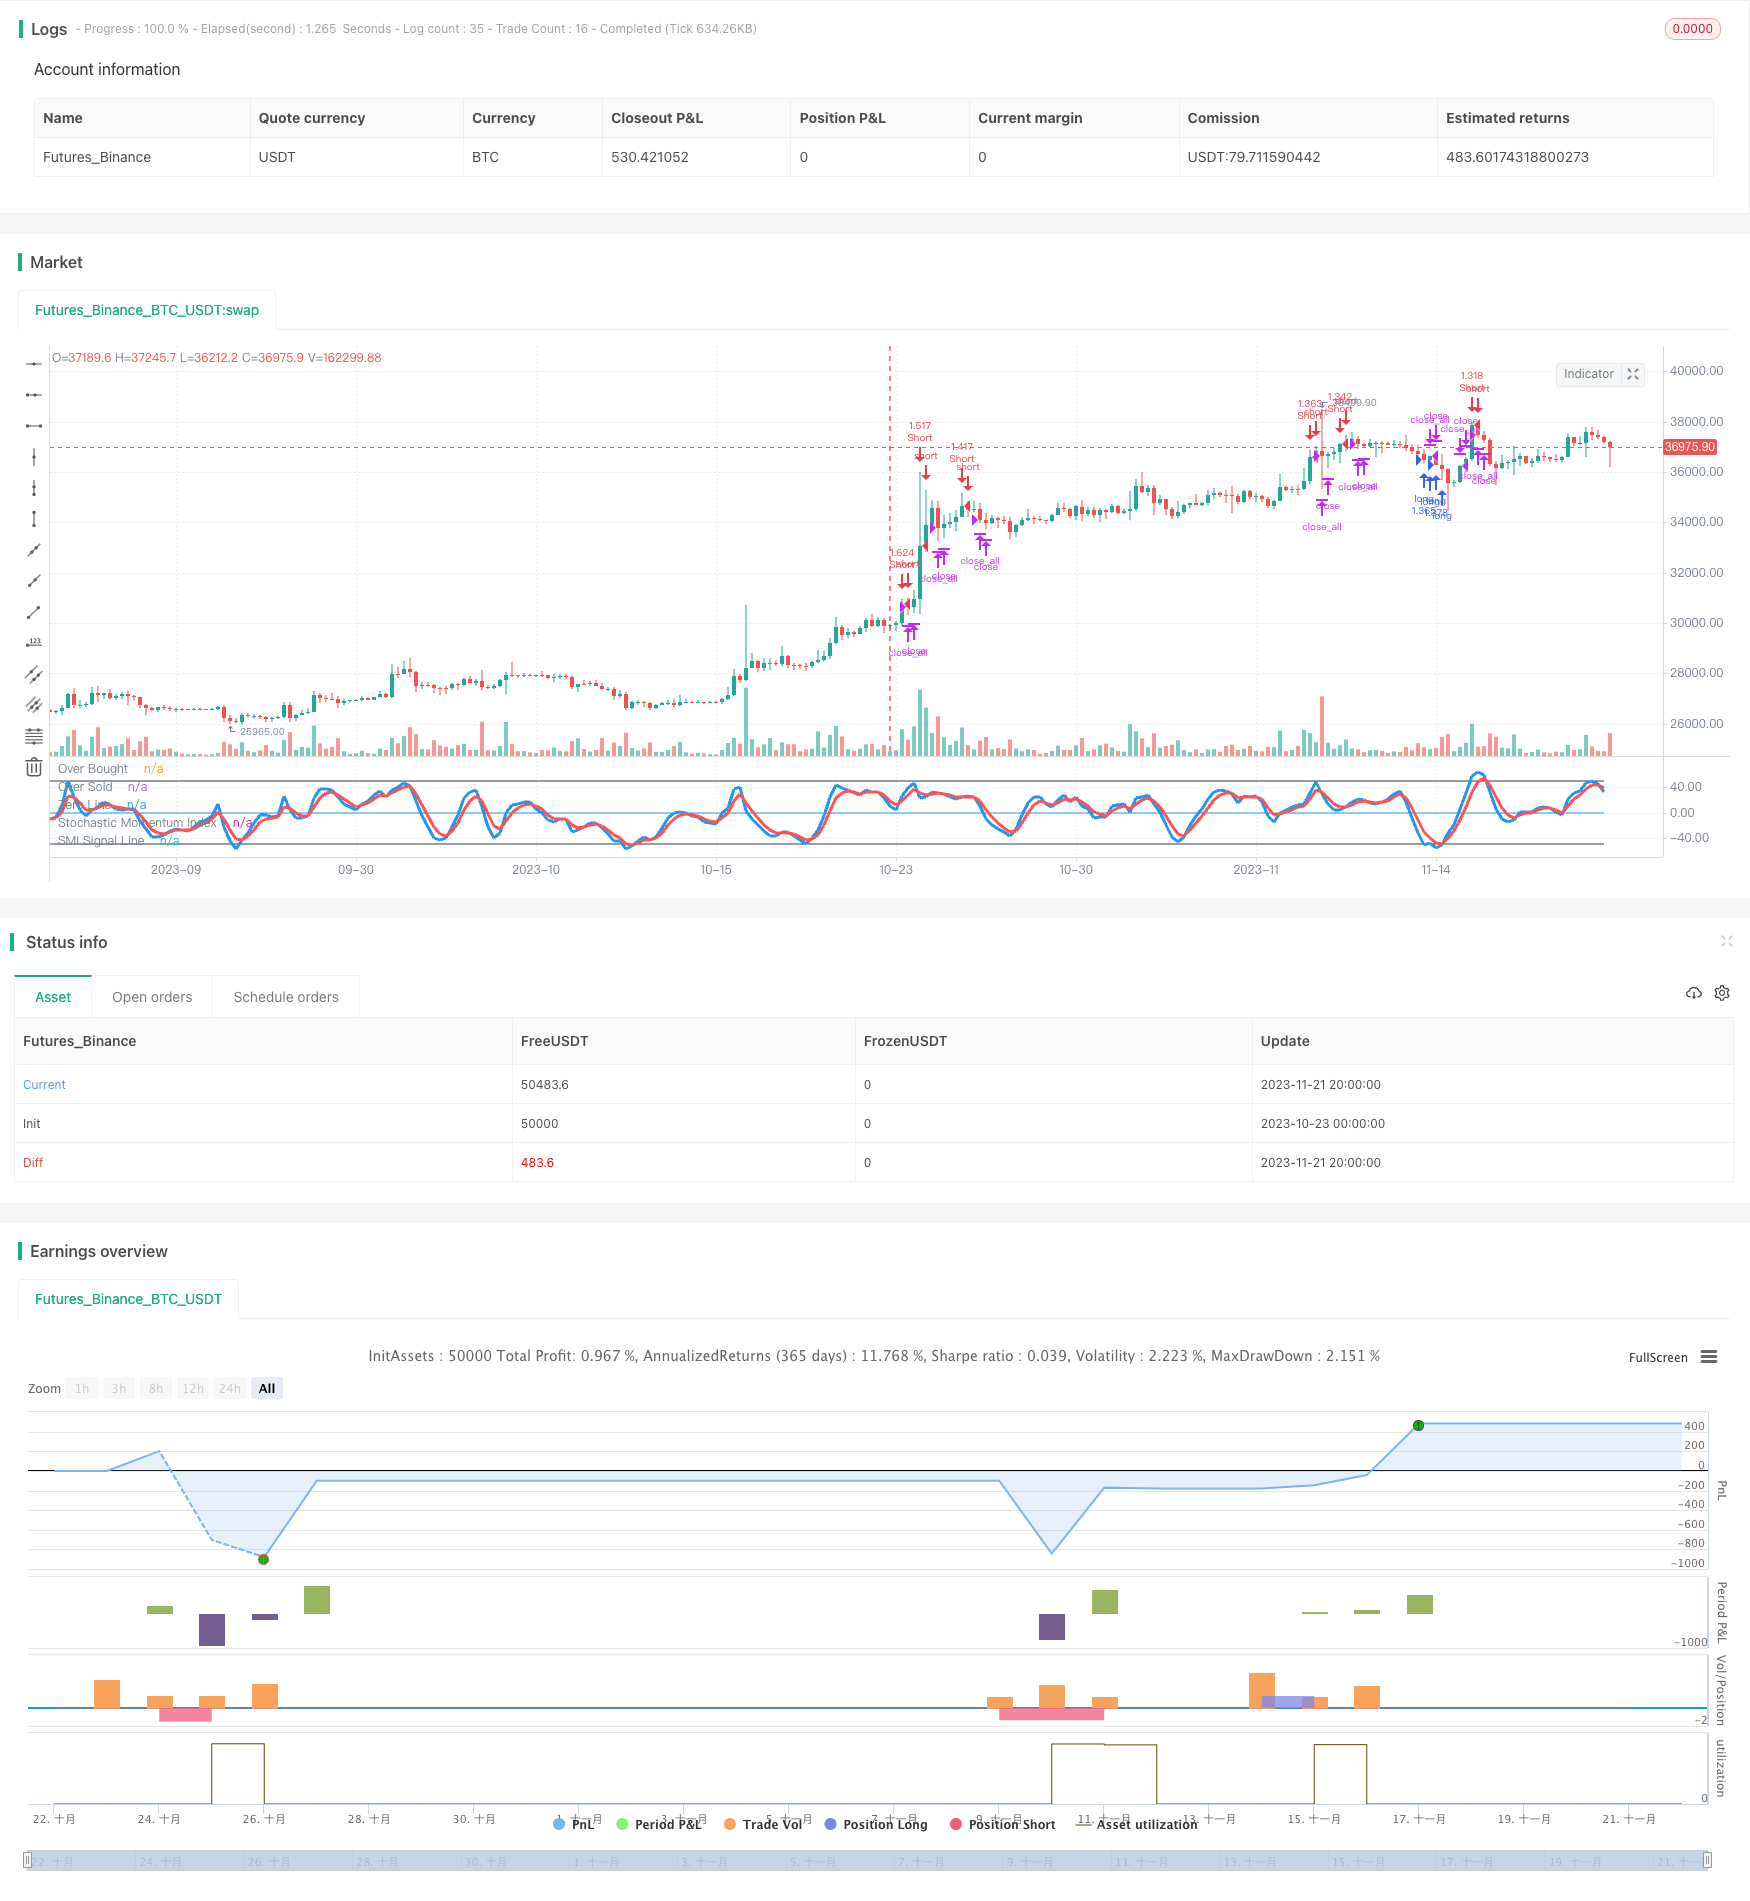
[trans]
概述
这是一个结合了动量指标和K线实体过滤的个性化交易策略。它综合运用了随机动量指数、快速RSI和K线实体过滤三种技术指标,实现了一个动量突破为主,同时考虑超买超卖的策略。
策略原理
本策略使用以下三个指标进行交易信号判断:
-
随机动量指数(SMI):它结合了K线实体间距和收盘价的相对位置,判断价格动能强弱。当SMI上穿过界线时产生买入信号,下穿界线时产生卖出信号。
-
快速RSI(7日线):它判断了价格的超买超卖状况。RSI低于20时为超卖产生买入信号,高于80时为超买产生卖出信号。
-
K线实体过滤:计算10日内的平均K线实体大小,当今日K线实体超过该平均值的三分之一时有效,避免无效信号。
本策略首先判断SMI和RSI的信号,如果符合其中一个indicator的信号要求,再结合K线实体过滤判定该信号是否有效,如果有效则产生交易信号。
优势分析
本策略具有以下优势:
-
多个指标结合,判断更精确可靠。
-
增加K线实体过滤,避免无效信号。
-
结合超买超卖判断,在趋势反转点更容易捕捉信号。
-
多空两个方向交易,收益机会增加。
-
采用部分交易仓位,避免单次交易过度损失。
风险分析
本策略也存在一些风险:
-
指标作用下,容易产生误信号导致亏损。可通过参数优化减少误信号。
-
部分仓位交易无法充分利用每个方向的趋势机会。可通过放大交易仓位获得更高收益。
-
SMI作为主指标,对参数设置敏感,不当设置可能错过交易机会或增加误信号。
-
多空双向交易,操作频繁,交易成本增加。
优化方向
本策略可从以下几个方向进行进一步优化:
-
优化SMI和RSI的参数,找到最佳参数组合。
-
增加仓位放大和仓位管理机制,在趋势中获得更高收益。
-
增加止损策略,降低单次亏损风险。
-
结合更多indicator判断信号可靠性,减少误信号。
-
采用高效合约,降低交易成本。
总结
本策略综合运用了SMI、快速RSI和K线实体过滤三种技术指标,实现了一个动量为主,兼顾超买超卖的个性化交易策略。它具有判断精确、识别有效信号、结合超买超卖和多空交易等优势,也存在一些参数敏感性、不能充分利用趋势、操作频繁等风险。通过持续优化参数设置、增加仓位和止损管理、减少误信号等方法,本策略可以获得更好的交易效果。 ||
Overview
This is a personalized trading strategy that combines momentum indicators and candlestick entity filtering. It comprehensively uses three technical indicators - Stochastic Momentum Index, fast RSI and candlestick entity filtering to implement a momentum breakthrough-based strategy while also considering overbought and oversold conditions.
Trading Logic
The strategy uses the following three indicators for trading signal judgment:
-
Stochastic Momentum Index (SMI): It combines the spacing between candlestick entities and the relative position of the closing price to judge the strength or weakness of price momentum. It generates a buy signal when SMI crosses above the boundary line and a sell signal when crossing below the boundary line.
-
Fast RSI (7-day line): It judges the overbought and oversold conditions of prices. RSI below 20 generates a buy signal as oversold while above 80 generates a sell signal as overbought.
-
Candlestick Entity Filter: Calculate the average candlestick entity size over the past 10 days. Only enable the signal when today's candlestick entity exceeds one-third of that average to avoid invalid signals.
The strategy first judges the signals from SMI and RSI. If either indicator signal requirement is met, then combine the candlestick entity filter to determine if that signal is valid and generate a trading signal if valid.
Advantage Analysis
The strategy has the following advantages:
-
Judgment is more precise and reliable with combination of multiple indicators.
-
Addition of candlestick entity filter avoids invalid signals.
-
By combining overbought/oversold conditions, it is easier to capture signals at trend reversal points.
-
Increased profit opportunities with dual-directional long/short trading.
-
Partial position trading avoids excessive single-time loss.
Risk Analysis
The strategy also has some risks:
-
Indicators can generate false signals leading to losses. Parameter optimization can reduce false signals.
-
Partial position trading cannot fully utilize the trend opportunities in each direction. Higher returns can be achieved by amplifying trading position size.
-
As the main indicator, SMI is sensitive to parameter settings. Improper configuration may miss trading opportunities or increase false signals.
-
Frequent trading with dual-directional strategy increases transaction costs.
Optimization Directions
The strategy can be further optimized in the following aspects:
-
Optimize parameters for SMI and RSI to find best parameter combinations.
-
Increase position sizing and position management mechanisms to achieve higher returns during trends.
-
Add stop loss strategies to reduce single-time loss risk.
-
Combine more indicators to judge signal reliability and reduce false signals.
-
Adopt efficient contracts to reduce transaction costs.
Conclusion
The strategy comprehensively utilizes the SMI, fast RSI and candlestick entity filtering indicators to implement a momentum-based, overbought/oversold-aware personalized trading strategy. It has advantages like precise judgment, identification of valid signals, combination of overbought/oversold conditions and dual-directional trading, but also risks like parameter sensitivity, inability to fully capitalize trends, and frequent operations. By continuously optimizing parameters, increasing position sizing and stop loss management, reducing false signals etc., the strategy can achieve better trading performance.
[/trans]
Strategy Arguments
| Argument | Default | Description |
|---|---|---|
| v_input_1 | true | Long |
| v_input_2 | true | Short |
| v_input_3 | false | Use Martingale |
| v_input_4 | 100 | Capital, % |
| v_input_5 | true | Use SMI Strategy |
| v_input_6 | true | Use RSI Strategy |
| v_input_7 | true | Use Body-Filter |
| v_input_8 | 5 | SMI Percent K Length |
| v_input_9 | 3 | SMI Percent D Length |
| v_input_10 | 50 | SMI Limit |
| v_input_11 | 2017 | From Year |
| v_input_12 | 2100 | To Year |
| v_input_13 | true | From Month |
| v_input_14 | 12 | To Month |
| v_input_15 | true | From day |
| v_input_16 | 31 | To day |
Source (PineScript)
/*backtest
start: 2023-10-23 00:00:00
end: 2023-11-22 00:00:00
period: 6h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Noro
//2018

//@version=2
strategy(title = "Noro's Stochastic Strategy v1.2", shorttitle = "Stochastic str 1.2", overlay = false, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 0)

//Settings
needlong = input(true, defval = true, title = "Long")
needshort = input(true, defval = true, title = "Short")
usemar = input(false, defval = false, title = "Use Martingale")
capital = input(100, defval = 100, minval = 1, maxval = 10000, title = "Capital, %")
usesmi = input(true, defval = true, title = "Use SMI Strategy")
usersi = input(true, defval = true, title = "Use RSI Strategy")
usebod = input(true, defval = true, title = "Use Body-Filter")
a = input(5, "SMI Percent K Length")
b = input(3, "SMI Percent D Length")
limit = input(50, defval = 50, minval = 1, maxval = 100, title = "SMI Limit")
fromyear = input(2017, defval = 2017, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To day")

//Fast RSI
fastup = rma(max(change(close), 0), 7)
fastdown = rma(-min(change(close), 0), 7)
fastrsi = fastdown == 0 ? 100 : fastup == 0 ? 0 : 100 - (100 / (1 + fastup / fastdown))

//Stochastic Momentum Index
ll = lowest (low, a)
hh = highest (high, a)
diff = hh - ll
rdiff = close - (hh+ll)/2
avgrel = ema(ema(rdiff,b),b)
avgdiff = ema(ema(diff,b),b)
SMI = avgdiff != 0 ? (avgrel/(avgdiff/2)*100) : 0
SMIsignal = ema(SMI,b)

//Lines
plot(SMI, color = blue, linewidth = 3, title = "Stochastic Momentum Index")
plot(SMIsignal, color = red, linewidth = 3, title = "SMI Signal Line")
plot(limit, color = black, title = "Over Bought")
plot(-1 * limit, color = black, title = "Over Sold")
plot(0, color = blue, title = "Zero Line")

//Body Filter
nbody = abs(close - open)
abody = sma(nbody, 10)
body = nbody > abody / 3 or usebod == false

//Signals
up1 = SMI < -1 * limit and close < open and body and usesmi
dn1 = SMI > limit and close > open and body and usesmi
up2 = fastrsi < 20 and close < open and body and usersi
dn2 = fastrsi > 80 and close > open and body and usersi
exit = ((strategy.position_size > 0 and close > open) or (strategy.position_size < 0 and close < open)) and body

//Trading
profit = exit ? ((strategy.position_size > 0 and close > strategy.position_avg_price) or (strategy.position_size < 0 and close < strategy.position_avg_price)) ? 1 : -1 : profit[1]
mult = usemar ? exit ? profit == -1 ? mult[1] * 2 : 1 : mult[1] : 1
lot = strategy.position_size == 0 ? strategy.equity / close * capital / 100 * mult : lot[1]

if up1 or up2
    if strategy.position_size < 0
        strategy.close_all()

    strategy.entry("long", strategy.long, needlong == false ? 0 : lot, when=(time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if dn1 or dn2
    if strategy.position_size > 0
        strategy.close_all()

    strategy.entry("Short", strategy.short, needshort == false ? 0 : lot, when=(time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if time > timestamp(toyear, tomonth, today, 23, 59) or exit
    strategy.close_all()
Detail
https://www.fmz.com/strategy/433007
Last Modified
2023-11-23 15:18:27