
10 KiB
Name
移动平均线指标交易策略Multi-Moving-Average-Crossover-Trading-Strategy
Author
ChaoZhang
Strategy Description
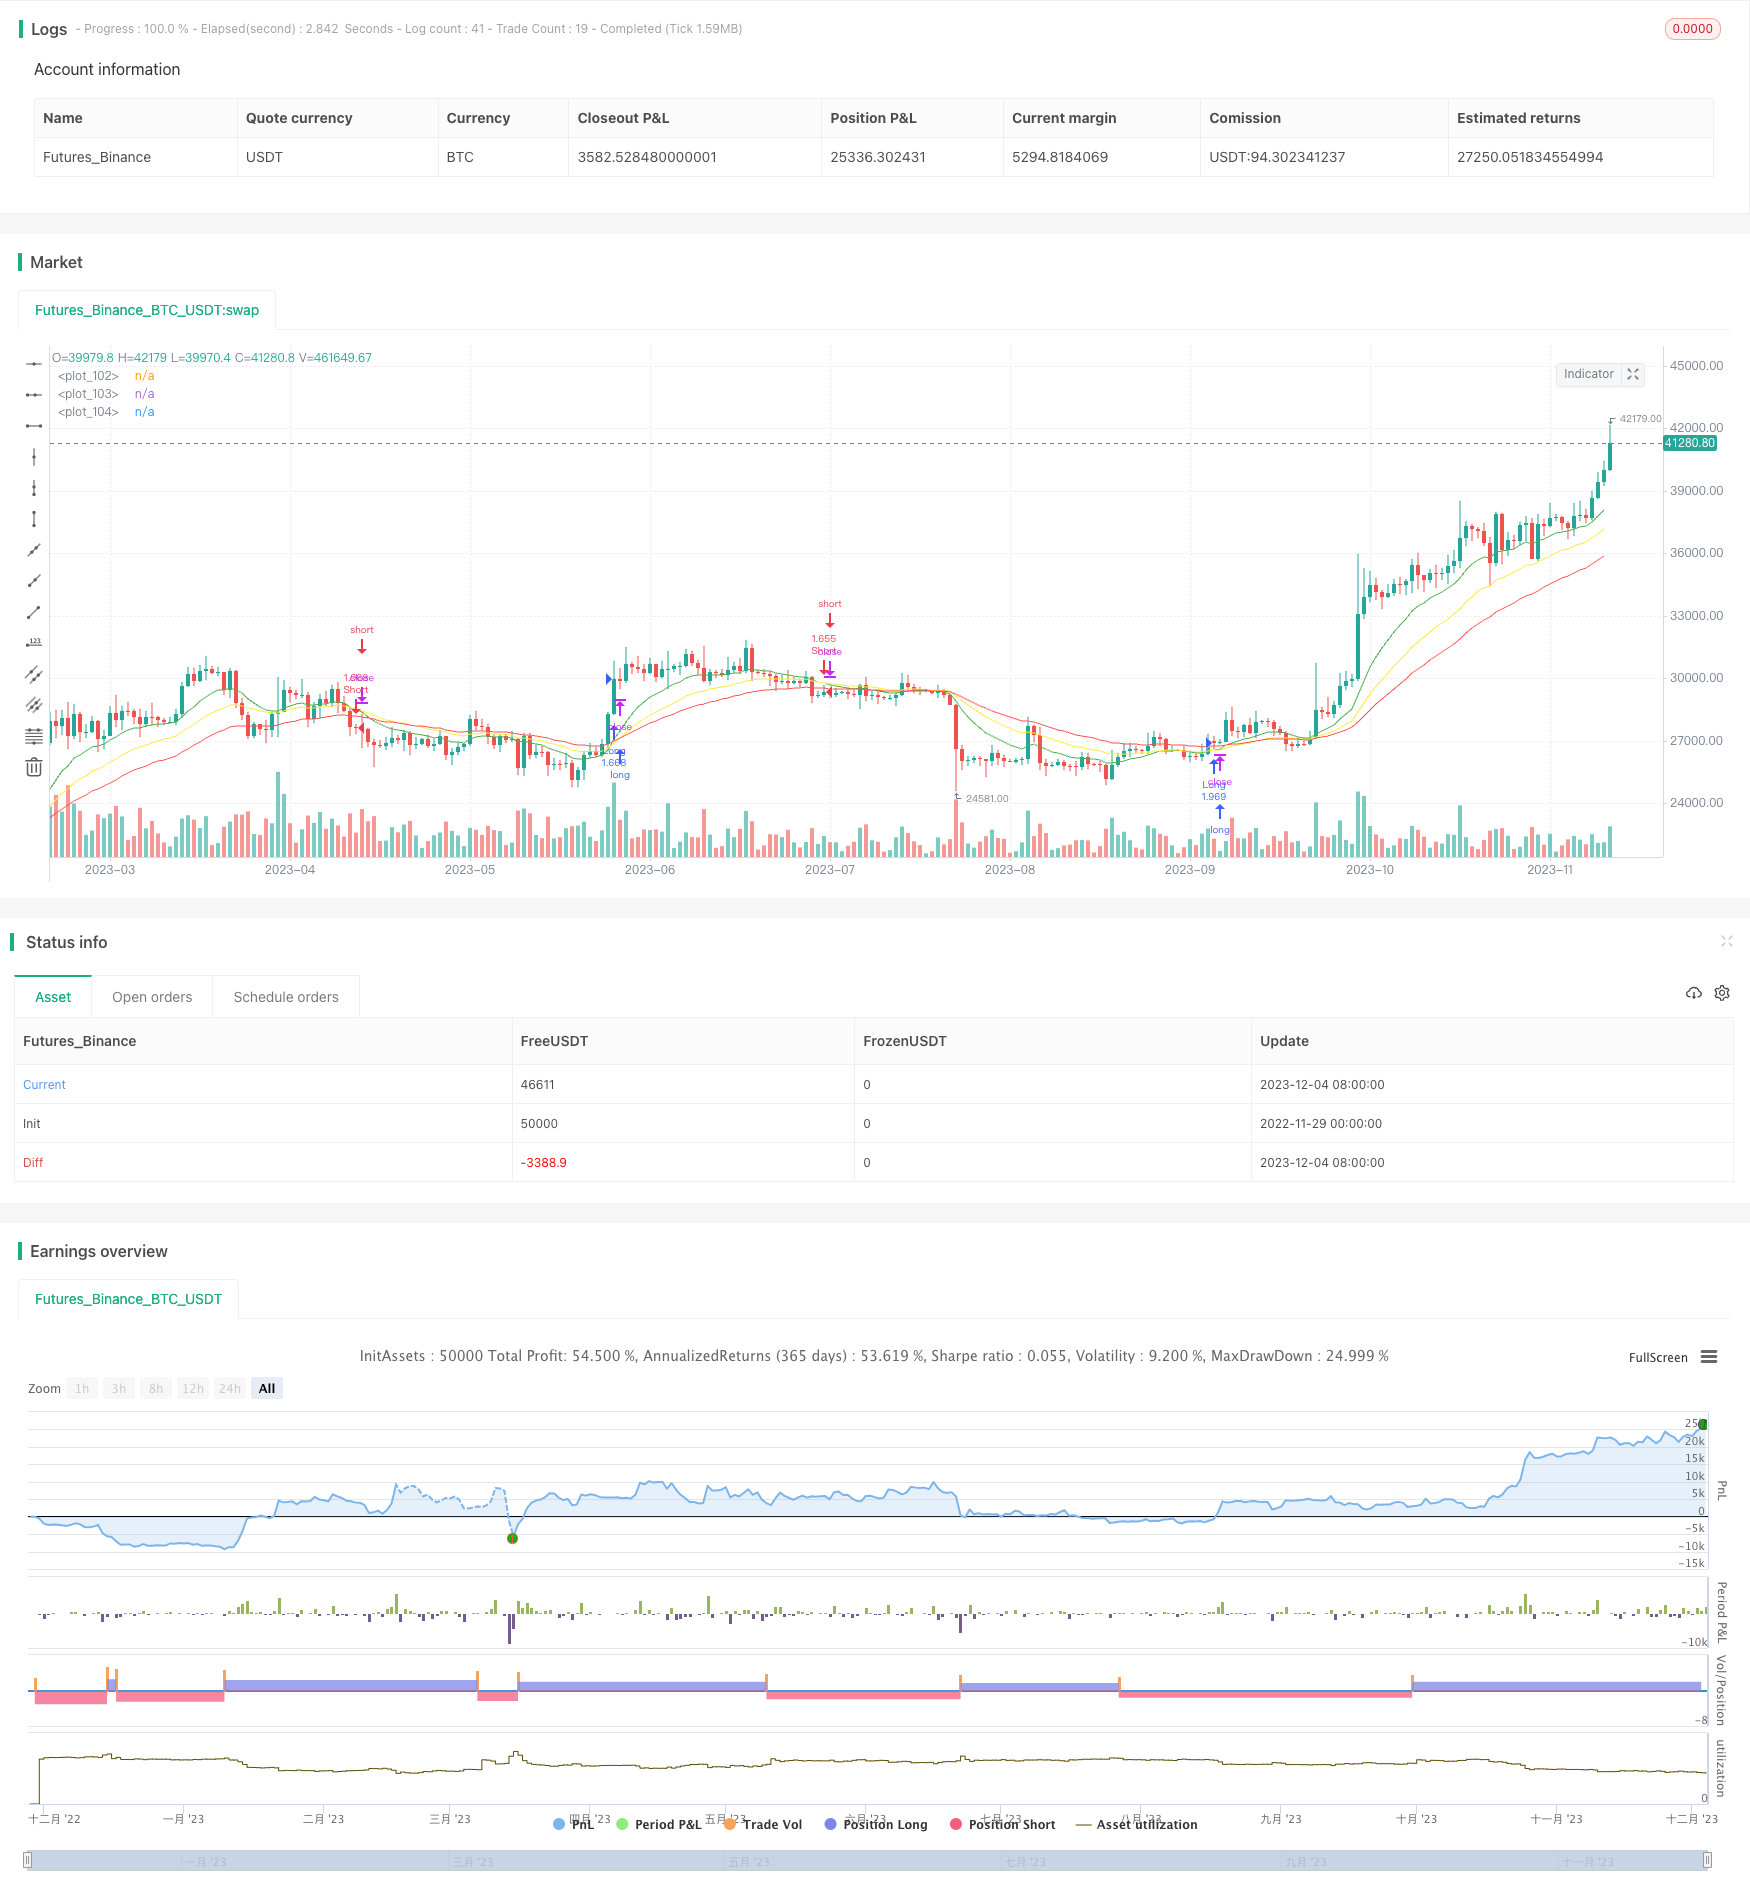 [trans]
策略概述
该策略是基于多个移动平均线指标来产生交易信号的策略。策略会同时关注短期、中期和长期移动平均线,根据它们的交叉情况来判断趋势方向并产生交易信号。
策略名称
多重均线交叉策略(Multi Moving Average Crossover Strategy)
策略原理
该策略同时使用 3 条不同周期的移动平均线,包括 7 日线、13 日线和 21 日线。其交易逻辑基于以下几点:
- 当短期 7 日线上穿中期 13 日线,长期 21 日线处于上升趋势时,产生做多信号;
- 当短期 7 日线下穿中期 13 日线,长期 21 日线处于下降趋势时,产生做空信号。
通过结合不同时间段的移动平均线,可以更准确判断市场趋势,避免错误交易。
策略优势
- 使用多组移动平均线,可以更准确判断市场走势,避免被市场中的假突破或短期波动误导。
- 只在趋势明确时才产生信号,可以减少不必要的交易次数,从而降低交易成本。
- 参数设置灵活,可以根据个人偏好调整移动平均线的周期,适应不同品种和市场环境。
策略风险
- 在震荡调整的市场中,可能出现频繁的错误信号。
- 移动平均线作为趋势跟随指标,无法准确定位转折点。
- 移动平均线交叉延迟识别趋势,可能错过部分利润。
- 可通过引入其他技术指标验证信号,优化移动平均线参数来降低风险。
策略优化方向
- 考虑引入波动率指标,判断趋势强度,避免在震荡市场中交易。
- 尝试运用机器学习等定量技术自动优化移动平均线参数。
- 增加止损策略,在亏损扩大时及时止损。
- 考虑在移动平均线交叉时,利用限价单减少滑点。
总结
该策略结合短中长三个时间段的移动平均线,根据它们的交叉关系判断市场趋势,是一个相对稳定和高效的趋势跟随策略。通过对指标参数、止损机制以及下单方式的优化,可以进一步提高策略的胜率和盈利能力。
||
Strategy Overview
This strategy generates trading signals based on multiple moving average indicators. It monitors short-term, medium-term and long-term moving averages simultaneously, and generates trading signals according to their crossover situations to determine trend direction.
Strategy Name
Multi Moving Average Crossover Strategy
Strategy Logic
This strategy employs 3 moving averages with different periods, including 7-day, 13-day and 21-day lines. The trading logic is based on the following points:
- When the short-term 7-day MA crosses over the medium-term 13-day MA upwards, while the long-term 21-day MA is in an upward trend, a long signal is generated.
- When the short-term 7-day MA crosses below the medium-term 13-day MA downwards, while the long-term 21-day MA is in a downward trend, a short signal is generated.
By combining moving averages across different timeframes, the strategy can judge market trends more precisely and avoid false trades.
Advantages
- Using multiple MA lines can better determine market moves and avoid being misguided by false breakouts or short-term fluctuations in the market.
- Signals are only generated when the trend is clear, thus reducing unnecessary trades and lowering transaction costs.
- Flexible parameter settings - the periods of the MAs can be adjusted based on personal preference to suit different products and market environments.
Risks
- Frequent false signals may occur in a ranging, choppy market.
- MAs as trend-following indicators cannot accurately locate turning points.
- Delayed signal by MA crossovers may miss part of the profits.
- Risks can be reduced by introducing other technical indicators for signal validation and optimizing MA parameters.
Optimization Directions
- Consider incorporating volatility indicators to gauge trend strength and avoid trading in choppy markets.
- Try applying machine learning models to auto-optimize MA parameters.
- Add stop loss strategies to cut losses in time when drawdowns expand.
- Use limit orders when MA crossover happens to reduce slippage.
Conclusion
This strategy combines short-term, medium-term and long-term MAs to determine market trend based on their crossover relations, making it a relatively stable and efficient trend-following strategy. Further improvements in indicator parameters, stop loss mechanisms and order placement can help increase win rate and profitability. [/trans]
Strategy Arguments
| Argument | Default | Description |
|---|---|---|
| v_input_1 | true | From Day |
| v_input_2 | true | From Month |
| v_input_3 | 2015 | From Year |
| v_input_4 | true | To Day |
| v_input_5 | true | To Month |
| v_input_6 | 2030 | To Year |
| v_input_7 | false | Signals from Heikin Ashi Candles |
| v_input_8 | 0 | MA Type: SMMA |
| v_input_9_ohlc4 | 0 | src: ohlc4 |
| v_input_10 | 7 | Short MA Length |
| v_input_11 | 13 | Middle MA Length |
| v_input_12 | 21 | Long MA Length |
Source (PineScript)
/*backtest
start: 2022-11-29 00:00:00
end: 2023-12-05 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Crypto-Oli

//@version=4
strategy("CryptOli 3 MAs long/short Backtest", initial_capital=5000, default_qty_type=strategy.percent_of_equity, default_qty_value=100, overlay=true)

// this is an educational Script - basicly its very simple - you can see how minimal changes impact results, thats why i posted it
// Credits to Quantnomad to publish tons of free educational script
// this Script is based on https://www.tradingview.com/script/0NgUadGr-Ultimate-MA-Cross-Indicator/ Quantnomads Ultimate MA Indicator
// HA - Option for calcucaltion based on HA-Candles (very famous recently)
// Source Input - Option (Candletype for calculation, close, ohlc4 ect.) --- there are huge differences --- try it by your own

////////////////////////////////////////////////////////////////////////////////
// BACKTESTING RANGE

// From Date Inputs
fromDay = input(defval=1, title="From Day", minval=1, maxval=31)
fromMonth = input(defval=1, title="From Month", minval=1, maxval=12)
fromYear = input(defval=2015, title="From Year", minval=1970)

// To Date Inputs
toDay = input(defval=1, title="To Day", minval=1, maxval=31)
toMonth = input(defval=1, title="To Month", minval=1, maxval=12)
toYear = input(defval=2030, title="To Year", minval=1970)

// Calculate start/end date and time condition
startDate = timestamp(fromYear, fromMonth, fromDay, 00, 00)
finishDate = timestamp(toYear, toMonth, toDay, 00, 00)
time_cond = time >= startDate and time <= finishDate

////////////////////////////////////////////////////////////////////////////////

h = input(false, title = "Signals from Heikin Ashi Candles")

ma_type      = input(title = "MA Type",         type = input.string,  defval = "SMMA", options = ['SMA', 'EMA', 'WMA', 'VWMA', 'HMA', 'SMMA', 'DEMA'])
src = input(ohlc4)

short_ma_len = input(title = "Short MA Length", type = input.integer, defval = 7,     minval = 1)
short_ma_src = h ? security(heikinashi(syminfo.tickerid), timeframe.period, src, lookahead = false) : close
middle_ma_len  = input(title = "Middle MA Length",  type = input.integer, defval = 13,    minval = 2)
middle_ma_src = h ? security(heikinashi(syminfo.tickerid), timeframe.period, src, lookahead = false) : close
long_ma_len  = input(title = "Long MA Length",  type = input.integer, defval = 21,    minval = 2)
long_ma_src = h ? security(heikinashi(syminfo.tickerid), timeframe.period, src, lookahead = false) : close


tick_round(x) =>
    round(x / syminfo.mintick) * syminfo.mintick

// Set initial values to 0
short_ma = 0.0
middle_ma = 0.0
long_ma  = 0.0

// Simple Moving Average (SMA)
if ma_type == 'SMA'
    short_ma := sma(short_ma_src, short_ma_len)
    middle_ma := sma(middle_ma_src, middle_ma_len)
    long_ma  := sma(long_ma_src,  long_ma_len)

// Exponential Moving Average (EMA)
if ma_type == 'EMA'
    short_ma := ema(short_ma_src, short_ma_len)
    middle_ma := ema(middle_ma_src, middle_ma_len)
    long_ma  := ema(long_ma_src,  long_ma_len)

// Weighted Moving Average (WMA)
if ma_type == 'WMA'
    short_ma := wma(short_ma_src, short_ma_len)
    middle_ma := wma(middle_ma_src, middle_ma_len)
    long_ma  := wma(long_ma_src,  long_ma_len)

// Hull Moving Average (HMA)
if ma_type == 'HMA'
    short_ma := wma(2*wma(short_ma_src, short_ma_len/2)-wma(short_ma_src, short_ma_len), round(sqrt(short_ma_len)))
    middle_ma := wma(2*wma(middle_ma_src, middle_ma_len/2)-wma(middle_ma_src, middle_ma_len), round(sqrt(middle_ma_len)))
    long_ma  := wma(2*wma(long_ma_src,  long_ma_len /2)-wma(long_ma_src,  long_ma_len),  round(sqrt(long_ma_len)))

// Volume-weighted Moving Average (VWMA)
if ma_type == 'VWMA'
    short_ma := vwma(short_ma_src, short_ma_len)
    middle_ma := vwma(middle_ma_src, middle_ma_len)
    long_ma  := vwma(long_ma_src,  long_ma_len)


// Smoothed Moving Average (SMMA)
if ma_type == 'SMMA'
    short_ma := na(short_ma[1]) ? sma(short_ma_src, short_ma_len) : (short_ma[1] * (short_ma_len - 1) + short_ma_src) / short_ma_len
    middle_ma := na(middle_ma[1]) ? sma(middle_ma_src, middle_ma_len) : (middle_ma[1] * (middle_ma_len - 1) + middle_ma_src) / middle_ma_len
    long_ma  := na(long_ma[1])  ? sma(long_ma_src,  long_ma_len)  : (long_ma[1]  * (long_ma_len  - 1) + long_ma_src)  / long_ma_len

// Double Exponential Moving Average (DEMA)
if ma_type == 'DEMA'
    e1_short = ema(short_ma_src, short_ma_len)
    e1_middle = ema(middle_ma_src, middle_ma_len)
    e1_long  = ema(long_ma_src,  long_ma_len)

    short_ma := 2 * e1_short - ema(e1_short, short_ma_len)
    middle_ma := 2 * e1_middle - ema(e1_middle, middle_ma_len)
    long_ma  := 2 * e1_long  - ema(e1_long,  long_ma_len)

// Plot MAs
plot(short_ma, color = color.green,   linewidth = 1)
plot(middle_ma, color = color.yellow,   linewidth = 1)
plot(long_ma,  color = color.red, linewidth = 1)

if close>long_ma and short_ma>middle_ma and time_cond
    strategy.entry("Long", strategy.long)


if close<long_ma and short_ma<middle_ma and time_cond
    strategy.entry("Short", strategy.short)
Detail
https://www.fmz.com/strategy/434478
Last Modified
2023-12-06 17:10:00