
8.8 KiB
Name
双线追踪反转均线系统Dual-Moving-Average-Reversal-Tracking-System
Author
ChaoZhang
Strategy Description
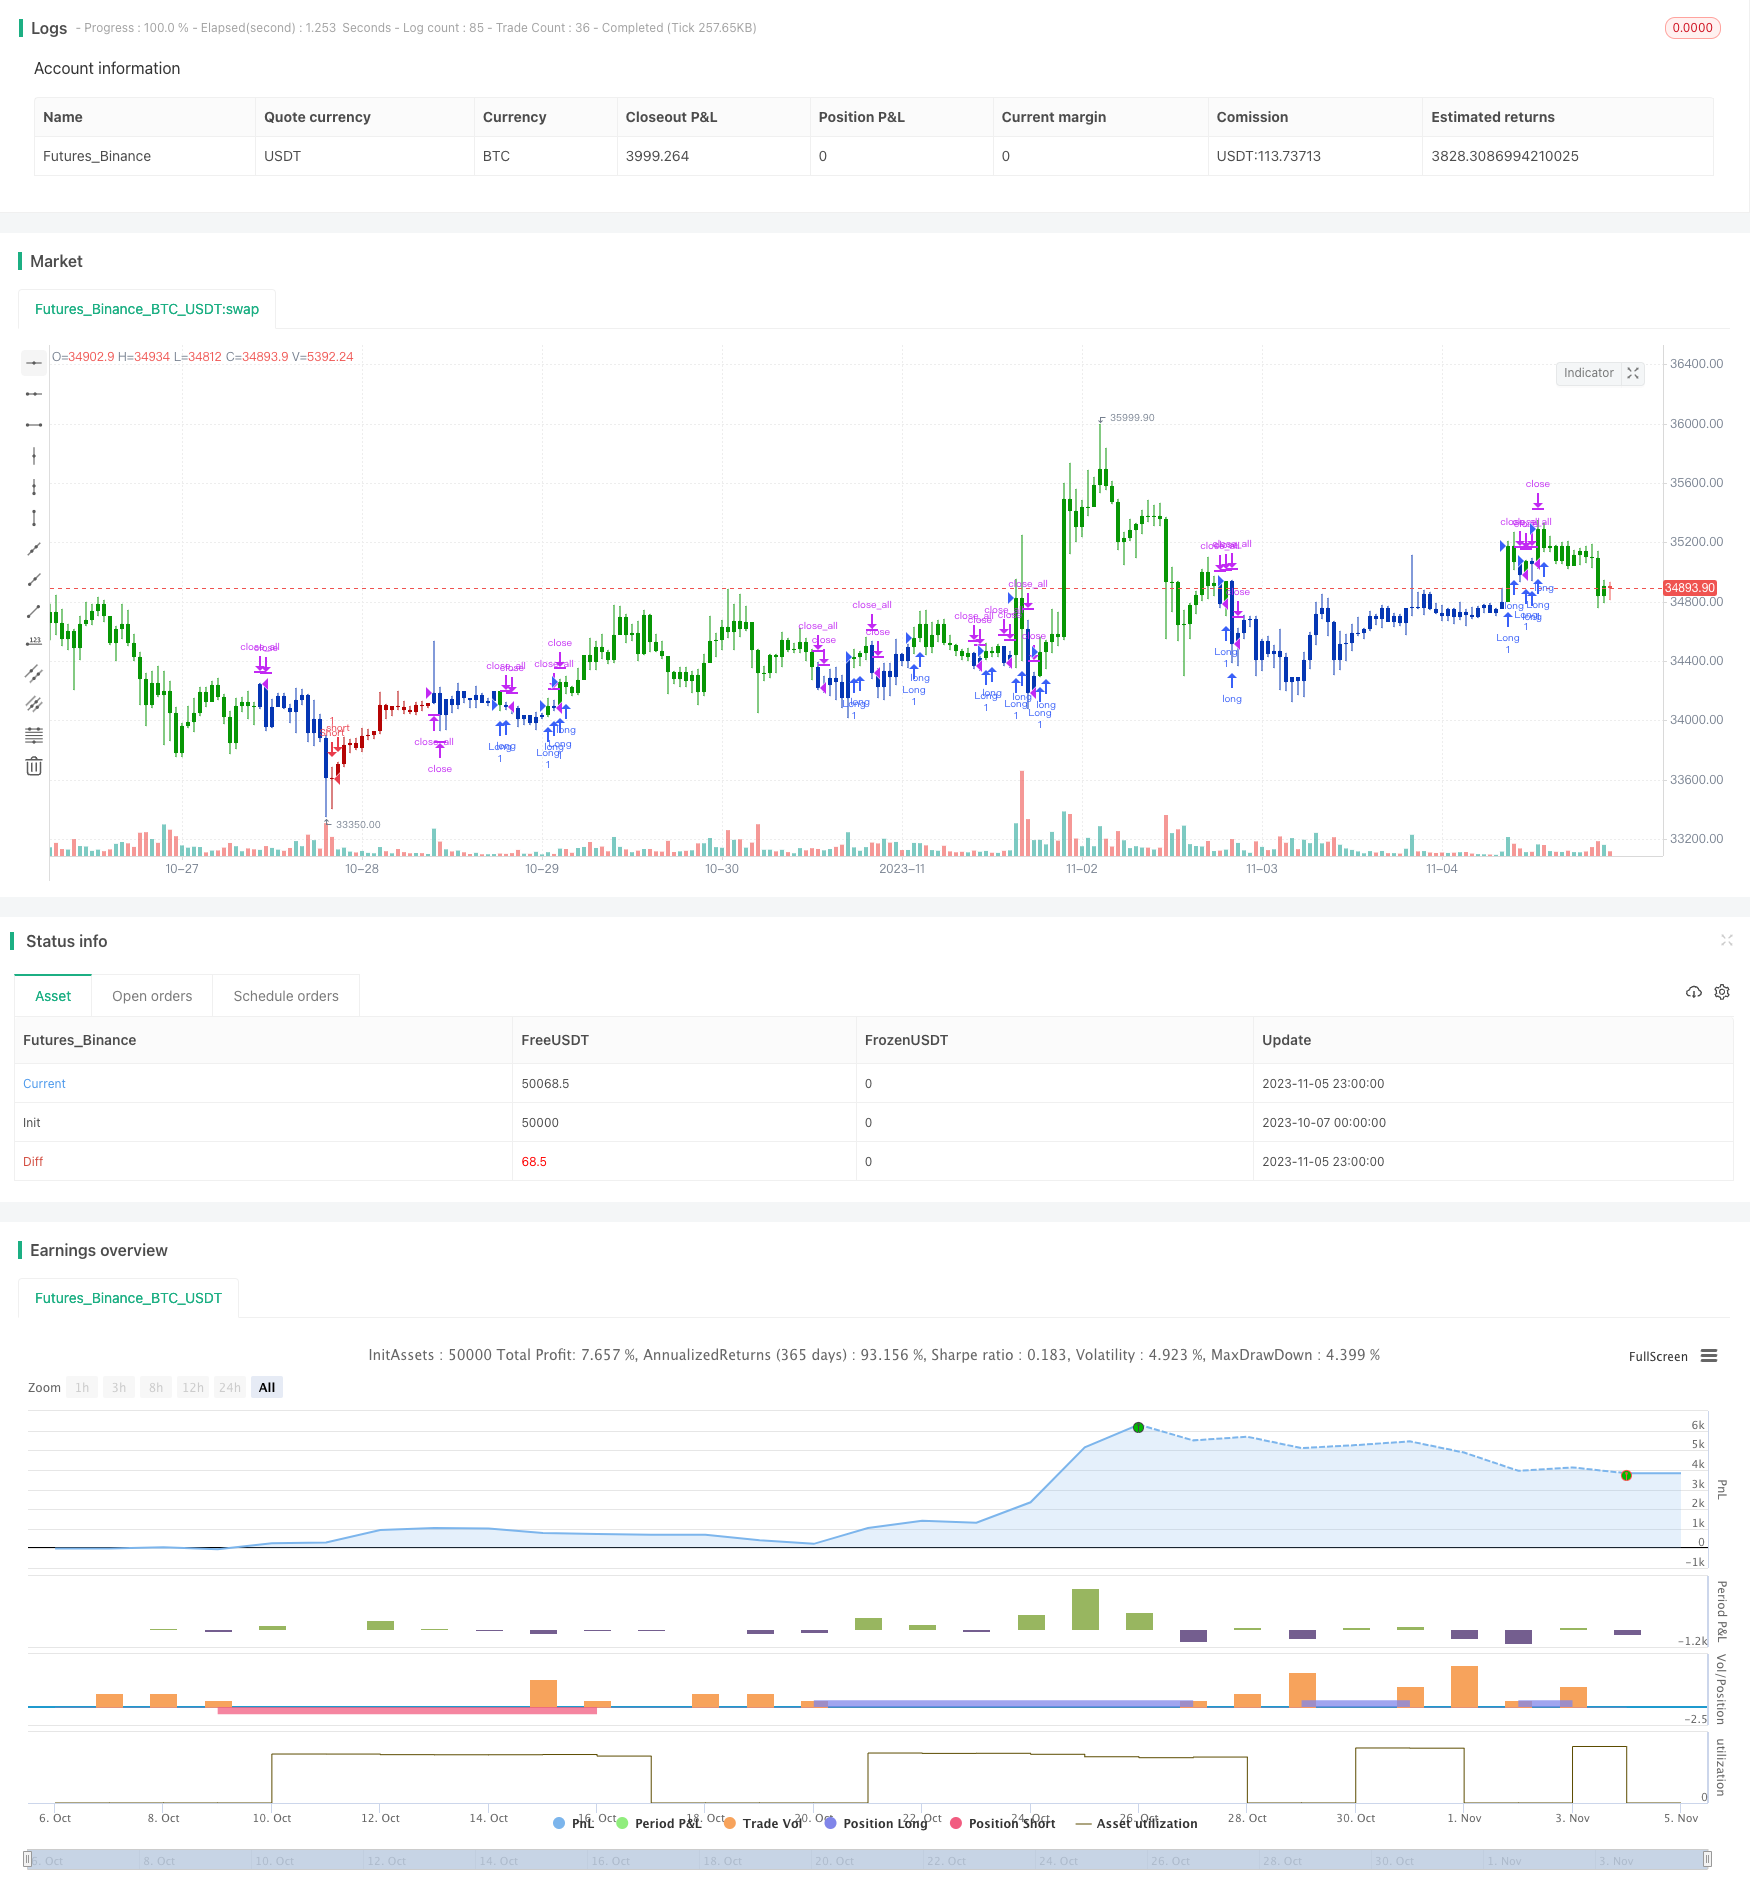 [trans]
概述
双线追踪反转均线系统融合了123形态反转策略和一目均衡表策略,旨在发掘反转机会,追踪趋势,以获取超额收益。
策略原理
该策略由两个子策略组成:
- 123形态反转策略
该策略基于价格形态进行交易。具体逻辑是:
- 当收盘价连续两日上涨,且9日慢速K线低于50时,做多
- 当收盘价连续两日下跌,且9日快速K线高于50时,做空
该策略利用价格突破上一日收盘价的方式判断反转,并利用股票K线组合指标滤除震荡盘整。
- 一目均衡表策略
该策略基于一目均衡表的五线交叉进行交易。具体逻辑是:
- 当收盘价高于基准线时做多
- 当收盘价低于转换线时做空
其中,基准线为过去26日的最高价和最低价的中点,转换线为过去9日的最高价和最低价的中点。该策略利用均线交叉系统发掘趋势。
最终策略根据两个子策略的信号进行合并,当两者同向看多或看空时开仓,不同向时平仓。
优势分析
- 结合反转和趋势,既可捕捉反转机会,也可跟踪趋势,策略灵活。
- 123形态简单实用,可有效识别临界反转点。
- 一目均衡表参数经过优化,突破风险小。
- 两种不同类型策略合并,可实现策略优化。
风险分析
- 反转策略容易被陷阱,存在亏损风险。可适当缩短交易周期,或增加止损来控制风险。
- 一目均衡表在震荡行情中容易被套,可适当调整参数或增加过滤条件以减少不必要交易。
- 两种策略合并时,参数匹配不当可能导致信号过于频繁或稀疏,需要仔细测试优化。
优化方向
- 测试更多指标组合,寻找更好的过滤手段。例如结合量能指标等。
- 优化一目均衡表的参数,使之更契合具体产品特性。
- 增加止损机制。可以根据ATR来设定持仓止损。
- 增加money management模块,实现风险控制。
- 在回测中收集更多数据,对策略展开多方位测试,发现问题并不断优化。
总结
双线追踪反转均线系统综合运用反转和趋势策略的优点,通过参数优化和策略合并实现超额收益。该策略有一定的交易优势,但也存在被套和止损风险。我们需要在回测中持续优化策略逻辑,并辅以严格的风险管理措施,以提高策略的稳定性和实盘表现。总体来说,该策略为我们提供了一个不错的思路,即用不同类型策略进行组合,以获得更优的整体效果。
||
Overview
The Dual Moving Average Reversal Tracking System integrates the 123 reversal pattern strategy and the Ichimoku strategy to identify reversal opportunities and track trends for excess returns.
Strategy Logic
The strategy consists of two sub-strategies:
- 123 Reversal Pattern Strategy
This strategy trades based on price patterns. The logic is:
-
Go long when the close price rises for two consecutive days and the 9-day slow stochastic is below 50.
-
Go short when the close price falls for two consecutive days and the 9-day fast stochastic is above 50.
It uses the breakout of previous day's close to determine reversals and uses stochastics to filter noise.
- Ichimoku Strategy
This strategy trades based on the five lines crossover of Ichimoku. The logic is:
-
Go long when close price is above the baseline.
-
Go short when close price is below the conversion line.
Where the baseline is the midpoint of the highest high and lowest low over the past 26 days, and the conversion line is the midpoint of the highest high and lowest low over the past 9 days. It uses moving average crossovers to identify trends.
The final strategy combines the signals from the two sub-strategies, entering when both signal long or short and exiting when they disagree.
Advantage Analysis
-
Combines reversal and trend-following, flexible in catching reversals and trends.
-
123 pattern is simple and effective in identifying reversals.
-
Ichimoku parameters are optimized, with lower breakout risk.
-
Combining two different strategies can achieve optimization.
Risk Analysis
-
Reversal strategies are prone to traps and losses. Consider shorter holding periods or add stop loss to control risks.
-
Ichimoku can experience whipsaws in range-bound markets. Fine-tune parameters or add filters to reduce unnecessary trades.
-
Incompatible parameters when combining strategies may lead to too frequent or sparse signals. Require careful testing and optimization.
Optimization Directions
-
Test more indicators for better filters, e.g. incorporating volume.
-
Optimize Ichimoku parameters to fit instrument characteristics.
-
Add stop loss mechanisms, e.g. set exits based on ATR.
-
Add money management module for risk control.
-
Collect more data for robust backtesting, discover issues and iterate.
Conclusion
The Dual Moving Average Reversal Tracking System combines the strengths of reversal and trend-following strategies through optimization and combination for alpha generation. It has trading merits but risks like whipsaws and stop loss exist. We need to keep improving the logic in backtests and implement proper risk control for stability and real-world performance. Overall it provides a good approach of combining different strategies for better overall results.
[/trans]
Strategy Arguments
| Argument | Default | Description |
|---|---|---|
| v_input_1 | 14 | Length |
| v_input_2 | true | KSmoothing |
| v_input_3 | 3 | DLength |
| v_input_4 | 50 | Level |
| v_input_5 | 9 | conversionPeriods |
| v_input_6 | 26 | basePeriods |
| v_input_7 | 52 | laggingSpan2Periods |
| v_input_8 | 26 | displacement |
| v_input_9 | false | Trade reverse |
Source (PineScript)
/*backtest
start: 2023-10-07 00:00:00
end: 2023-11-06 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 26/11/2020
// This is combo strategies for get a cumulative signal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Second strategy
//  Ichimoku Strategy
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos

middleDonchian(Length) =>
    lower = lowest(Length)
    upper = highest(Length)
    avg(upper, lower)

Ichimoku2c(conversionPeriods, basePeriods,laggingSpan2Periods,displacement) =>
    pos = 0.0
    Tenkan = middleDonchian(conversionPeriods)
    Kijun =  middleDonchian(basePeriods)
    xChikou = close
    SenkouA = middleDonchian(laggingSpan2Periods)
    SenkouB = (Tenkan[basePeriods] + Kijun[basePeriods]) / 2
    pos := iff(close < SenkouA[displacement], -1,
              iff(close > SenkouB, 1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal & Ichimoku2c", shorttitle="Combo", overlay = true)
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
//-------------------------
conversionPeriods = input(9, minval=1),
basePeriods = input(26, minval=1)
laggingSpan2Periods = input(52, minval=1),
displacement = input(26, minval=1)
reverse = input(false, title="Trade reverse")
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posIchimoku2c = Ichimoku2c(conversionPeriods, basePeriods,laggingSpan2Periods,displacement)
pos = iff(posReversal123 == 1 and posIchimoku2c == 1 , 1,
	   iff(posReversal123 == -1 and posIchimoku2c == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1 , 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? #b50404: possig == 1 ? #079605 : #0536b3 )
Detail
https://www.fmz.com/strategy/431407
Last Modified
2023-11-07 16:00:33