
7.8 KiB
Name
多周期成交量加权均价与移动平均线突破交易策略-Multi-Timeframe-VWAP-and-EMA-Breakout-Trading-Strategy
Author
ianzeng123
Strategy Description
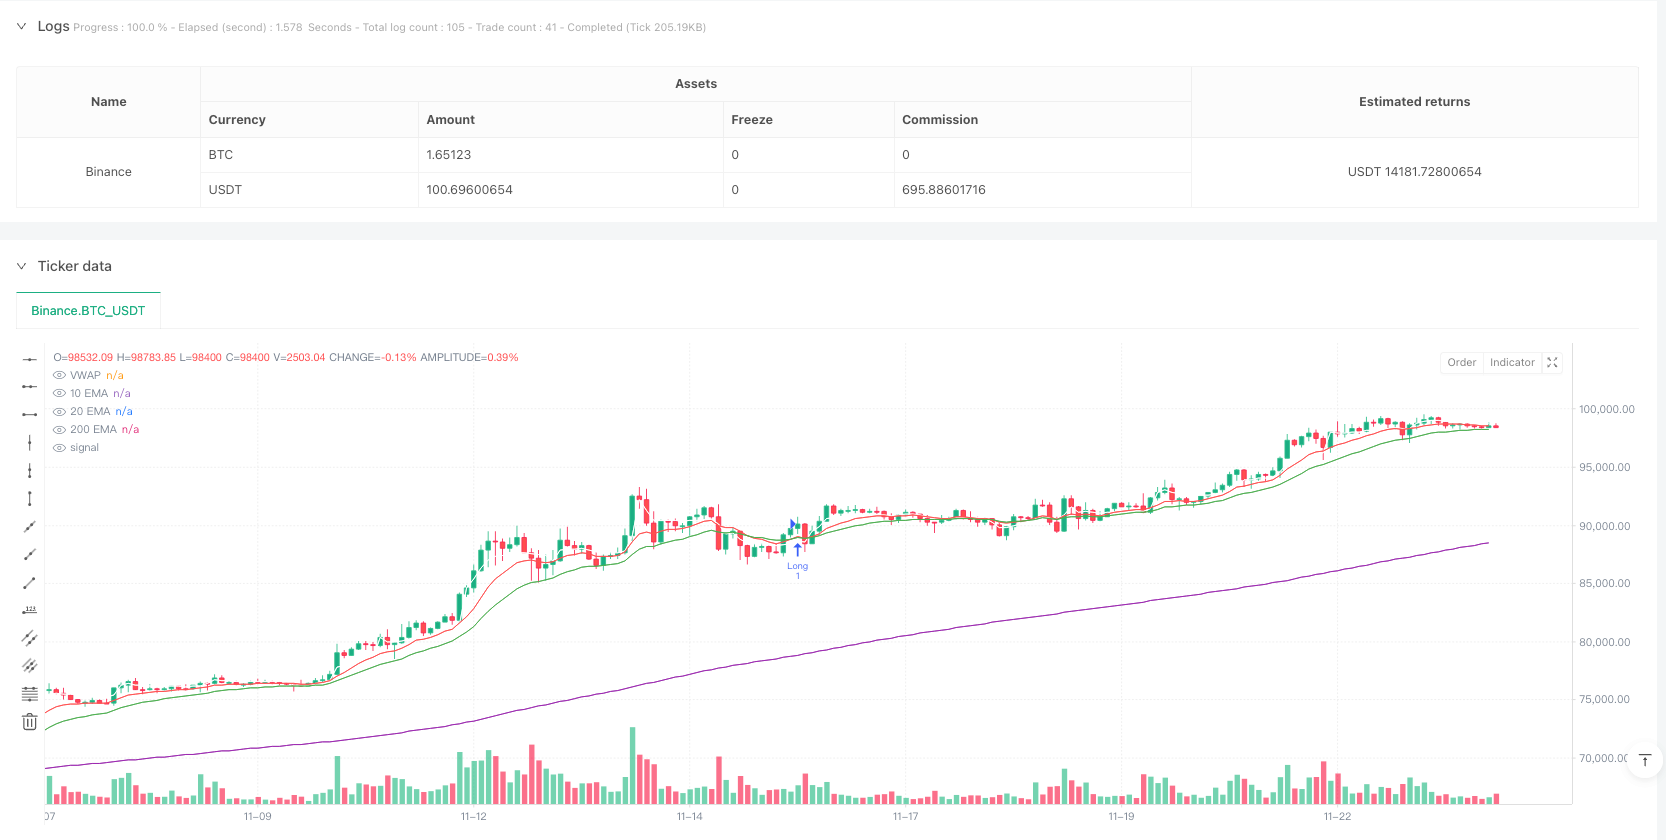
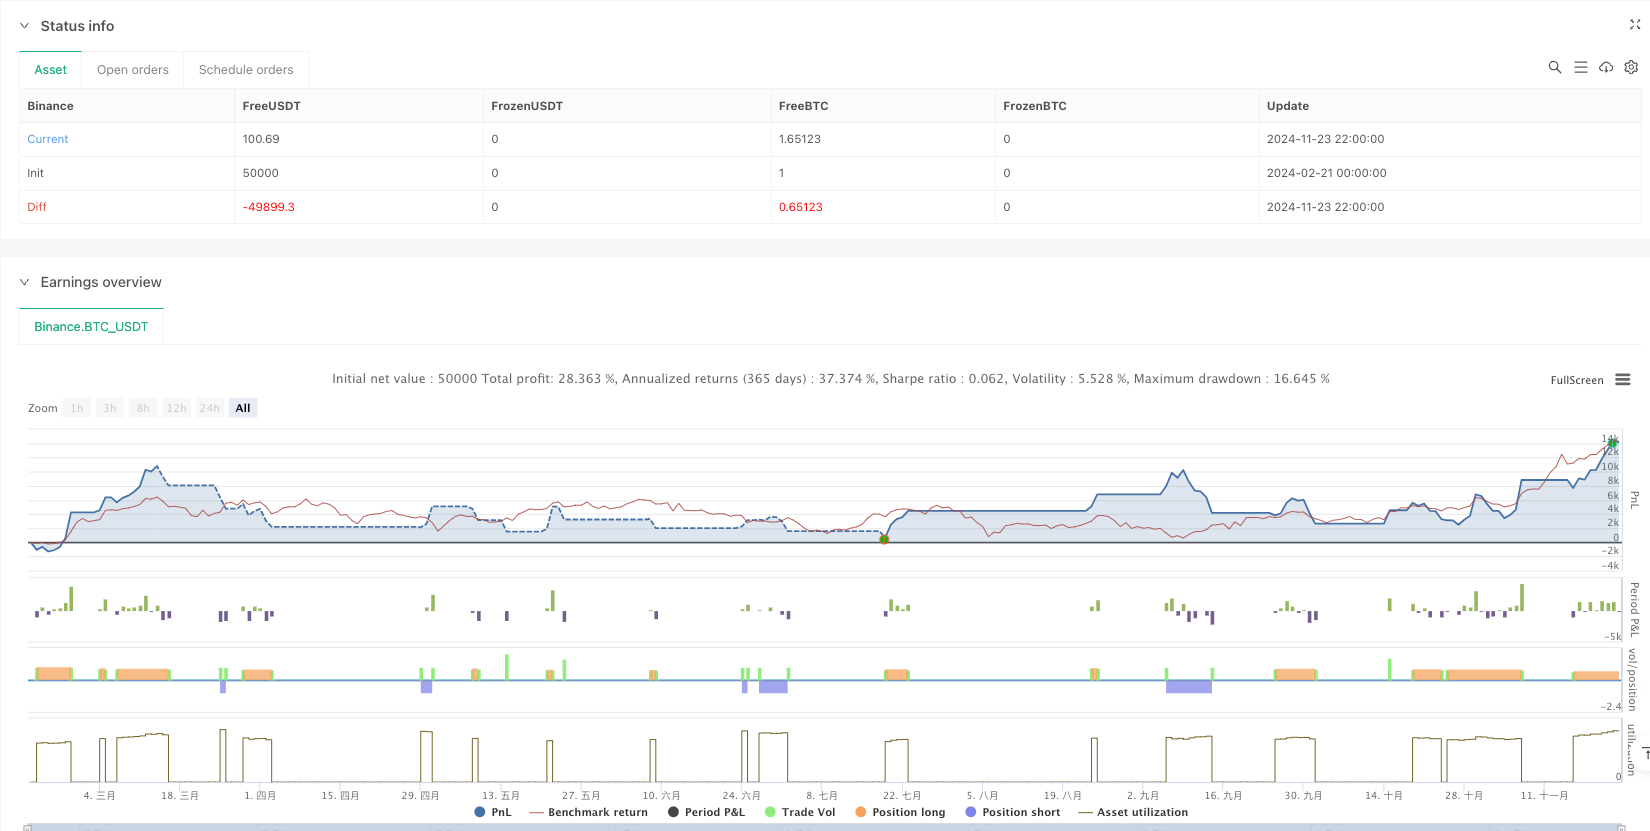
[trans]
概述
这是一个结合了成交量加权平均价(VWAP)和多周期指数移动平均线(EMA)的交易策略。该策略主要用于日内交易,特别适合15分钟时间周期。策略通过分析价格与VWAP和不同周期EMA之间的关系,结合成交量信息,来确定市场趋势和交易机会。
策略原理
策略使用了10周期、20周期和200周期的EMA,以及VWAP作为核心指标。交易信号的产生基于以下条件:
- 多头入场条件:价格需同时高于VWAP、200EMA、10EMA和20EMA;当前K线收盘价高于开盘价;VWAP位于200EMA之上;10EMA位于20EMA之上,且20EMA位于VWAP之上。
- 空头入场条件:与多头相反的条件组合。
- 止损设置:使用前10根K线的最低点(多头)或最高点(空头)加减ATR值。
- 获利目标:采用1:2和1:3的风险收益比设置两个目标位。
策略优势
- 多重确认机制:通过多个技术指标的配合使用,提高了交易信号的可靠性。
- 动态风险管理:基于ATR的动态止损设置,能够适应市场波动性的变化。
- 清晰的获利目标:采用固定的风险收益比,便于交易者进行风险控制。
- 趋势跟踪与动量结合:通过不同周期均线的配合,既捕捉趋势又不错过短期机会。
策略风险
- 滞后性风险:EMA和VWAP都是滞后指标,在市场快速转向时可能反应不及时。
- 震荡市场风险:在横盘整理阶段,可能产生过多假突破信号。
- 资金管理风险:固定的风险收益比可能不适合所有市场环境。
- 交易成本影响:频繁交易可能导致较高的交易成本。
策略优化方向
- 引入波动率过滤器:可以添加ATR百分比阈值,在低波动率环境下避免交易。
- 优化时间过滤:可以根据不同市场的特点,设置最佳交易时间段。
- 动态调整风险收益比:根据市场波动性动态调整获利目标。
- 加入成交量确认:可以设置最小成交量阈值,提高突破的可靠性。
总结
该策略通过结合多个技术指标,构建了一个完整的交易系统。策略的核心优势在于多重确认机制和完善的风险管理体系。虽然存在一定的滞后性风险,但通过建议的优化方向,可以进一步提升策略的稳定性和盈利能力。策略特别适合日内交易者使用,但需要根据具体市场特点进行参数优化。 ||
Overview
This is a trading strategy that combines Volume Weighted Average Price (VWAP) and multiple-timeframe Exponential Moving Averages (EMA). The strategy is designed for intraday trading, particularly suitable for 15-minute timeframes. It determines market trends and trading opportunities by analyzing price relationships with VWAP and different period EMAs, incorporating volume information.
Strategy Principles
The strategy utilizes 10-period, 20-period, and 200-period EMAs, along with VWAP as core indicators. Trading signals are generated based on the following conditions:
- Long entry conditions: Price must be above VWAP, 200EMA, 10EMA, and 20EMA; current candle closes above open; VWAP above 200EMA; 10EMA above 20EMA, and 20EMA above VWAP.
- Short entry conditions: Reverse conditions of long entries.
- Stop-loss: Uses 10-period low (for longs) or high (for shorts) plus/minus ATR value.
- Profit targets: Sets two targets using 1:2 and 1:3 risk-reward ratios.
Strategy Advantages
- Multiple confirmation mechanism: Improves signal reliability through the combination of multiple technical indicators.
- Dynamic risk management: ATR-based dynamic stop-loss adapts to market volatility changes.
- Clear profit objectives: Fixed risk-reward ratios facilitate risk control for traders.
- Trend following with momentum: Combines different period moving averages to capture both trends and short-term opportunities.
Strategy Risks
- Lag risk: EMA and VWAP are lagging indicators, potentially slow to react to rapid market reversals.
- Choppy market risk: May generate excessive false breakout signals during consolidation phases.
- Money management risk: Fixed risk-reward ratios might not suit all market conditions.
- Transaction cost impact: Frequent trading may result in high transaction costs.
Strategy Optimization Directions
- Implement volatility filter: Add ATR percentage threshold to avoid trading in low volatility environments.
- Optimize time filtering: Set optimal trading time windows based on specific market characteristics.
- Dynamic risk-reward adjustment: Adjust profit targets based on market volatility.
- Add volume confirmation: Set minimum volume thresholds to improve breakout reliability.
Summary
This strategy builds a comprehensive trading system by combining multiple technical indicators. Its core strengths lie in the multiple confirmation mechanism and robust risk management system. While there are inherent lag risks, the suggested optimization directions can further enhance strategy stability and profitability. The strategy is particularly suitable for intraday traders but requires parameter optimization based on specific market characteristics.[/trans]
Source (PineScript)
/*backtest
start: 2024-02-21 00:00:00
end: 2024-11-24 00:00:00
period: 2h
basePeriod: 2h
exchanges: [{"eid":"Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("VWAP EMA Breakout", overlay=true)

// Define Indicators
ema10 = ta.ema(close, 10)
ema20 = ta.ema(close, 20)
ema200 = ta.ema(close, 200)
vwap = ta.vwap(close)
atr = ta.atr(14)

// Price Conditions (Long)
priceAboveVWAP200EMA = close > vwap and close > ema200 and close > ema10 and close > ema20
bullishCandle = close > open

// Additional Conditions for VWAP and EMA Relationships (Long)
vwapAbove200EMA = vwap > ema200
emaConditions = ema10 > ema20 and ema20 > vwap and vwap > ema200

// Entry Conditions (Long)
longCondition = priceAboveVWAP200EMA and bullishCandle and vwapAbove200EMA and emaConditions

// Stop-Loss & Take-Profit (Long)
swingLow = ta.lowest(low, 10)
stopLossLong = swingLow - atr
riskLong = close - stopLossLong
takeProfitLong2 = close + (riskLong * 2) // 1:2 RR
takeProfitLong3 = close + (riskLong * 3) // 1:3 RR

// Execute Long Trade
if longCondition
    strategy.entry("Long", strategy.long)
    strategy.exit("TP 1:2", from_entry="Long", limit=takeProfitLong2, stop=stopLossLong)
    strategy.exit("TP 1:3", from_entry="Long", limit=takeProfitLong3, stop=stopLossLong)

// Price Conditions (Short)
priceBelowVWAP200EMA = close < vwap and close < ema200 and close < ema10 and close < ema20
bearishCandle = close < open

// Additional Conditions for VWAP and EMA Relationships (Short)
vwapBelow200EMA = vwap < ema200
emaConditionsShort = ema10 < ema20 and ema20 < vwap and vwap < ema200

// Entry Conditions (Short)
shortCondition = priceBelowVWAP200EMA and bearishCandle and vwapBelow200EMA and emaConditionsShort

// Stop-Loss & Take-Profit (Short)
swingHigh = ta.highest(high, 10)
stopLossShort = swingHigh + atr
riskShort = stopLossShort - close
takeProfitShort2 = close - (riskShort * 2) // 1:2 RR
takeProfitShort3 = close - (riskShort * 3) // 1:3 RR

// Execute Short Trade
if shortCondition
    strategy.entry("Short", strategy.short)
    strategy.exit("TP 1:2", from_entry="Short", limit=takeProfitShort2, stop=stopLossShort)
    strategy.exit("TP 1:3", from_entry="Short", limit=takeProfitShort3, stop=stopLossShort)

// Plot Indicators
plot(ema10, color=color.red, title="10 EMA")
plot(ema20, color=color.green, title="20 EMA")
plot(ema200, color=color.purple, title="200 EMA")
plot(vwap, color=color.white, title="VWAP")
Detail
https://www.fmz.com/strategy/482823
Last Modified
2025-02-20 13:25:02