
6.9 KiB
Name
基于伽马权重和动量的比特币期货智能交易策略-Gamma-Weighted-Momentum-Based-Bitcoin-Futures-Intelligent-Trading-Strategy
Author
ChaoZhang
Strategy Description
[trans]
概述
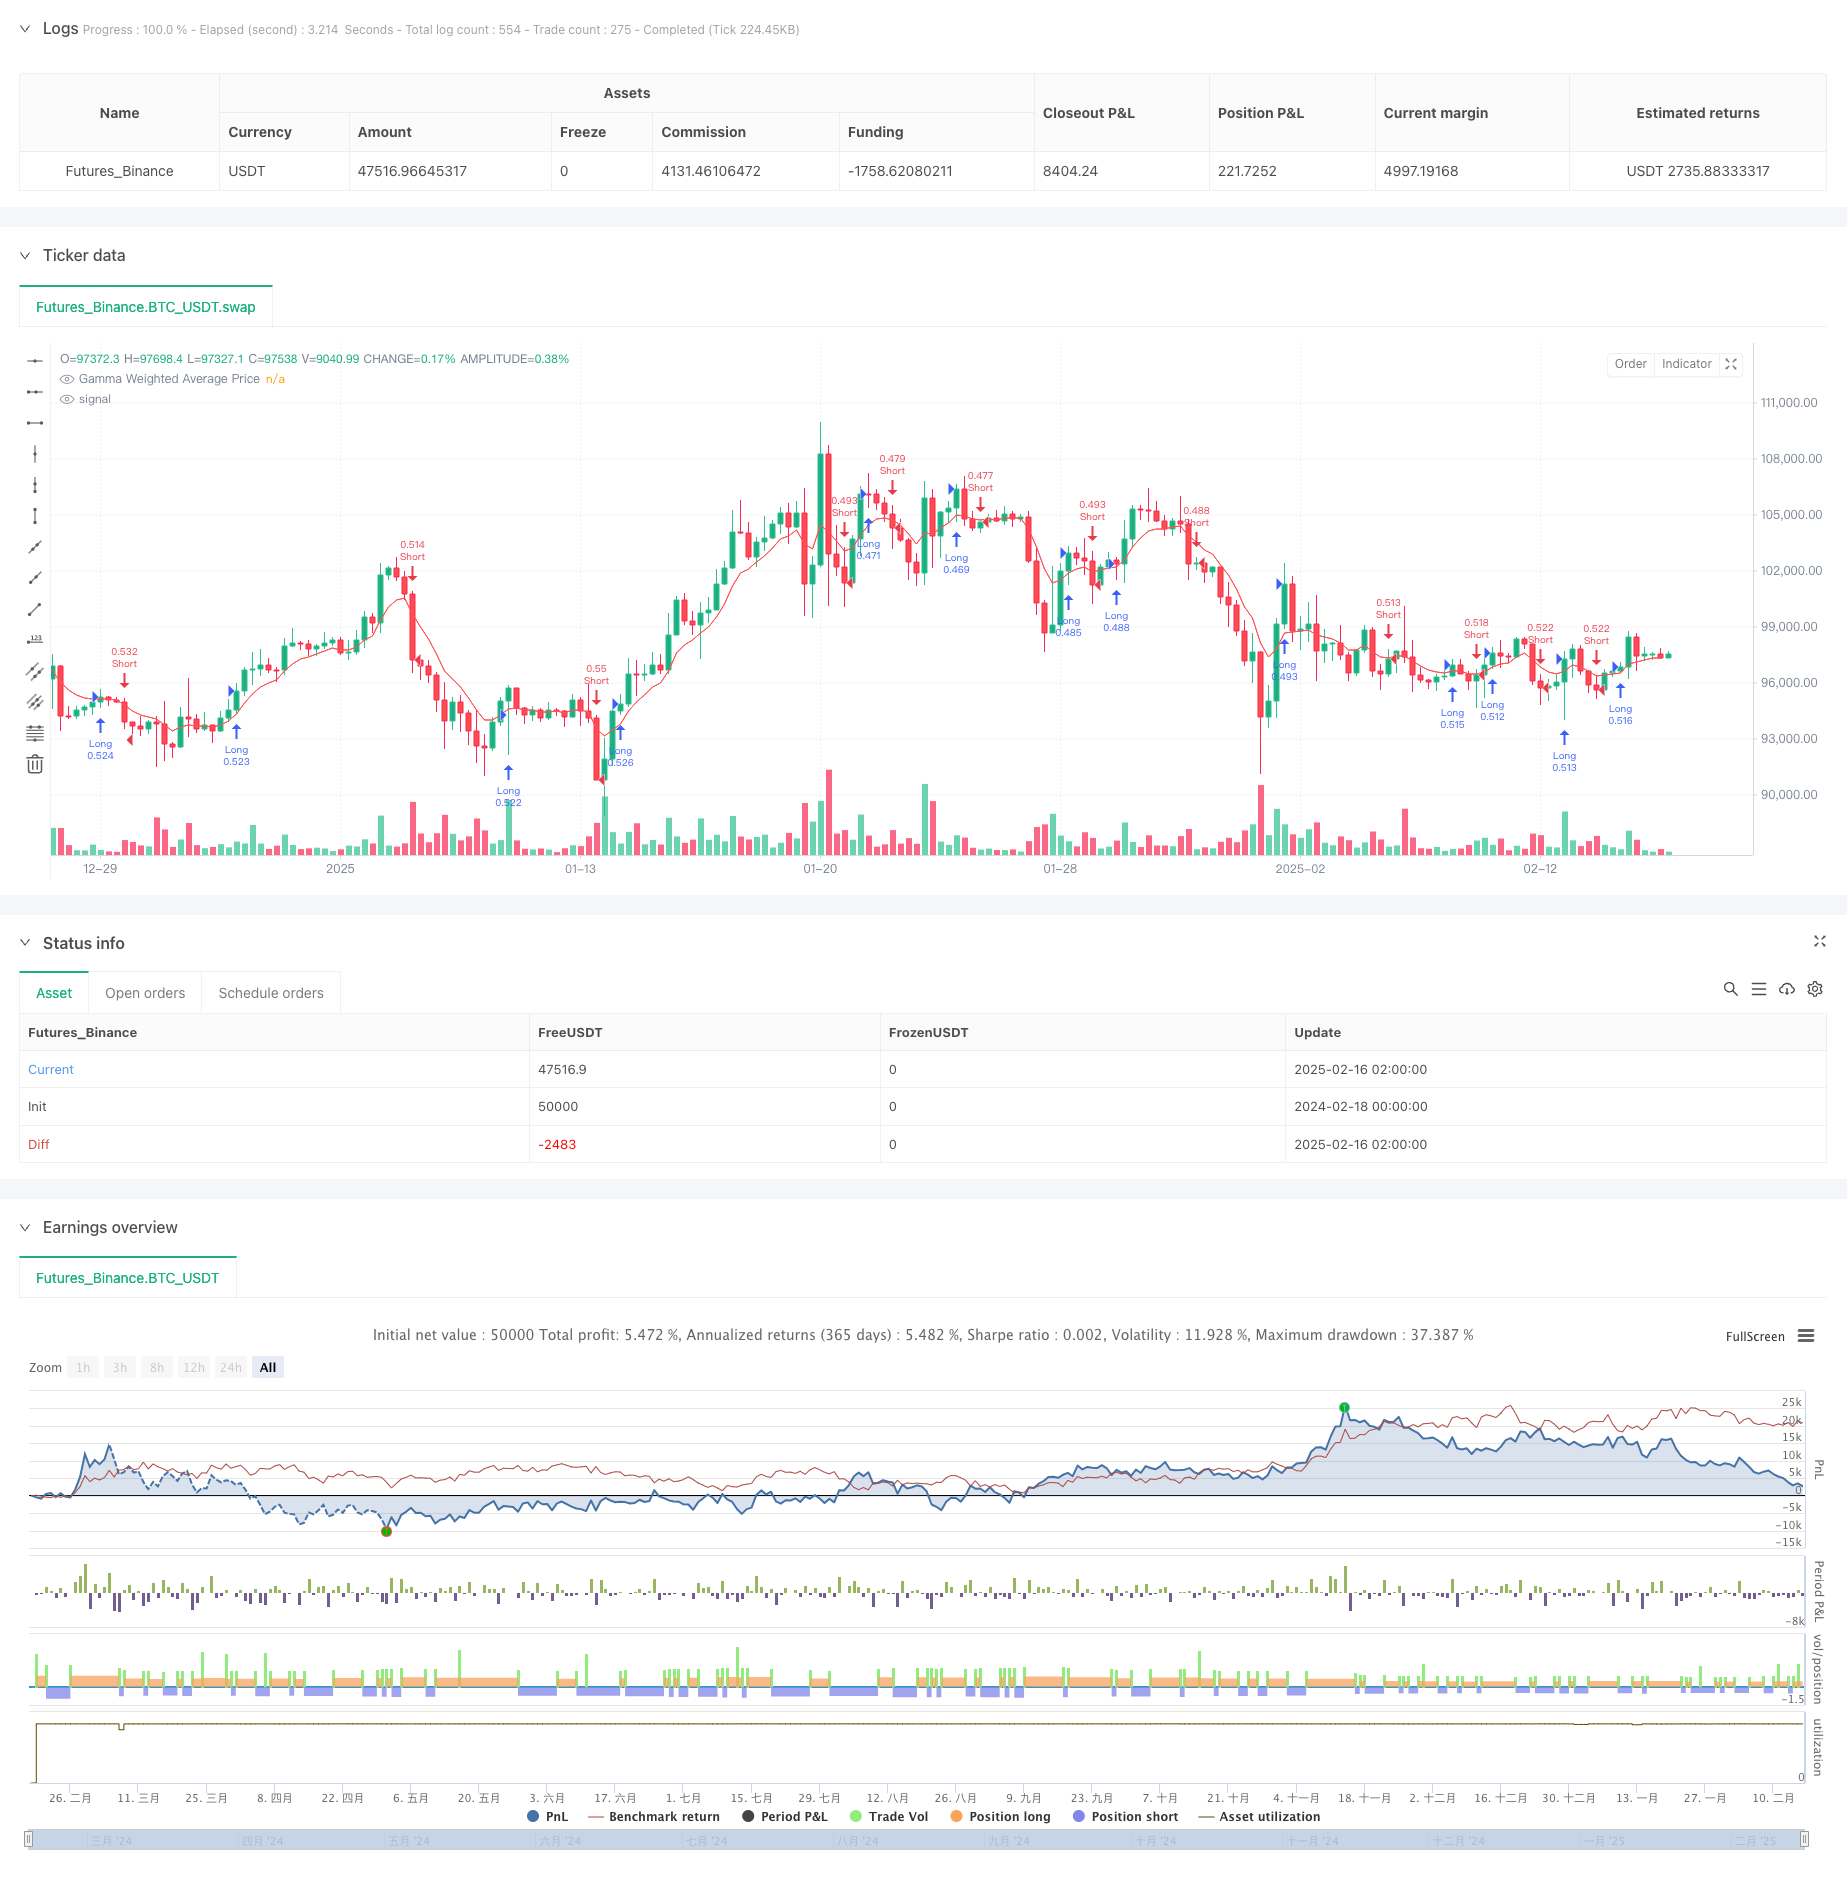
该策略是一个结合了伽马权重平均价格(GWAP)和动量分析的量化交易系统。它通过对历史价格数据进行伽马加权处理,并结合短期动量指标来预测价格走势。策略的核心在于利用伽马因子对近期价格进行更高的权重分配,从而提高对市场近期走势的敏感度。
策略原理
策略主要基于两个核心理论:动量效应和伽马权重定价。在动量方面,策略利用了金融市场中价格趋势延续的特性;在权重方面,通过伽马因子(取值范围0.5-1.5)对历史价格进行指数级衰减加权。具体实现上,策略通过计算GWAP作为基准价格,当价格位于GWAP之上且连续三个周期呈上涨趋势时开立多仓,反之则开立空仓。
策略优势
- 自适应性强:伽马权重机制能够根据市场状况动态调整对历史数据的权重分配。
- 风险控制完善:通过GWAP作为基准价格,为交易决策提供了可靠的参考标准。
- 计算效率高:策略采用数组存储和循环计算方式,优化了计算效率。
- 参数可调性好:关键参数如伽马因子和计算周期都可以根据市场情况灵活调整。
策略风险
- 市场波动风险:在震荡市场中可能产生频繁的假信号。
- 参数敏感性:伽马因子的选择对策略表现影响较大,需要持续优化。
- 计算延迟:大量历史数据的处理可能导致实盘执行延迟。
- 趋势反转风险:在市场趋势突然反转时,策略反应可能相对滞后。
策略优化方向
- 引入波动率自适应机制,动态调整伽马因子。
- 增加多重时间周期的趋势确认机制。
- 优化计算效率,减少数组操作次数。
- 添加市场情绪指标,提高策略的预测准确性。
- 实现动态止损机制,提高风险控制能力。
总结
该策略通过结合伽马权重和动量分析,实现了对市场趋势的智能跟踪。其核心优势在于能够根据市场状况动态调整权重分配,同时保持了较高的计算效率。虽然存在一定的市场风险和参数敏感性问题,但通过持续优化和完善,策略具有良好的应用前景。 ||
Overview
This strategy is a quantitative trading system that combines Gamma-Weighted Average Price (GWAP) and momentum analysis. It predicts price movements by applying gamma weighting to historical price data and incorporating short-term momentum indicators. The core concept lies in assigning higher weights to recent prices through the gamma factor, thereby increasing sensitivity to recent market trends.
Strategy Principle
The strategy is based on two core theories: momentum effect and gamma-weighted pricing. For momentum, it leverages the tendency of price trends to persist in financial markets. For weighting, it applies exponential decay weighting to historical prices through a gamma factor (range 0.5-1.5). In implementation, the strategy calculates GWAP as a benchmark price, initiating long positions when prices are above GWAP with three consecutive periods of upward trend, and short positions under opposite conditions.
Strategy Advantages
- Strong adaptability: The gamma weighting mechanism can dynamically adjust weights assigned to historical data based on market conditions.
- Comprehensive risk control: GWAP serves as a reliable benchmark price for trading decisions.
- High computational efficiency: The strategy employs array storage and loop calculations to optimize performance.
- Good parameter adjustability: Key parameters like gamma factor and calculation period can be flexibly adjusted according to market conditions.
Strategy Risks
- Market volatility risk: May generate frequent false signals in choppy markets.
- Parameter sensitivity: Strategy performance is highly dependent on gamma factor selection, requiring continuous optimization.
- Computational delay: Processing large amounts of historical data may lead to execution delays in live trading.
- Trend reversal risk: Strategy response may lag during sudden market trend reversals.
Strategy Optimization Directions
- Introduce volatility-adaptive mechanisms to dynamically adjust the gamma factor.
- Add multi-timeframe trend confirmation mechanisms.
- Optimize computational efficiency by reducing array operations.
- Incorporate market sentiment indicators to improve prediction accuracy.
- Implement dynamic stop-loss mechanisms to enhance risk control.
Summary
The strategy achieves intelligent market trend tracking by combining gamma weighting and momentum analysis. Its core advantage lies in the ability to dynamically adjust weight distribution according to market conditions while maintaining high computational efficiency. Although there are certain market risks and parameter sensitivity issues, the strategy shows good application prospects through continuous optimization and improvement.[/trans]
Source (PineScript)
/*backtest
start: 2024-02-18 00:00:00
end: 2025-02-16 08:00:00
period: 6h
basePeriod: 6h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("BTC Future Gamma-Weighted Momentum Model (BGMM)", shorttitle="BGMM", overlay=true,
         default_qty_type=strategy.cash, default_qty_value=50000,
         slippage=1, commission_value=0.01)

// Inputs
length = input.int(60, "Length for GWAP Calculation")
gamma_factor = input.float(0.75, "Gamma Weight Factor", minval=0.5, maxval=1.5, step=0.01)

// Helper Functions
var float cumulative_weighted_price = na
var float cumulative_weight = na

price = (high + low + close) / 3  // Typical price as a baseline

gamma_weights = array.new_float(length, 0.0)
price_series = array.new_float(length, na)

// Populate Arrays for Calculation
if bar_index >= length
    for i = 0 to length - 1
        weighted_gamma = math.pow(gamma_factor, i)
        array.set(gamma_weights, i, weighted_gamma)
        array.set(price_series, i, close[i])

// Compute GWAP
weighted_sum = 0.0
weight_total = 0.0
for i = 0 to length - 1
    w = array.get(gamma_weights, i)
    p = array.get(price_series, i)
    weighted_sum := weighted_sum + p * w
    weight_total := weight_total + w

GWAP = weight_total != 0 ? weighted_sum / weight_total : na

plot(GWAP, color=color.red, title="Gamma Weighted Average Price")

// Conditions for Trade Signals
long_condition = close > GWAP and close[1] > close[2] and close[2] > close[3]
short_condition = close < GWAP and close[1] < close[2] and close[2] < close[3]

// Strategy Logic
if long_condition
    strategy.entry("Long", strategy.long)

if short_condition
    strategy.entry("Short", strategy.short)
Detail
https://www.fmz.com/strategy/482474
Last Modified
2025-02-18 15:45:58