
9.0 KiB
Name
双时间周期超级趋势与RSI策略优化系统-Dual-Timeframe-Supertrend-with-RSI-Optimization-System
Author
ChaoZhang
Strategy Description
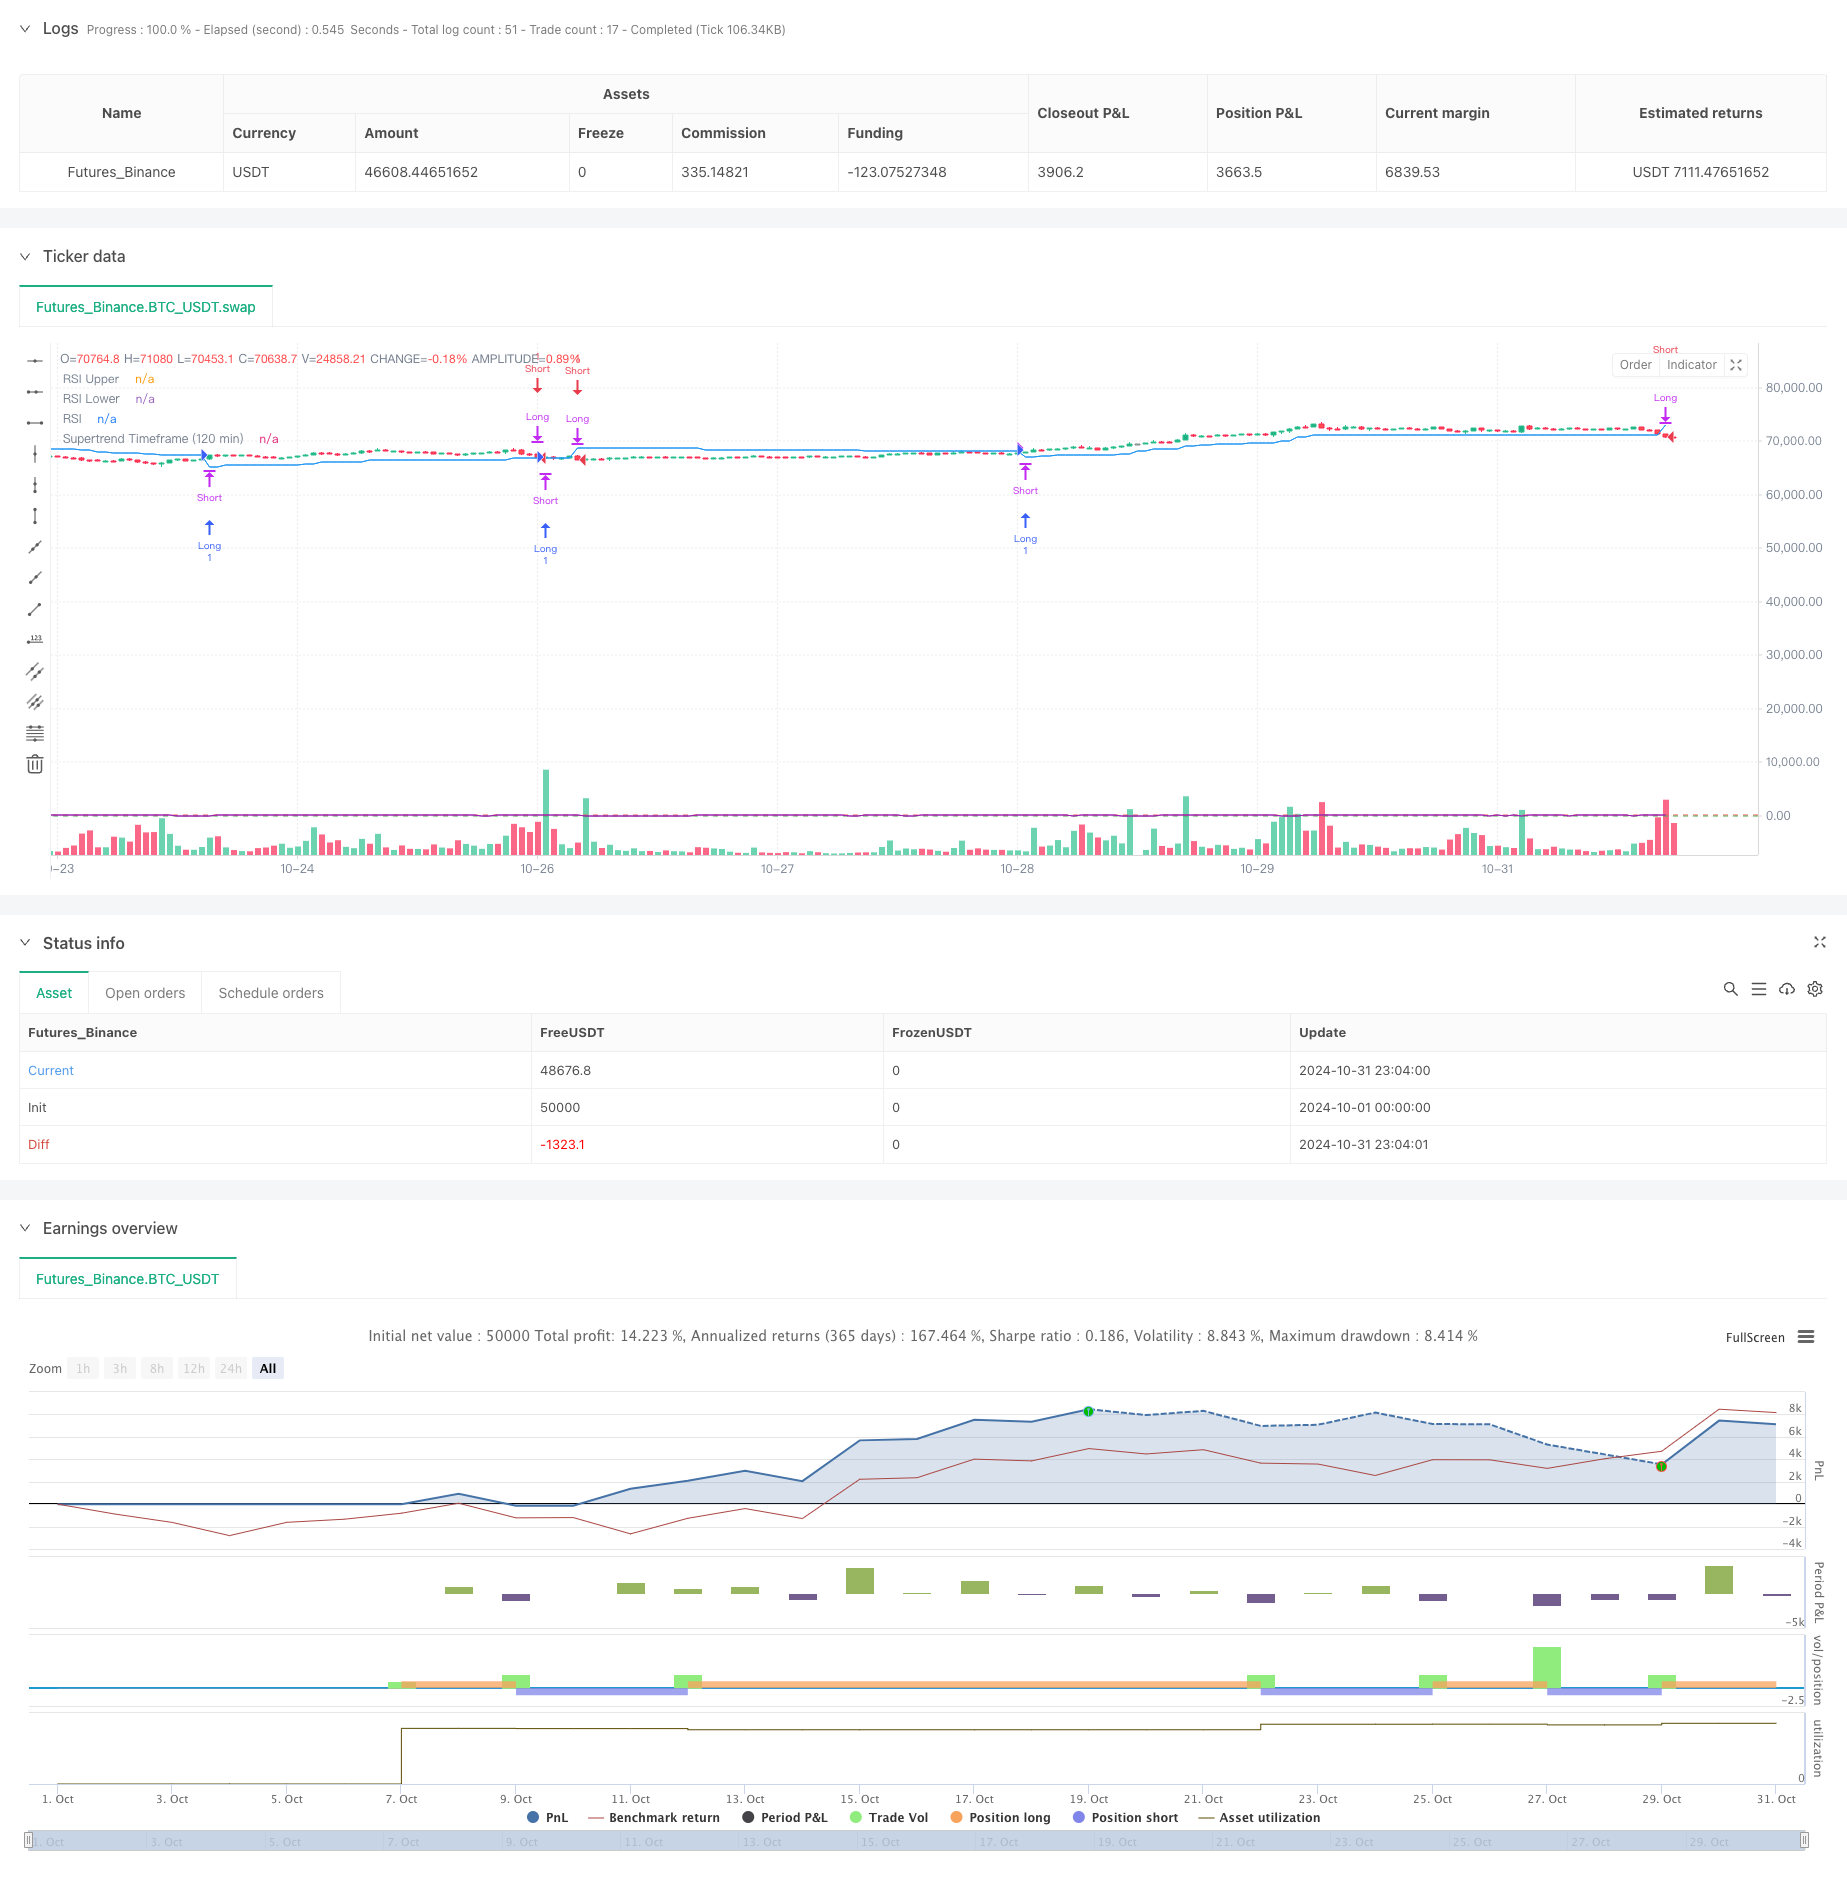
[trans]
概述
该策略是一个基于SuperTrend指标和RSI指标的双时间周期交易系统。它结合了120分钟和15分钟两个时间周期的技术分析指标,通过SuperTrend指标捕捉中期趋势方向,同时利用RSI指标进行获利了结。策略采用资金管理机制,通过百分比分配仓位,并设置了基于百分比的止盈条件。
策略原理
策略的核心逻辑建立在以下几个关键要素上:
- 使用120分钟周期的SuperTrend指标作为主要趋势判断工具,该指标基于ATR周期为14,因子设置为3.42
- 通过价格与SuperTrend线的交叉来确定交易信号,向上穿越产生做多信号,向下穿越产生做空信号
- 采用15分钟周期的RSI指标作为辅助工具,RSI周期设为5,用于市场过热或过冷的判断
- 在RSI达到超买区(95)时平掉多头仓位,在达到超卖区(5)时平掉空头仓位
- 设置30%的百分比止盈点,相对于开仓均价计算
策略优势
- 多时间周期结合提高了信号的可靠性,降低了虚假信号的影响
- SuperTrend指标的参数优化适中,既保证了对趋势的敏感度,又避免了过度灵敏导致的频繁交易
- RSI指标的极值设置非常严格(5和95),确保只在极端行情下触发平仓,避免过早离场
- 资金管理采用账户净值的固定比例(35%),有效控制风险的同时保证了收益空间
- 在开新仓位前会自动平掉反向持仓,避免了同时持有多空仓位的风险
策略风险
- 双时间周期策略在震荡市场可能产生滞后效应,需要注意控制回撤
- RSI指标的极值设置过于严格,可能导致错过一些获利了结的机会
- 30%的止盈点设置较为激进,在波动较大的市场中可能过早获利了结
- 策略未设置止损条件,在趋势突然反转时可能承受较大损失
- 35%的仓位配比相对激进,在市场剧烈波动时风险较大
策略优化方向
- 建议增加动态止损机制,可以考虑基于ATR的跟踪止损
- RSI的超买超卖阈值可以适当放宽,建议调整为10和90,提高策略的适应性
- 可以添加成交量指标作为辅助确认,提高信号的可靠性
- 考虑根据市场波动情况动态调整仓位比例,使用ATR或波动率指标
- 建议增加趋势强度过滤器,例如DMI或ADX指标,过滤弱趋势行情
总结
这是一个结构完整、逻辑清晰的趋势跟踪策略。通过组合不同时间周期的技术指标,在把握趋势的同时也注意风险控制。虽然还存在一些可以优化的空间,但整体设计理念符合量化交易的基本原则。建议交易者在实盘使用前,先通过回测优化各项参数,并根据自己的风险承受能力调整仓位配比。 ||
Overview
This strategy is a dual timeframe trading system based on the SuperTrend indicator and RSI. It combines technical analysis indicators from 120-minute and 15-minute timeframes, using SuperTrend to capture medium-term trend direction while utilizing RSI for profit-taking. The strategy implements position sizing through percentage allocation and includes percentage-based take-profit conditions.
Strategy Principles
The core logic is built on several key elements:
- Uses 120-minute timeframe SuperTrend indicator as the main trend determination tool, with ATR period of 14 and factor of 3.42
- Generates trading signals through price crossovers with SuperTrend line - upward crosses for long entries and downward crosses for short entries
- Employs 15-minute timeframe RSI indicator with period 5 as a supplementary tool for market overbought/oversold conditions
- Closes long positions when RSI reaches overbought zone (95) and short positions at oversold zone (5)
- Sets 30% take-profit level calculated relative to entry average price
Strategy Advantages
- Multiple timeframe combination improves signal reliability and reduces false signals
- Optimized SuperTrend parameters balance trend sensitivity while avoiding excessive trading
- Strict RSI extreme values (5 and 95) ensure position closing only in extreme conditions
- Position sizing uses fixed percentage of equity (35%), effectively controlling risk while maintaining profit potential
- Automatically closes reverse positions before opening new ones, avoiding simultaneous long and short exposure
Strategy Risks
- Dual timeframe approach may create lag in ranging markets, requiring drawdown management
- Strict RSI extreme values might cause missed profit-taking opportunities
- 30% take-profit level is aggressive, potentially leading to early exits in volatile markets
- Lack of stop-loss conditions could result in significant losses during sudden trend reversals
- 35% position sizing is relatively aggressive, creating high risk during extreme volatility
Optimization Directions
- Recommend adding dynamic stop-loss mechanism, considering ATR-based trailing stops
- RSI overbought/oversold thresholds could be adjusted to 10 and 90 for better adaptability
- Volume indicators could be added for signal confirmation
- Consider dynamic position sizing based on market volatility using ATR or volatility indicators
- Suggest adding trend strength filters like DMI or ADX to filter weak trends
Summary
This is a well-structured trend-following strategy with clear logic. It combines different timeframe technical indicators to capture trends while maintaining risk control. While there's room for optimization, the overall design aligns with quantitative trading principles. Traders should backtest and optimize parameters before live trading and adjust position sizing according to their risk tolerance.[/trans]
Source (PineScript)
/*backtest
start: 2024-10-01 00:00:00
end: 2024-10-31 23:59:59
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © felipemiransan

//@version=5
strategy("Supertrend Strategy", overlay=true)

// Function for Supertrend
supertrend(_factor, _atrPeriod) =>
    [out, _] = ta.supertrend(_factor, _atrPeriod)
    out

// Supertrend Settings
factor = input.float(3.42, title="Supertrend Factor")
atrPeriod = input.int(14, title="ATR Period")
tf2 = input.timeframe("120", title="Supertrend Timeframe")

// RSI Settings
rsi_tf = input.timeframe("15", title="RSI Timeframe")
rsiLength = input.int(5, title="RSI Length")
rsiUpper = input.int(95, title="RSI Upper Limit")
rsiLower = input.int(5, title="RSI Lower Limit")

// RSI Timeframe
rsi_tf_value = request.security(syminfo.tickerid, rsi_tf, ta.rsi(close, rsiLength), lookahead=barmerge.lookahead_off, gaps=barmerge.gaps_off)

// Supertrend Timeframe
supertrend_tf2 = request.security(syminfo.tickerid, tf2, supertrend(factor, atrPeriod), lookahead=barmerge.lookahead_off, gaps=barmerge.gaps_off)

// Take Profit Settings (Percentage in relation to the average price)
takeProfitPercent = input.float(30, title="Take Profit", step=0.1) / 100

// Entry conditions based on price crossover with Supertrend Timeframe
longCondition = ta.crossover(close, supertrend_tf2) and barstate.isconfirmed
shortCondition = ta.crossunder(close, supertrend_tf2) and barstate.isconfirmed

// Execution of reversal orders with closing of previous position
if (longCondition)
    // Close a short position before opening a long position
    if (strategy.position_size < 0)
        strategy.close("Short", comment="Close Short for Long Entry")
    strategy.entry("Long", strategy.long)

if (shortCondition)
    // Close long position before opening short position
    if (strategy.position_size > 0)
        strategy.close("Long", comment="Close Long for Short Entry")
    strategy.entry("Short", strategy.short)

// Calculate take profit levels relative to the average entry price
if (strategy.position_size > 0)
    takeProfitLong = strategy.position_avg_price * (1 + takeProfitPercent)
    strategy.exit("Take Profit Long", "Long", limit=takeProfitLong)

if (strategy.position_size > 0 and (rsi_tf_value >= rsiUpper))
    strategy.close("Long", comment="RSI Take Profit Long")

if (strategy.position_size < 0)
    takeProfitShort = strategy.position_avg_price * (1 - takeProfitPercent)
    strategy.exit("Take Profit Short", "Short", limit=takeProfitShort)

if (strategy.position_size < 0 and (rsi_tf_value <= rsiLower))
    strategy.close("Short", comment="RSI Take Profit Short")

// Plot Supertrend timeframe with commit check to avoid repainting
plot(barstate.isconfirmed ? supertrend_tf2 : na, color=color.blue, title="Supertrend Timeframe (120 min)", linewidth=1)

// Plot RSI for visualization
plot(rsi_tf_value, "RSI", color=color.purple)
hline(rsiUpper, "RSI Upper", color=color.red)
hline(rsiLower, "RSI Lower", color=color.green)
Detail
https://www.fmz.com/strategy/472973
Last Modified
2024-11-25 17:27:21