
8.4 KiB
Name
动态趋势跟踪的EMA-ADX多级止盈策略-Dynamic-Trend-Following-EMA-ADX-Multi-Level-Take-Profit-Strategy
Author
ChaoZhang
Strategy Description
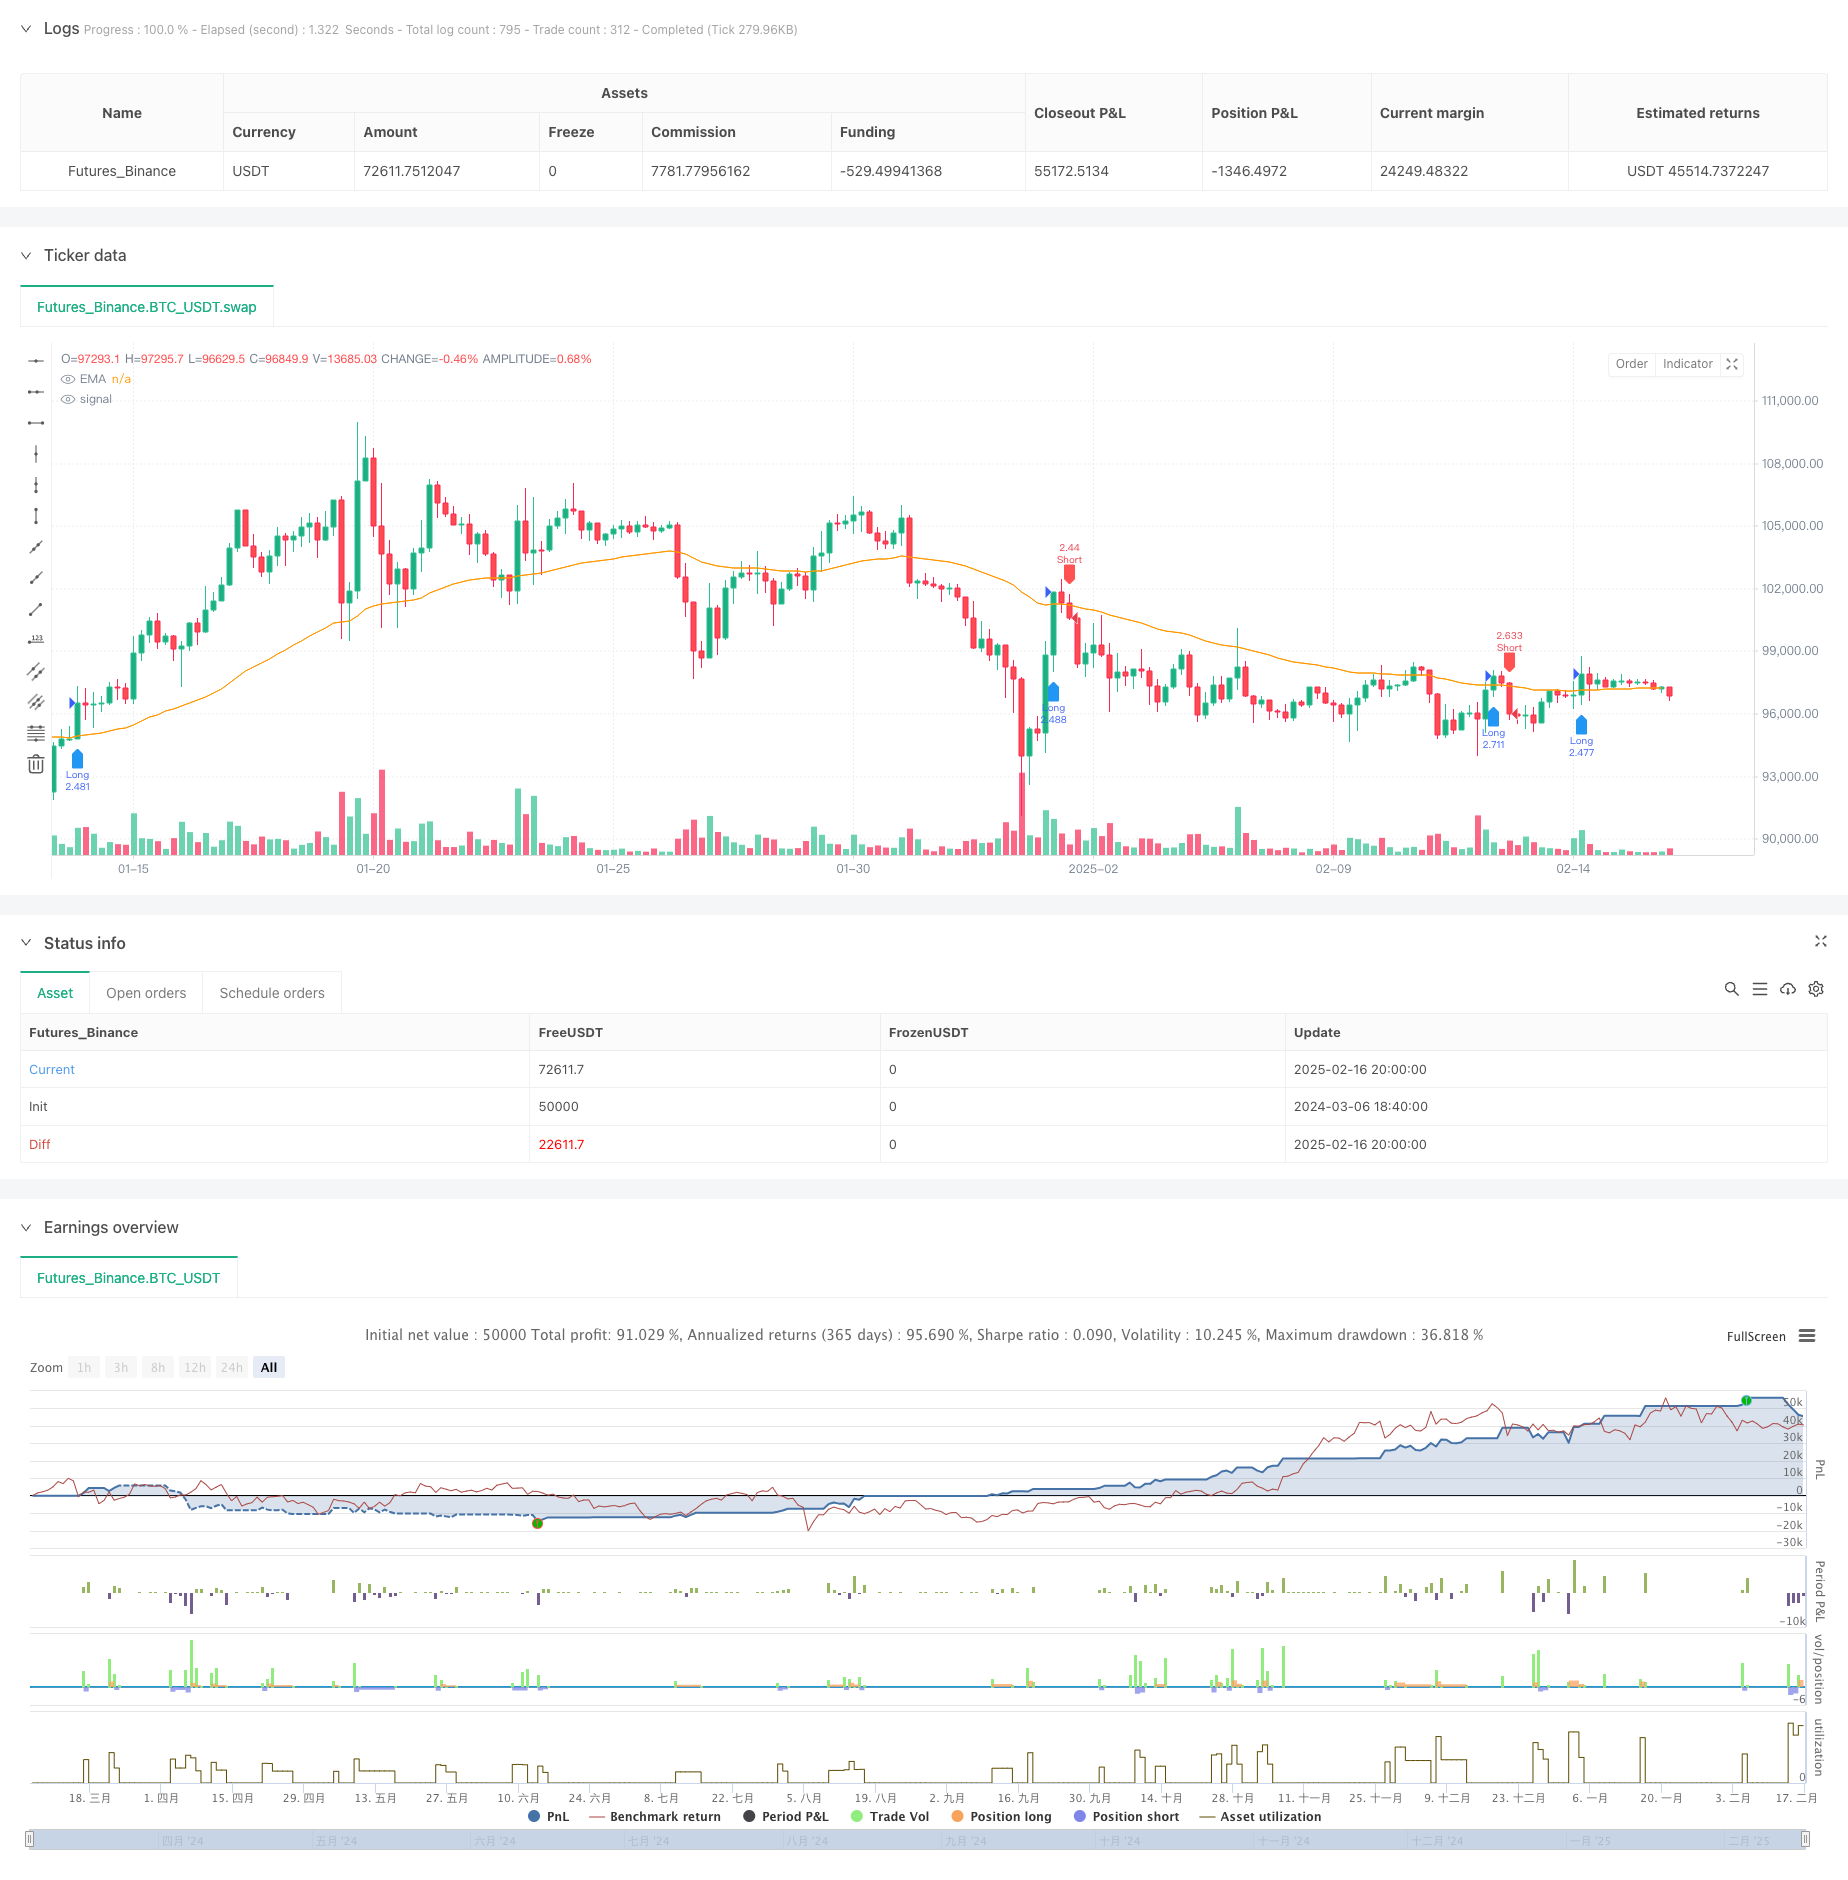
[trans]
概述
该策略是一个结合EMA和ADX指标的趋势跟踪交易系统,通过多级止盈和移动止损来优化资金管理。策略采用EMA均线作为趋势方向判断,ADX指标作为趋势强度过滤,并设计了三层止盈机制来分批获利,同时运用ATR动态调整止损位置来控制风险。
策略原理
策略的核心逻辑包含以下几个关键部分:
- 使用50周期EMA均线判断趋势方向,价格突破EMA上方开多,突破下方开空
- 通过14周期ADX指标过滤弱趋势,ADX>20时确认趋势有效
- 基于14周期ATR计算动态止损位置,多单在最低价减去1ATR,空单在最高价加上1ATR
- 采用三层止盈机制:
- 第一层:30%仓位在1倍ATR处止盈
- 第二层:50%仓位在2倍ATR处止盈
- 第三层:20%仓位采用3倍ATR的移动止盈
- 当价格达到第二层止盈位置时,自动平掉所有剩余仓位
策略优势
- 多层止盈设计既能及时锁定利润,又不会错过大行情
- 移动止损机制可以自适应市场波动率,提供动态风险控制
- ADX过滤能有效避免震荡市的虚假信号
- EMA和价格交叉提供清晰的进场信号
- 分批止盈降低了情绪波动,有利于策略的长期执行
策略风险
- 在震荡市场中可能频繁进出导致成本增加
- EMA作为滞后指标可能在快速反转时反应不及时
- 固定的ADX阈值在不同市场环境下可能需要调整
- 多层止盈可能在单边趋势中过早减仓 缓解措施:
- 可以根据不同市场周期动态调整ADX阈值
- 考虑增加趋势确认指标
- 对止盈比例进行更细致的参数优化
策略优化方向
- 引入成交量指标来增强趋势确认
- 根据市场波动率动态调整ADX阈值
- 优化止盈层次的仓位分配比例
- 增加趋势强度分级,对应不同的止盈策略
- 考虑加入季节性因素和市场周期判断
总结
这是一个结构完整、逻辑清晰的趋势跟踪策略,通过多层止盈和动态止损来平衡收益和风险。策略整体设计符合量化交易的基本原则,具有良好的可扩展性和优化空间。通过合理的参数调整和优化升级,该策略有望在不同市场环境下保持稳定表现。
||
Overview
This strategy is a trend-following trading system that combines EMA and ADX indicators with multi-level take-profit and trailing stop-loss mechanisms for optimized money management. It uses EMA for trend direction determination, ADX for trend strength filtering, and implements a three-tiered take-profit mechanism for batch profit-taking, while using ATR for dynamic stop-loss adjustment to control risk.
Strategy Principles
The core logic includes several key components:
- Uses 50-period EMA to determine trend direction, entering long when price crosses above EMA and short when crossing below
- Filters weak trends using 14-period ADX, confirming valid trends when ADX>20
- Calculates dynamic stop-loss positions based on 14-period ATR, setting stops at low-1ATR for longs and high+1ATR for shorts
- Implements a three-tiered take-profit mechanism:
- First tier: 30% position closes at 1x ATR
- Second tier: 50% position closes at 2x ATR
- Third tier: 20% position uses 3x ATR trailing stop
- Automatically closes all remaining positions when price reaches second-tier take-profit level
Strategy Advantages
- Multi-level take-profit design secures profits while maintaining exposure to larger moves
- Trailing stop mechanism adapts to market volatility, providing dynamic risk control
- ADX filtering effectively avoids false signals in ranging markets
- EMA and price crossovers provide clear entry signals
- Batch profit-taking reduces emotional volatility, supporting long-term strategy execution
Strategy Risks
- May result in frequent trading and increased costs in ranging markets
- EMA as a lagging indicator might be slow to react in rapid reversals
- Fixed ADX threshold may need adjustment in different market conditions
- Multi-level take-profit might reduce position size too early in strong trends Mitigation measures:
- Dynamically adjust ADX threshold based on market cycles
- Consider adding trend confirmation indicators
- Optimize take-profit ratio parameters more precisely
Strategy Optimization Directions
- Incorporate volume indicators for enhanced trend confirmation
- Implement dynamic ADX thresholds based on market volatility
- Optimize position allocation ratios for take-profit levels
- Add trend strength classification with corresponding take-profit strategies
- Consider incorporating seasonality and market cycle factors
Summary
This is a well-structured trend-following strategy with clear logic, balancing returns and risks through multi-level take-profits and dynamic stop-losses. The strategy design adheres to basic quantitative trading principles, offering good scalability and optimization potential. Through appropriate parameter adjustment and optimization upgrades, this strategy has the potential to maintain stable performance across different market conditions. [/trans]
Source (PineScript)
/*backtest
start: 2024-03-06 18:40:00
end: 2025-02-17 00:00:00
period: 4h
basePeriod: 4h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("BTC Optimized Strategy v6", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=250)

// === 參數設定 ===
lengthEMA = input(50, title="EMA 週期")
adxLength = input(14, title="ADX 週期")
atrLength = input(14, title="ATR 週期")
riskReward = input(2.0, title="風險報酬比")
tp1_ratio = input(1.0, title="TP1 (ATR 倍數)")
tp2_ratio = input(2.0, title="TP2 (ATR 倍數)")
trailATR = input(3.0, title="移動止盈 ATR 倍數")

// === 計算技術指標 ===
ema = ta.ema(close, lengthEMA)
atr = ta.atr(atrLength)

// === 計算 ADX ===
upMove = math.max(high - nz(high[1], high), 0)
downMove = math.max(nz(low[1], low) - low, 0)
tr = math.max(math.max(high - low, math.abs(high - nz(close[1], close))), math.abs(low - nz(close[1], close)))
plusDM = upMove > downMove and upMove > 0 ? upMove : 0
minusDM = downMove > upMove and downMove > 0 ? downMove : 0
plusDI = 100 * ta.rma(plusDM, adxLength) / ta.rma(tr, adxLength)
minusDI = 100 * ta.rma(minusDM, adxLength) / ta.rma(tr, adxLength)
dx = 100 * math.abs(plusDI - minusDI) / (plusDI + minusDI)
adx = ta.rma(dx, adxLength)

// === 趨勢過濾條件 ===
isTrending = adx > 20

// === 進場條件 ===
longCondition = ta.crossover(close, ema) and isTrending
shortCondition = ta.crossunder(close, ema) and isTrending

// === 計算止損、止盈價格 ===
longStopLoss = low - atr
shortStopLoss = high + atr
longTP1 = close + tp1_ratio * atr
longTP2 = close + tp2_ratio * atr
shortTP1 = close - tp1_ratio * atr
shortTP2 = close - tp2_ratio * atr

// === 設定進場和出場 ===
if longCondition
    strategy.entry("Long", strategy.long)
    strategy.exit("Long_Exit1", from_entry="Long", qty_percent=30, limit=longTP1, stop=longStopLoss)
    strategy.exit("Long_Exit2", from_entry="Long", qty_percent=50, limit=longTP2, stop=longStopLoss)
    strategy.exit("Long_Trail", from_entry="Long", qty_percent=20,
                 trail_points=atr * trailATR,
                 trail_offset=atr * trailATR)

if shortCondition
    strategy.entry("Short", strategy.short)
    strategy.exit("Short_Exit1", from_entry="Short", qty_percent=30, limit=shortTP1, stop=shortStopLoss)
    strategy.exit("Short_Exit2", from_entry="Short", qty_percent=50, limit=shortTP2, stop=shortStopLoss)
    strategy.exit("Short_Trail", from_entry="Short", qty_percent=20,
                 trail_points=atr * trailATR,
                 trail_offset=atr * trailATR)

// === 當價格超過 TP2 後,自動平倉 ===
if close >= longTP2
    strategy.close("Long")

if close <= shortTP2
    strategy.close("Short")

// === 畫圖標示 ===
plotshape(series=longCondition, location=location.belowbar, color=color.blue, style=shape.labelup, title="買入")
plotshape(series=shortCondition, location=location.abovebar, color=color.red, style=shape.labeldown, title="賣出")
plot(ema, color=color.orange, title="EMA")
Detail
https://www.fmz.com/strategy/482432
Last Modified
2025-02-18 14:08:02