
7.6 KiB
Name
Keltner-Channels-EMA-ATR-Strategy-Keltner通道EMA-ATR策略
Author
ChaoZhang
Strategy Description
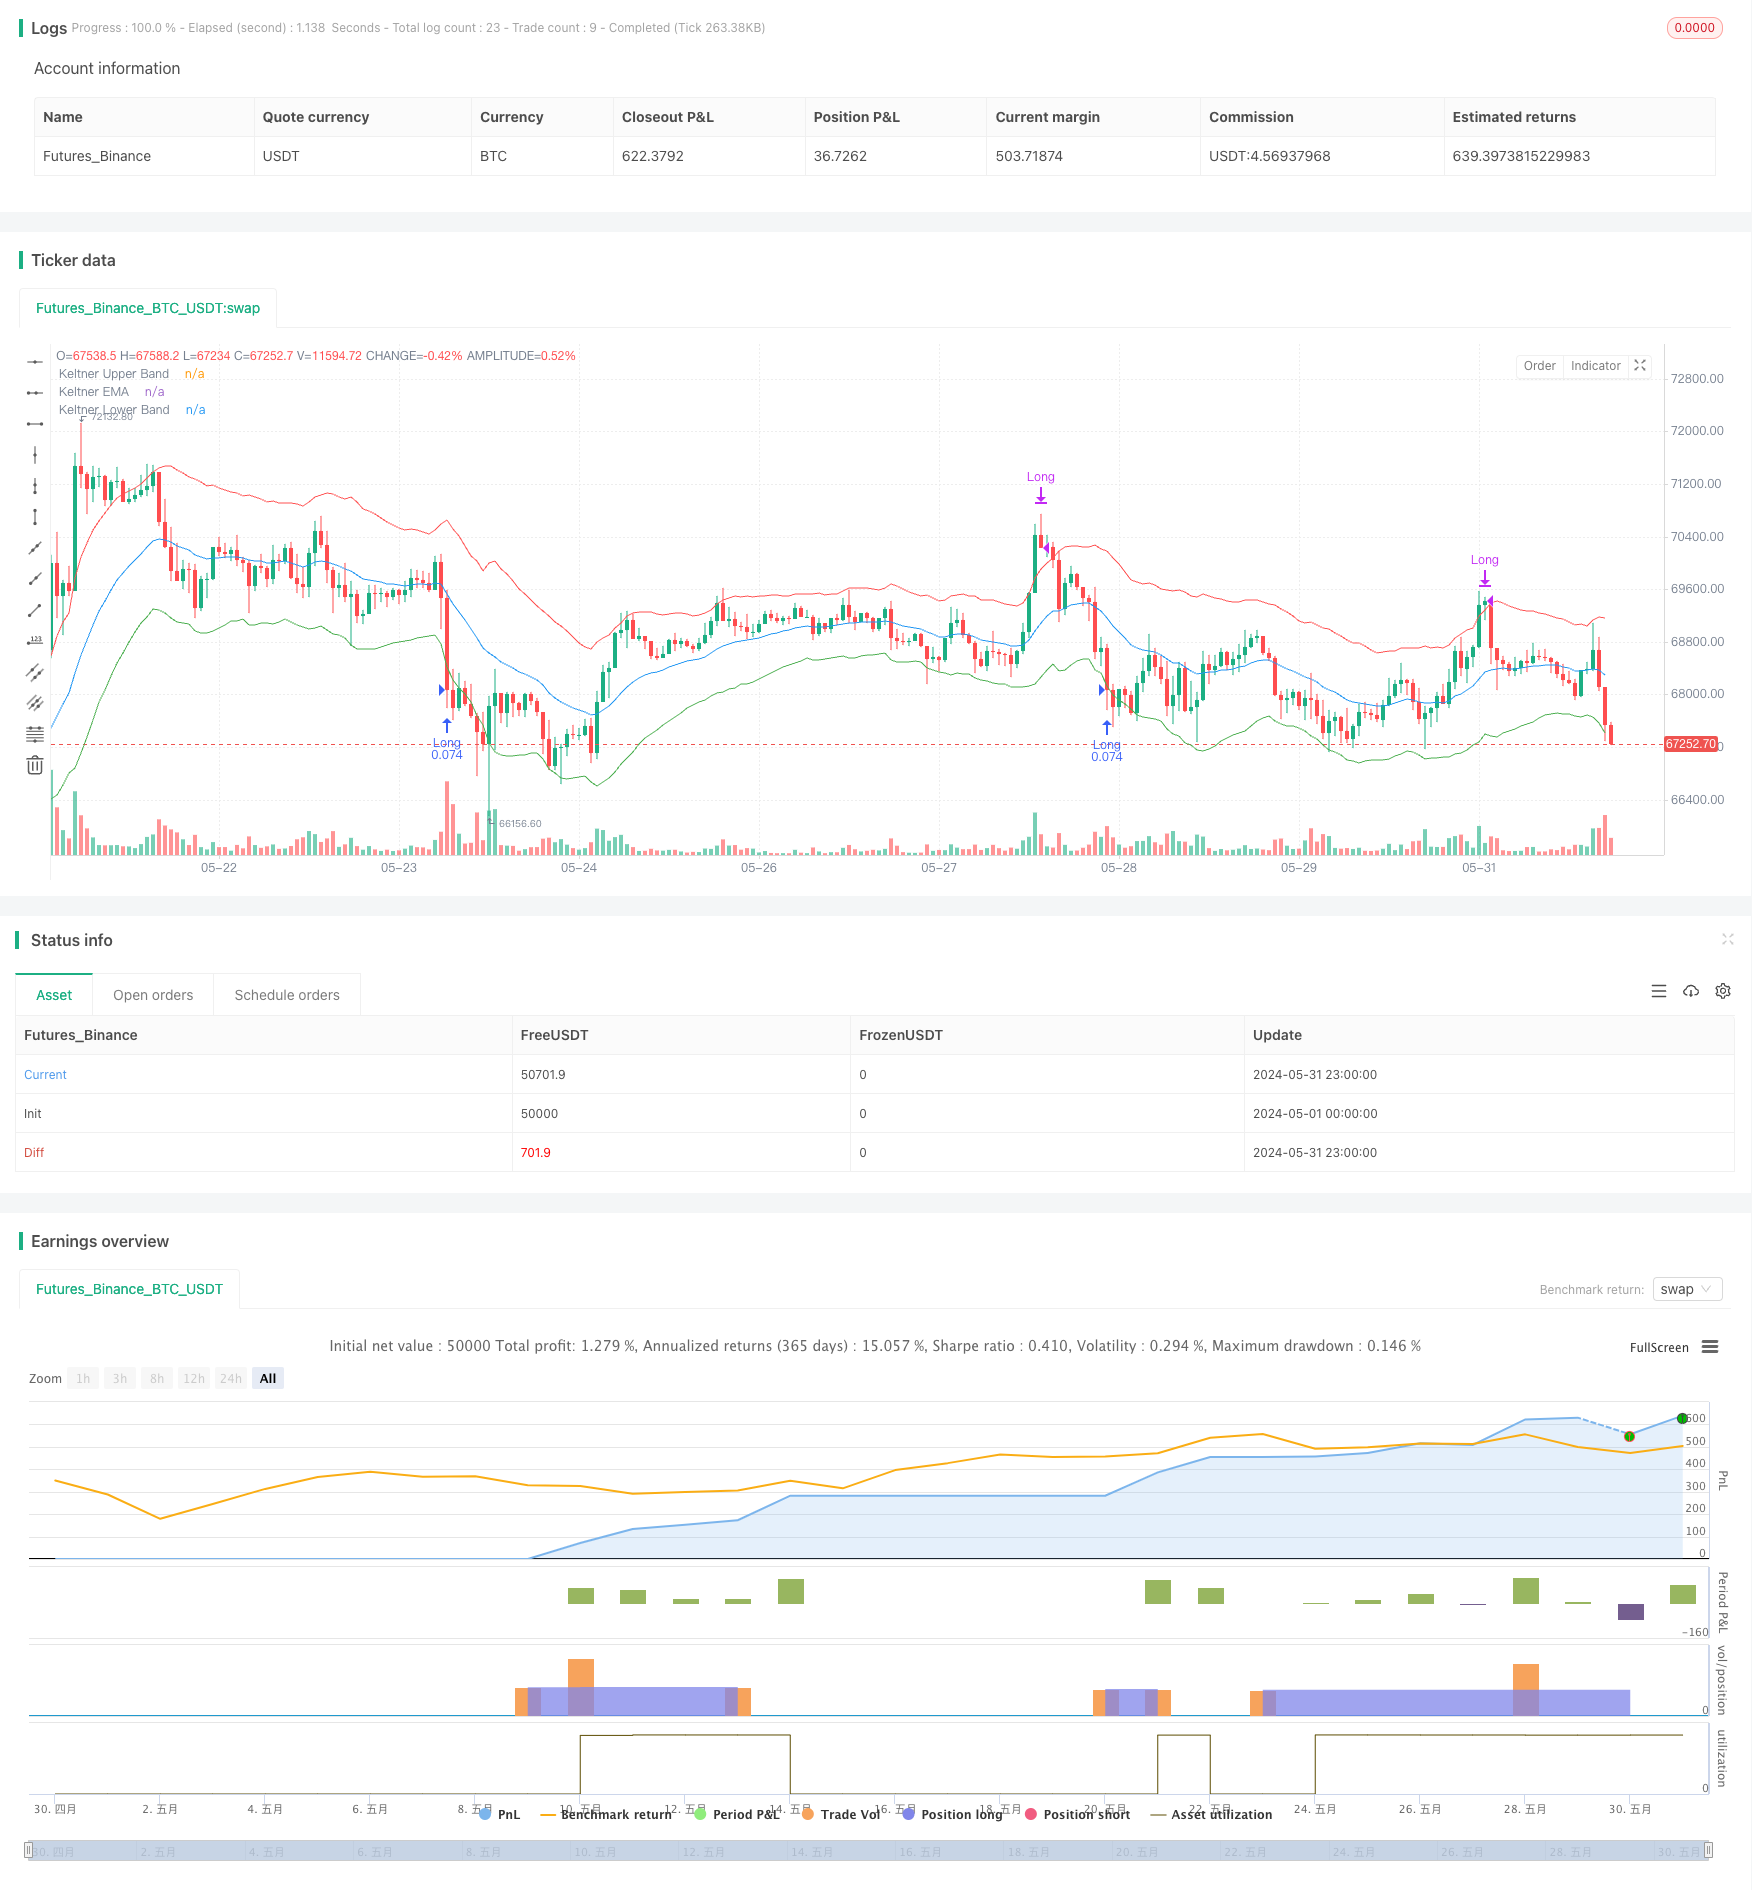 [trans]
概述
该策略基于Keltner通道指标,利用指数移动平均线(EMA)和平均真实波动幅度(ATR)构建上下通道,当价格突破下轨时开仓做多,当价格突破上轨时平仓。该策略试图捕捉价格的波动区间,在价格向上突破通道上轨时获利了结。
策略原理
- 计算指定周期的EMA作为Keltner通道的中轨。
- 计算指定周期的ATR,然后乘以一个倍数作为通道的上下轨道。
- 当收盘价跌破下轨时开仓做多,并记录开仓价格。
- 当开盘价突破上轨时平仓。
- 在开仓状态下,如果开盘价高于上轨,则平掉多单。
策略优势
- 能够自适应价格波动幅度。由于Keltner通道利用ATR构建上下轨,ATR能够衡量价格的波动率,因此在波动率较大时,通道宽度会相应增加,从而有效降低频繁交易带来的成本。
- 具有逻辑清晰简单,易于理解和实现的特点。该策略使用的指标简单,核心逻辑也比较容易把握。
- 具有一定的趋势跟踪能力。在上升趋势中,该策略能够持有多头头寸,直到价格突破上轨。
策略风险
- 缺乏明确的止损机制。该策略在开仓后并没有设置止损位,这可能导致在逆向行情中承受较大的回撤。
- 对突破信号的定义比较粗糙。仅仅使用收盘价跌破下轨和开盘价突破上轨作为开平仓信号,可能会产生一些误判,导致亏损交易。
- 策略参数的选择对结果有很大影响。EMA和ATR的周期选择以及ATR倍数的设置都会影响策略表现,但策略并未给出明确的参数优化方法。
策略优化方向
- 引入明确的止损机制。可以考虑在开仓时同时设置一个固定点数或百分比的止损位,从而控制单次交易的最大亏损。
- 优化信号的判断条件。可以考虑使用更多的价格信息来确认突破,比如要求收盘价连续数根K线低于下轨才开仓,避免单根K线的假突破。
- 进行参数优化。可以使用遗传算法等方法对EMA、ATR的周期以及ATR倍数进行优化,寻找更适合当前市场的参数组合。
- 增加过滤条件。可以考虑增加一些过滤信号,比如只在ADX高于某个阈值时才开仓,或者使用MA的多头排列作为趋势过滤等。
总结
该策略基于Keltner通道指标,利用价格突破上下轨的逻辑开展交易。它的优点是逻辑简单清晰,适应性强,缺点是缺乏止损和信号质量欠佳。未来可以从引入止损,优化信号,参数寻优和增加过滤条件等方面对策略进行完善。
||
Overview
This strategy is based on the Keltner Channels indicator, which uses the Exponential Moving Average (EMA) and Average True Range (ATR) to construct upper and lower channels. When the price breaks below the lower channel, it enters a long position, and when the price breaks above the upper channel, it closes the position. This strategy attempts to capture the price volatility range and takes profit when the price breaks above the upper channel.
Strategy Principles
- Calculate the EMA of a specified period as the middle line of the Keltner Channels.
- Calculate the ATR of a specified period, then multiply it by a factor to serve as the upper and lower channels.
- When the closing price falls below the lower channel, enter a long position and record the entry price.
- When the opening price breaks above the upper channel, close the position.
- If already in a position and the opening price is higher than the upper channel, close the long position.
Strategy Advantages
- Adaptability to price volatility. Since Keltner Channels use ATR to construct the upper and lower channels, and ATR measures price volatility, the channel width will increase accordingly when volatility is high, effectively reducing the cost of frequent trading.
- Clear logic, simplicity, and easy to understand and implement. The indicators used in this strategy are simple, and the core logic is relatively easy to grasp.
- Certain trend-following capability. In an uptrend, this strategy can hold a long position until the price breaks above the upper channel.
Strategy Risks
- Lack of explicit stop-loss mechanism. This strategy does not set a stop-loss after entering a position, which may lead to a large drawdown in adverse market conditions.
- Rough definition of breakout signals. Using only the closing price falling below the lower channel and the opening price breaking above the upper channel as entry and exit signals may produce some misjudgments, leading to losing trades.
- The choice of strategy parameters has a significant impact on the results. The selection of EMA and ATR periods and the setting of the ATR multiple will affect the strategy performance, but the strategy does not provide a clear parameter optimization method.
Strategy Optimization Directions
- Introduce an explicit stop-loss mechanism. Consider setting a stop-loss at a fixed number of points or percentage when entering a position to control the maximum loss of a single trade.
- Optimize the judgment conditions of signals. Consider using more price information to confirm the breakout, such as requiring the closing price to be below the lower channel for several consecutive candles before entering a position to avoid false breakouts.
- Perform parameter optimization. Use methods such as genetic algorithms to optimize the periods of EMA and ATR and the ATR multiple to find the parameter combination that is more suitable for the current market.
- Add filtering conditions. Consider adding some filtering signals, such as only entering a position when ADX is above a certain threshold or using the MA bullish crossover as a trend filter.
Summary
This strategy is based on the Keltner Channels indicator and conducts trades based on the logic of price breaking above or below the channels. Its advantages are simple and clear logic and strong adaptability. Its disadvantages are the lack of stop-loss and poor signal quality. In the future, the strategy can be improved by introducing stop-loss, optimizing signals, parameter optimization, and adding filtering conditions. [/trans]
Source (PineScript)
/*backtest
start: 2024-05-01 00:00:00
end: 2024-05-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © satrusskumar

//@version=5

// Input parameters
length = input.int(21, title="EMA Length")
mult = input.float(2, title="ATR Multiplier")
atrLength = input.int(13, title="ATR Length")

// Calculate Keltner Channels
ema = ta.ema(close, length)
atr = ta.atr(atrLength)
upper_band = ema + mult * atr
lower_band = ema - mult * atr

// Plot Keltner Channels
plot(upper_band, color=color.red, title="Keltner Upper Band")
plot(ema, color=color.blue, title="Keltner EMA")
plot(lower_band, color=color.green, title="Keltner Lower Band")

// Strategy logic
var float entry_price = na
var bool in_trade = false

if (not in_trade and close < lower_band)
    strategy.entry("Long", strategy.long)
    entry_price := close
    in_trade := true

if (in_trade and open > upper_band)
    strategy.close("Long")
    in_trade := false
// Strategy settings
strategy("Keltner Channel Strategy", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=10)
Detail
https://www.fmz.com/strategy/453223
Last Modified
2024-06-03 10:39:20