
18 KiB
Name
多维度EMA趋势追踪与成交量波动率确认策略-Multi-Dimensional-EMA-Trend-Following-with-Volume-and-Volatility-Confirmation-Strategy
Author
ianzeng123
Strategy Description
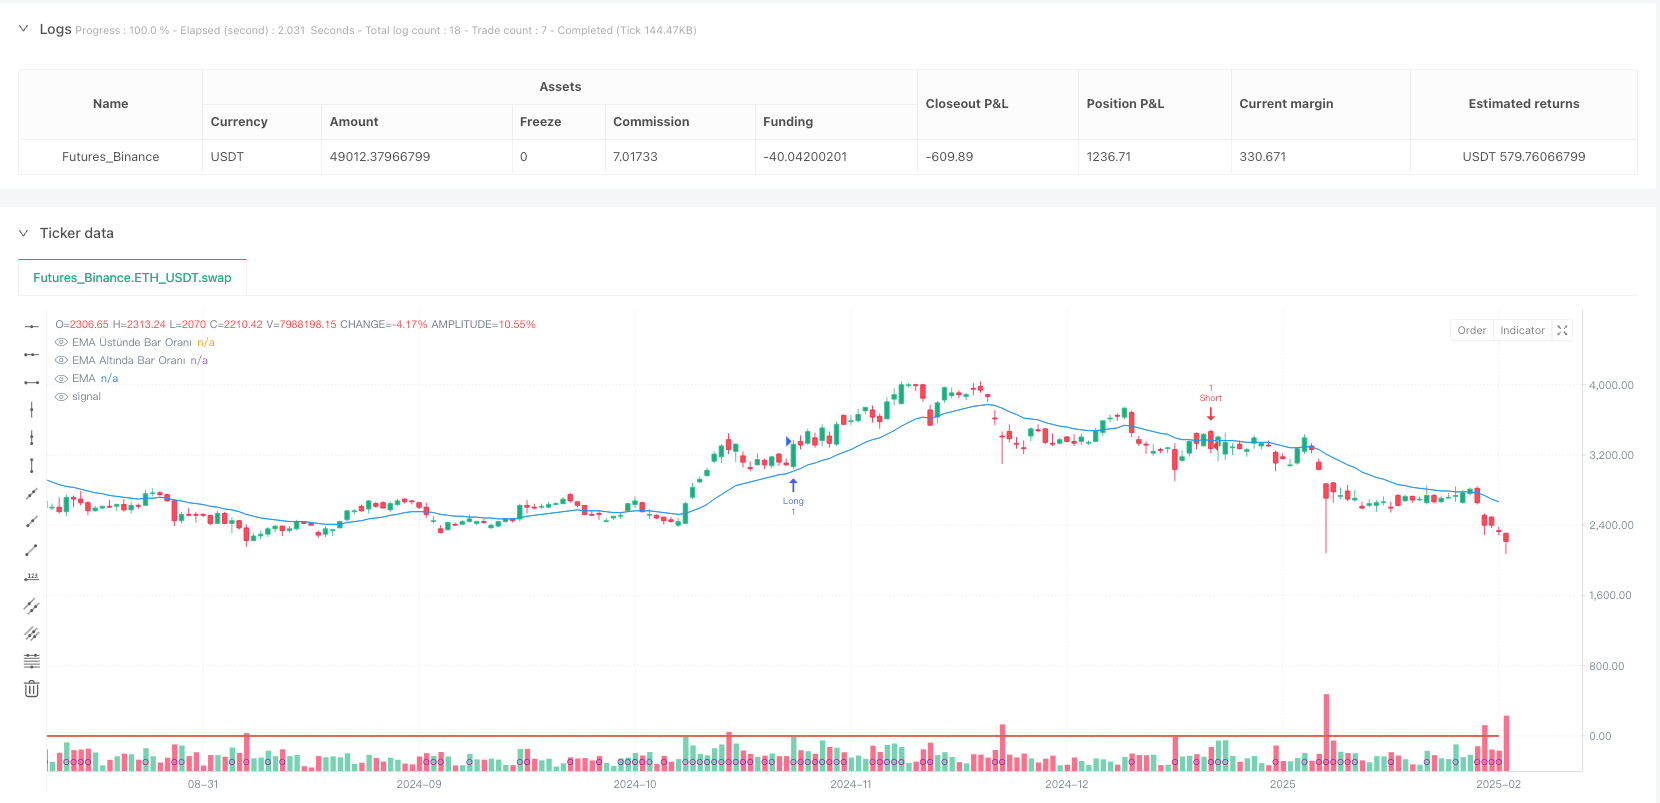
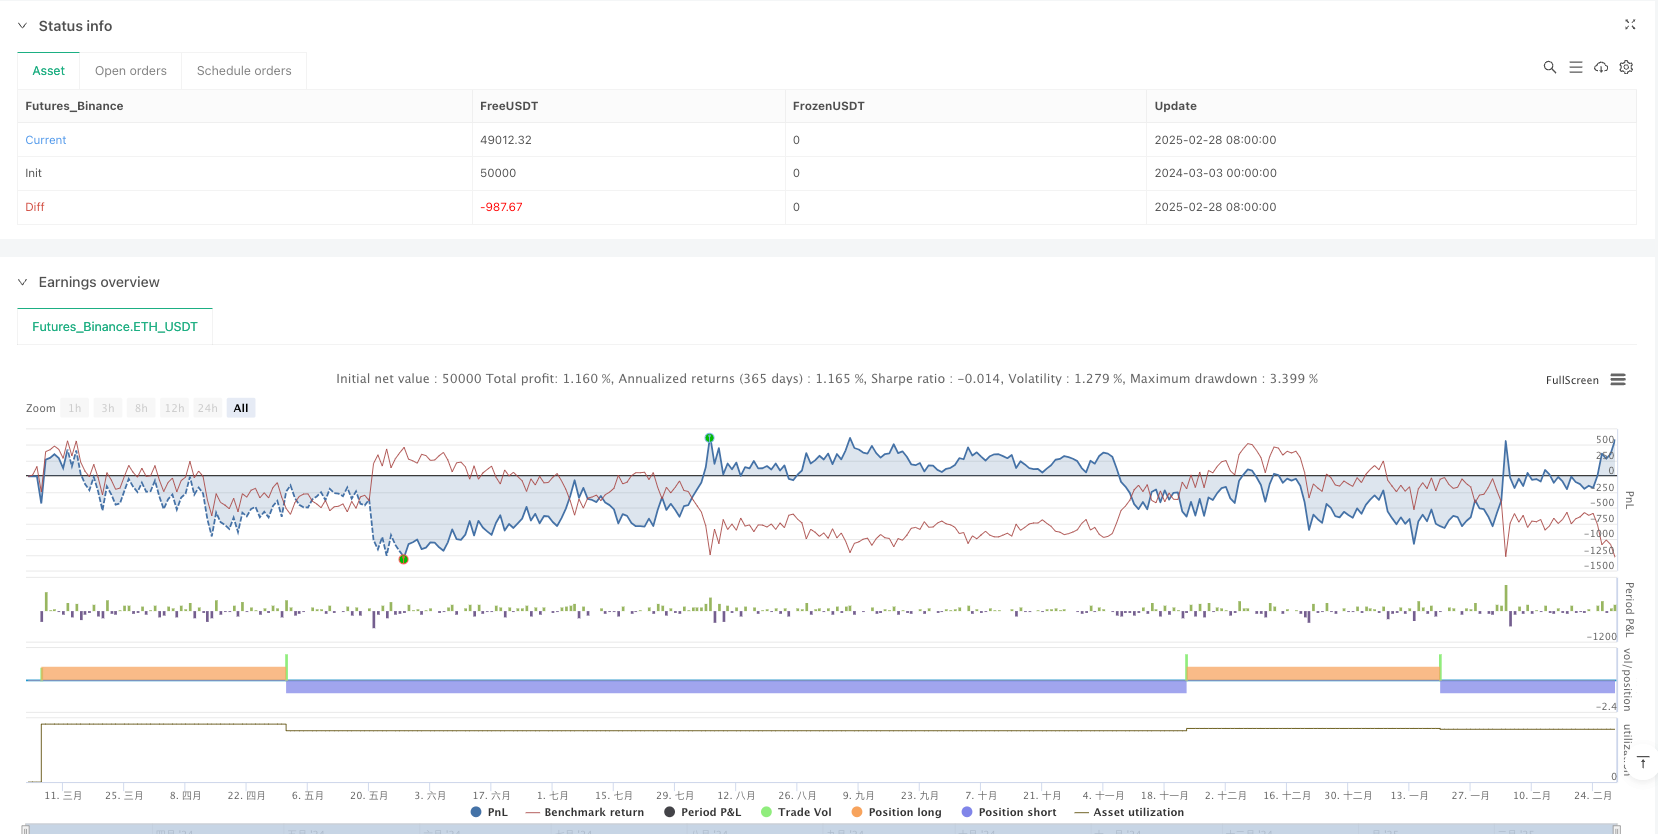
[trans]
概述
多维度EMA趋势追踪与成交量波动率确认策略是一种结合指数移动平均线(EMA)、成交量分析和波动率过滤的综合量化交易系统。该策略通过观察价格与EMA的相对位置关系、历史价格趋势统计、成交量突破和ATR波动率确认来识别潜在的趋势入场机会。策略核心思想是在价格形成明确趋势、交易量增加且市场波动性适中的条件下进行交易,从而提高交易成功率和盈利能力。
策略原理
该策略的运作原理基于四个关键组件:
- EMA趋势识别:策略使用用户自定义长度的指数移动平均线(EMA)作为基准线,通过比较收盘价与EMA的位置关系来判断当前趋势方向。
- 历史趋势强度分析:策略计算在回溯期间(lookbackBars)内,收盘价位于EMA上方和下方的比例,从而确定趋势的持续性和强度。当超过50%的K线收盘价位于EMA上方时,被视为上升趋势;反之则被视为下降趋势。
- 成交量确认:策略要求当前成交量必须超过回溯期间内平均成交量的特定倍数(volMultiplier),以确保有足够的市场参与度支撑价格走势。
- 波动率过滤:策略使用平均真实范围(ATR)指标来衡量市场波动性,要求当前ATR相对于收盘价的百分比必须超过预设阈值,以确保市场有足够的波动性来产生有效信号。
策略的买入信号产生条件:
- 回溯期间内超过50%的K线收盘价位于EMA上方
- 当前K线收盘价位于EMA上方
- 当前成交量大于平均成交量乘以设定倍数
- 当前ATR百分比大于波动率阈值
策略的卖出信号产生条件:
- 回溯期间内超过50%的K线收盘价位于EMA下方
- 当前K线收盘价位于EMA下方
- 当前成交量大于平均成交量乘以设定倍数
- 当前ATR百分比大于波动率阈值
策略优势
- 多重确认机制:该策略不仅关注价格趋势,还结合成交量和波动率指标进行多重确认,减少了假突破信号,提高了交易质量。
- 趋势持续性评估:通过统计历史K线与EMA的相对位置,策略能够评估趋势的持续性和强度,避免在趋势弱时入场。
- 适应性与灵活性:策略提供多个可调参数(EMA长度、回溯周期、成交量倍数、ATR周期和阈值),使用户可以根据不同市场环境和交易品种进行优化。
- 可视化支持:策略提供EMA线、趋势强度比例和成交量条件达成指示等可视化元素,帮助交易者更直观地理解市场状况和策略逻辑。
- 过滤低流动性环境:通过成交量条件,策略自动过滤低流动性环境,降低滑点风险和假信号可能性。
- 波动率适应性:通过ATR波动率过滤,策略能够在市场波动合理的情况下进行交易,避免在过度平静或过度波动的市场环境中产生不良信号。
策略风险
- 趋势反转风险:虽然策略使用多重确认机制,但在趋势快速反转时仍可能产生滞后,导致入场或出场时机不佳。解决方法:可以考虑添加更快速的反转指标或设置止损策略来限制损失。
- 参数优化过拟合:过度优化策略参数可能导致过拟合历史数据,而在实际交易中表现不佳。解决方法:应采用跨市场、跨时段的参数稳健性测试,并保持参数设置的合理性。
- 低波动环境表现:在市场波动性极低的环境中,策略可能长时间不产生交易信号,影响资金利用效率。解决方法:可以针对不同波动率环境设置不同的参数配置,或结合其他类型的策略形成组合策略。
- 成交量异常干扰:异常大的成交量峰值(如重大新闻发布后)可能导致错误信号。解决方法:可以考虑使用成交量的标准差或其他统计方法来过滤异常值。
- 参数敏感性:EMA长度、回溯周期等参数的微小变化可能导致策略表现差异较大。解决方法:进行参数敏感性分析,选择在参数小幅变化时性能仍相对稳定的配置。
- 市场环境适应性:策略在不同市场环境(如趋势市、震荡市)中表现可能不一致。解决方法:可以添加市场环境识别功能,在不同环境下应用不同的交易规则或参数设置。
策略优化方向
- 自适应参数:将EMA长度、回溯周期等关键参数设计为自适应的,根据市场波动性和趋势强度自动调整。这样可以提高策略在不同市场环境中的适应性,减少人为参数调整的需要。
- 止损机制完善:添加智能止损机制,如基于ATR的动态止损或基于策略信号反转的条件止损,以保护已有利润并限制单笔交易损失。
- 市场环境分类:增加市场环境分类逻辑,如区分趋势市和震荡市,并在不同环境下应用不同的交易规则或参数配置,提高策略的环境适应性。
- 多时间框架分析:引入多时间框架分析,仅在更高时间框架趋势方向与当前时间框架一致时进行交易,提高趋势判断的准确性。
- 成交量分析优化:细化成交量分析方法,如考虑成交量的增长率、连续性等特征,而不仅是简单比较与平均值的关系,以获得更精准的成交量确认信号。
- 机器学习增强:尝试引入机器学习算法来优化信号生成过程,如通过历史数据训练模型来预测哪些条件组合更可能导致成功交易。
- 交易规模动态调整:基于信号强度(如趋势比例与阈值的差距、成交量超出平均值的程度等)动态调整交易规模,在更强信号时增加仓位,提高资金利用效率。
- 相关性过滤:增加与相关市场或指数的相关性分析,仅在相关性支持的情况下进行交易,减少由市场广泛因素引起的假信号。
总结
多维度EMA趋势追踪与成交量波动率确认策略是一个结合价格趋势、历史模式、成交量和波动率多重维度分析的综合交易系统。通过同时考虑价格相对于EMA的位置、历史趋势强度、成交量突破和波动率确认,该策略能够有效地识别具有持续性潜力的趋势入场机会。
策略的核心优势在于其多重确认机制和灵活的参数配置,使其能够适应不同市场环境。然而,策略也面临着参数优化、市场环境适应性和信号滞后等挑战。通过引入自适应参数、完善止损机制、增加市场环境分类和多时间框架分析等优化措施,策略的稳健性和盈利能力有望进一步提升。
对于量化交易者而言,该策略提供了一个坚实的基础框架,可以根据个人交易风格和目标市场特性进行进一步定制和优化。通过理解策略背后的原理和逻辑,交易者能够更好地把握市场趋势机会,提高交易决策的质量和一致性。 ||
Overview
The Multi-Dimensional EMA Trend Following with Volume and Volatility Confirmation Strategy is a comprehensive quantitative trading system that combines Exponential Moving Average (EMA), volume analysis, and volatility filtering. The strategy identifies potential trend entry opportunities by observing the relative position of price to EMA, historical price trend statistics, volume breakouts, and ATR volatility confirmation. The core idea is to execute trades when a clear price trend is forming, trading volume is increasing, and market volatility is moderate, thereby improving trade success rate and profitability.
Strategy Principles
The strategy operates based on four key components:
- EMA Trend Identification: The strategy uses an Exponential Moving Average (EMA) of user-defined length as a baseline and determines the current trend direction by comparing closing prices to the EMA.
- Historical Trend Strength Analysis: The strategy calculates the proportion of closing prices above and below the EMA during the lookback period (lookbackBars) to determine trend persistence and strength. When more than 50% of candles close above the EMA, it's considered an uptrend; conversely, it's considered a downtrend.
- Volume Confirmation: The strategy requires current volume to exceed a specific multiple (volMultiplier) of the average volume during the lookback period, ensuring sufficient market participation to support price movements.
- Volatility Filtering: The strategy uses the Average True Range (ATR) indicator to measure market volatility, requiring the current ATR percentage relative to closing price to exceed a preset threshold, ensuring the market has sufficient volatility to generate valid signals.
Buy signal conditions:
- More than 50% of candles in the lookback period close above the EMA
- Current candle closes above the EMA
- Current volume is greater than average volume multiplied by the set multiplier
- Current ATR percentage is greater than the volatility threshold
Sell signal conditions:
- More than 50% of candles in the lookback period close below the EMA
- Current candle closes below the EMA
- Current volume is greater than average volume multiplied by the set multiplier
- Current ATR percentage is greater than the volatility threshold
Strategy Advantages
- Multiple Confirmation Mechanism: The strategy not only focuses on price trends but also incorporates volume and volatility indicators for multiple confirmations, reducing false breakout signals and improving trade quality.
- Trend Persistence Assessment: By tracking the historical candles' position relative to the EMA, the strategy can evaluate trend persistence and strength, avoiding entry during weak trends.
- Adaptability and Flexibility: The strategy provides multiple adjustable parameters (EMA length, lookback period, volume multiplier, ATR period, and threshold), allowing users to optimize according to different market environments and trading instruments.
- Visualization Support: The strategy provides visual elements such as the EMA line, trend strength ratio, and volume condition indicators, helping traders understand market conditions and strategy logic more intuitively.
- Low Liquidity Environment Filtering: Through volume conditions, the strategy automatically filters low liquidity environments, reducing slippage risk and the possibility of false signals.
- Volatility Adaptability: Through ATR volatility filtering, the strategy can trade in markets with reasonable volatility, avoiding poor signals in excessively calm or volatile market environments.
Strategy Risks
- Trend Reversal Risk: Although the strategy uses multiple confirmation mechanisms, it may still lag during rapid trend reversals, leading to suboptimal entry or exit timing. Solution: Consider adding faster reversal indicators or setting stop-loss strategies to limit losses.
- Parameter Optimization Overfitting: Excessive optimization of strategy parameters may lead to overfitting historical data, performing poorly in actual trading. Solution: Conduct parameter robustness tests across markets and time periods, maintaining reasonable parameter settings.
- Low Volatility Environment Performance: In extremely low volatility environments, the strategy may not generate trading signals for extended periods, affecting capital utilization efficiency. Solution: Set different parameter configurations for different volatility environments or combine with other types of strategies.
- Volume Anomaly Interference: Abnormally large volume spikes (such as after major news releases) may cause erroneous signals. Solution: Consider using volume standard deviation or other statistical methods to filter outliers.
- Parameter Sensitivity: Small changes in parameters like EMA length and lookback period may cause significant differences in strategy performance. Solution: Conduct parameter sensitivity analysis, selecting configurations that remain relatively stable in performance despite small parameter changes.
- Market Environment Adaptability: Strategy performance may be inconsistent across different market environments (such as trending vs. range-bound markets). Solution: Add market environment identification functionality to apply different trading rules or parameter settings in different environments.
Strategy Optimization Directions
- Adaptive Parameters: Design key parameters such as EMA length and lookback period to be adaptive, automatically adjusting based on market volatility and trend strength. This improves strategy adaptability across different market environments, reducing the need for manual parameter adjustments.
- Stop-Loss Mechanism Improvement: Add intelligent stop-loss mechanisms, such as ATR-based dynamic stop-loss or condition-based stop-loss triggered by strategy signal reversal, to protect existing profits and limit single trade losses.
- Market Environment Classification: Add market environment classification logic, such as distinguishing between trending and range-bound markets, and apply different trading rules or parameter configurations in different environments to improve strategy adaptability.
- Multi-Timeframe Analysis: Introduce multi-timeframe analysis, trading only when the higher timeframe trend direction aligns with the current timeframe, improving trend judgment accuracy.
- Volume Analysis Optimization: Refine volume analysis methods by considering characteristics such as volume growth rate and continuity, rather than simply comparing to average values, to obtain more precise volume confirmation signals.
- Machine Learning Enhancement: Attempt to incorporate machine learning algorithms to optimize signal generation, such as training models on historical data to predict which condition combinations are more likely to lead to successful trades.
- Dynamic Trade Sizing: Dynamically adjust trade size based on signal strength (such as the difference between trend ratio and threshold, the extent volume exceeds average, etc.), increasing position size with stronger signals to improve capital utilization efficiency.
- Correlation Filtering: Add correlation analysis with related markets or indices, trading only when supported by correlations, reducing false signals caused by broad market factors.
Summary
The Multi-Dimensional EMA Trend Following with Volume and Volatility Confirmation Strategy is a comprehensive trading system that combines price trend, historical pattern, volume, and volatility analysis across multiple dimensions. By simultaneously considering price position relative to EMA, historical trend strength, volume breakouts, and volatility confirmation, the strategy can effectively identify trend entry opportunities with continuation potential.
The core advantage of the strategy lies in its multiple confirmation mechanisms and flexible parameter configuration, allowing it to adapt to different market environments. However, the strategy also faces challenges in parameter optimization, market environment adaptability, and signal lag. By introducing adaptive parameters, improving stop-loss mechanisms, adding market environment classification, and multi-timeframe analysis, the strategy's robustness and profitability can be further enhanced.
For quantitative traders, this strategy provides a solid framework that can be further customized and optimized according to individual trading styles and target market characteristics. By understanding the principles and logic behind the strategy, traders can better capitalize on market trend opportunities and improve the quality and consistency of trading decisions.[/trans]
Source (PineScript)
/*backtest
start: 2024-03-03 00:00:00
end: 2025-03-01 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"ETH_USDT"}]
*/

//@version=5
strategy("EMA, Hacim ve Volatilite Stratejisi", overlay=true, initial_capital=10000, currency=currency.USD)

// Kullanıcı girdileri
emaLength           = input.int(20, "EMA Uzunluğu", minval=1)
lookbackBars        = input.int(50, "Bakış Periyodu (Bar Sayısı)", minval=1)
volMultiplier       = input.float(1.0, "Hacim Çarpanı (Ortalama Hacim x)", step=0.1)
atrPeriod           = input.int(14, "ATR Periyodu", minval=1)
atrPercentThreshold = input.float(0.01, "ATR Yüzde Eşiği (Örn: 0.01 = %1)", step=0.001)

// EMA hesaplaması
emaSeries = ta.ema(close, emaLength)
plot(emaSeries, color=color.blue, title="EMA")

// Son lookbackBars barı içerisinde, kapanışın EMA'nın üzerinde olduğu bar sayısını hesaplamak için döngü
barsAboveEMA = 0.0
for i = 0 to lookbackBars - 1
    barsAboveEMA := barsAboveEMA + (close[i] > emaSeries[i] ? 1.0 : 0.0)
ratioAbove = barsAboveEMA / lookbackBars

// Son lookbackBars barı içerisinde, kapanışın EMA'nın altında olduğu bar sayısını hesaplamak için döngü
barsBelowEMA = 0.0
for i = 0 to lookbackBars - 1
    barsBelowEMA := barsBelowEMA + (close[i] < emaSeries[i] ? 1.0 : 0.0)
ratioBelow = barsBelowEMA / lookbackBars

// Hacim filtresi: Mevcut barın hacmi, lookbackBars süresince hesaplanan ortalama hacmin volMultiplier katından yüksek olmalı
avgVolume       = ta.sma(volume, lookbackBars)
volumeCondition = volume > volMultiplier * avgVolume

// Volatilite filtresi: ATR değerinin, kapanışa oranı belirlenen eşikten yüksek olmalı
atrValue            = ta.atr(atrPeriod)
atrPercent          = atrValue / close
volatilityCondition = atrPercent > atrPercentThreshold

// Long ve Short giriş koşulları:
// Long: lookbackBars barının %50'sinden fazlası EMA üzerinde ve son barın kapanışı EMA üzerinde; hacim ve volatilite şartları sağlanmalı
longCondition = (ratioAbove > 0.5) and (close > emaSeries) and volumeCondition and volatilityCondition

// Short: lookbackBars barının %50'sinden fazlası EMA altında ve son barın kapanışı EMA altında; hacim ve volatilite şartları sağlanmalı
shortCondition = (ratioBelow > 0.5) and (close < emaSeries) and volumeCondition and volatilityCondition

// Ekstra görselleştirmeler
plot(ratioAbove, color=color.green, title="EMA Üstünde Bar Oranı", linewidth=2)
plot(ratioBelow, color=color.red, title="EMA Altında Bar Oranı", linewidth=2)
plotshape(volumeCondition, title="Hacim Şartı", style=shape.circle, location=location.bottom, color=color.purple, size=size.tiny)

// İşlem sinyalleri
if longCondition
    strategy.entry("Long", strategy.long)
if shortCondition
    strategy.entry("Short", strategy.short)
Detail
https://www.fmz.com/strategy/484581
Last Modified
2025-03-03 09:59:19