
24 KiB
Name
多维度短期趋势预测策略技术分析与波动性自适应交易方法Multi-Dimensional-Short-Term-Trend-Predictor-Technical-Analysis-and-Volatility-Adaptive-Trading-Strategy
Author
ianzeng123
Strategy Description
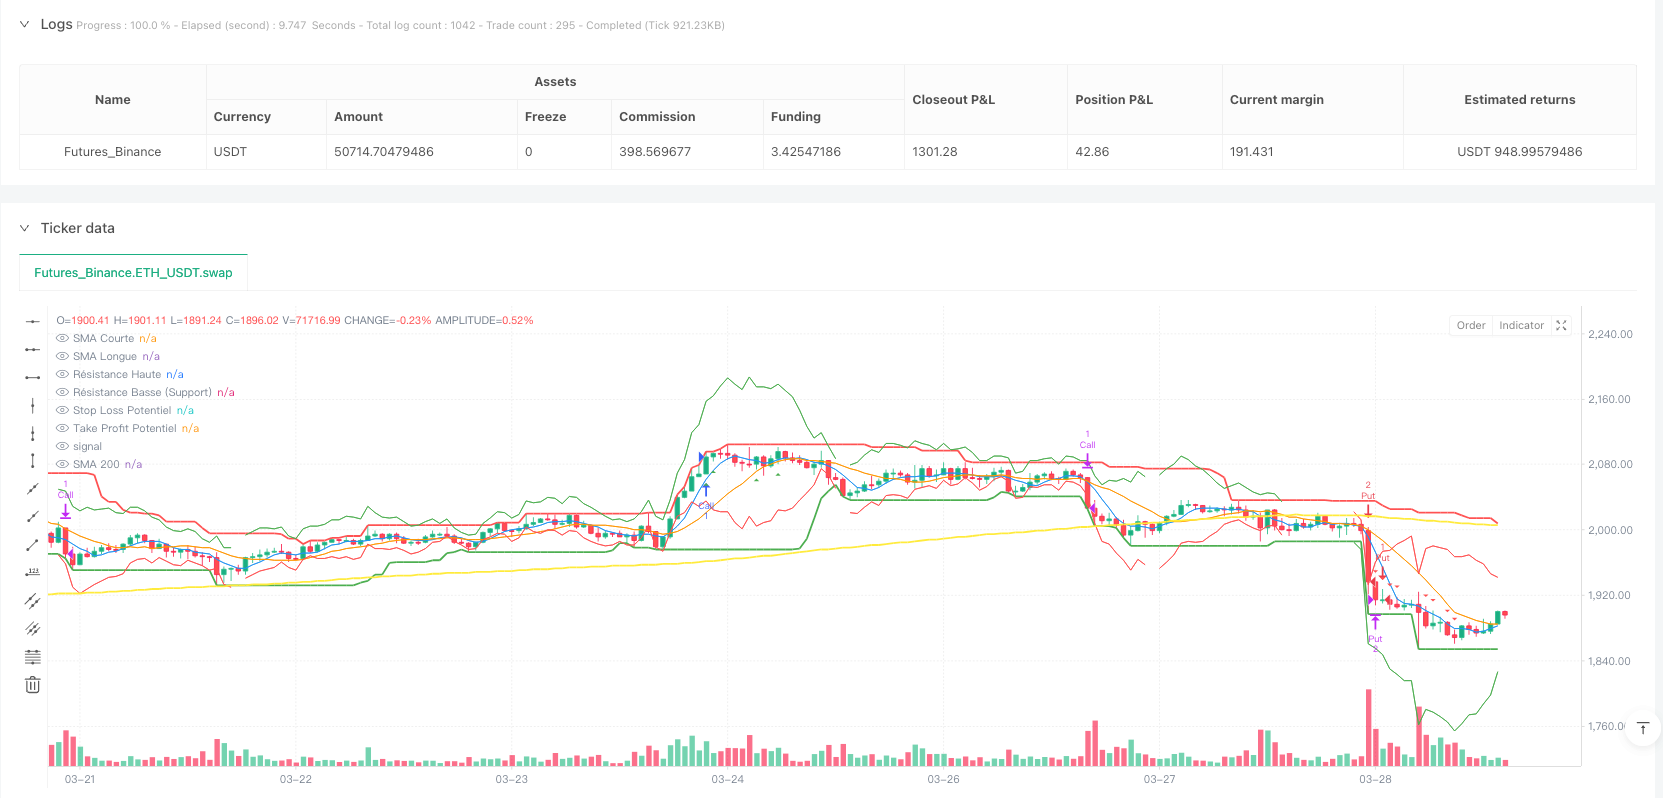
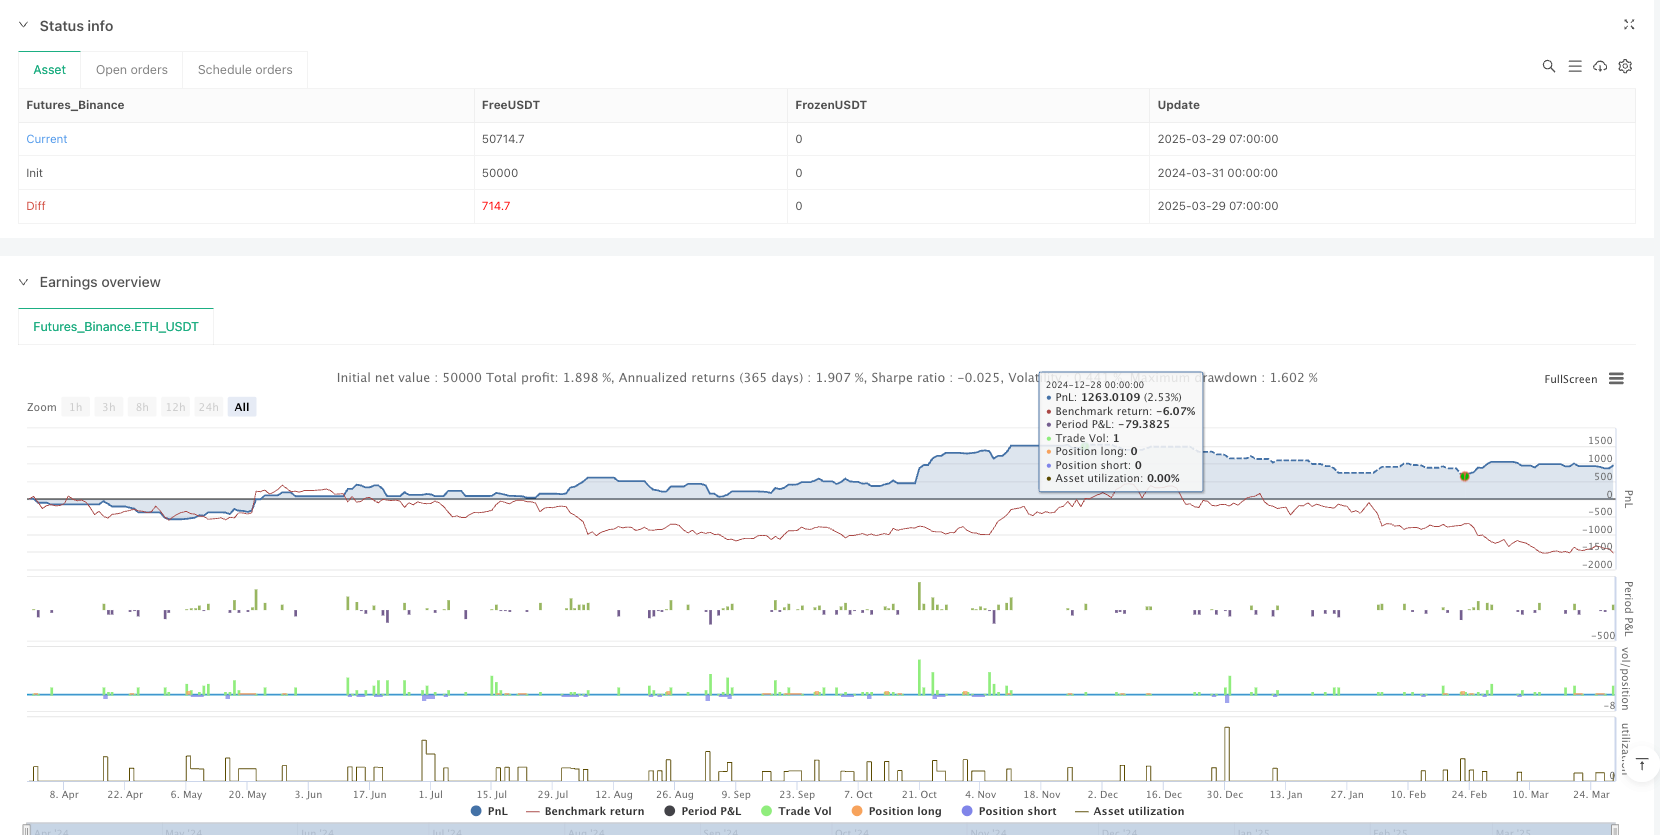
[trans]
概述
本策略是一种多维度短期趋势预测策略,专注于利用多个技术指标的协同效应来识别和预测金融市场中的短期趋势变化。该策略整合了简单移动平均线(SMA)、相对强弱指数(RSI)、平均方向指数(ADX)、平均真实波动范围(ATR)、移动平均线差指标(MACD)和随机振荡器(Stochastic)等关键技术分析工具,旨在提高交易信号的准确性和可靠性。
策略原理
该策略的核心原理基于多重技术指标的协同分析和趋势确认机制。通过综合考虑以下关键因素来生成交易信号:
- 短期和长期移动平均线的交叉
- RSI的超买超卖状态
- MACD线和信号线的变化
- 随机振荡器的动量指标
- ADX趋势强度
- 200周期移动平均线的整体市场趋势
- 最近的市场波动性
策略通过动态计算潜在入场点、止损和止盈水平,并根据最近的市场波动性调整这些关键参数,从而实现风险管理和交易执行。
策略优势
- 多指标综合分析:通过整合多个技术指标,降低了单一指标可能带来的误判风险
- 动态风险管理:基于ATR的止损和止盈机制,能够根据市场波动性调整仓位
- 灵活的时间框架:支持从5分钟到4小时不同的交易周期
- 自适应仓位规模:根据可用资本和每笔交易风险百分比动态调整仓位大小
- 趋势强度确认:通过ADX指标确认趋势的有效性,避免在震荡市场中频繁交易
策略风险
- 多指标复杂性可能导致信号生成的延迟
- 在高度不稳定的市场环境中,指标可能给出相互矛盾的信号
- 回测结果可能不完全代表未来实际交易表现
- 杠杆交易可能显著放大损失
- 没有考虑基本面因素和突发市场事件
策略优化方向
- 引入机器学习算法,动态调整指标权重
- 增加更多基本面和情绪指标
- 开发更智能的仓位管理算法
- 针对不同市场和资产类型定制个性化参数
- 集成实时新闻和社交媒体情绪分析
总结
这是一种多维度、数据驱动的短期趋势预测策略,通过复杂的技术指标组合和动态风险管理机制,旨在提高交易决策的准确性和可靠性。尽管策略具有显著的理论优势,但实际应用中仍需谨慎,并持续进行回测和优化。
||
Overview
This strategy is a multi-dimensional short-term trend prediction approach focusing on leveraging the synergistic effects of multiple technical indicators to identify and predict short-term trend changes in financial markets. By integrating key technical analysis tools such as Simple Moving Averages (SMA), Relative Strength Index (RSI), Average Directional Index (ADX), Average True Range (ATR), Moving Average Convergence Divergence (MACD), and Stochastic Oscillator, the strategy aims to enhance the accuracy and reliability of trading signals.
Strategy Principles
The core principle of this strategy is based on synergistic technical indicator analysis and trend confirmation mechanisms. Trading signals are generated by comprehensively considering the following key factors:
- Short-term and long-term moving average crossovers
- RSI overbought/oversold states
- MACD line and signal line changes
- Stochastic oscillator momentum indicators
- ADX trend strength
- Overall market trend via 200-period moving average
- Recent market volatility
The strategy dynamically calculates potential entry points, stop-loss, and take-profit levels, adjusting these critical parameters based on recent market volatility to achieve risk management and trade execution.
Strategy Advantages
- Multi-indicator comprehensive analysis: Integrating multiple technical indicators reduces the risk of misjudgment from single indicators
- Dynamic risk management: ATR-based stop-loss and take-profit mechanisms adapt to market volatility
- Flexible timeframe: Supports trading cycles from 5 minutes to 4 hours
- Adaptive position sizing: Dynamically adjusts position size based on available capital and per-trade risk percentage
- Trend strength confirmation: Using ADX to validate trend effectiveness, avoiding frequent trading in ranging markets
Strategy Risks
- Complexity of multiple indicators may cause signal generation delays
- Potential contradictory signals in highly unstable market environments
- Backtesting results may not fully represent actual future trading performance
- Leveraged trading can significantly amplify losses
- Lack of consideration for fundamental factors and unexpected market events
Strategy Optimization Directions
- Introduce machine learning algorithms for dynamic indicator weight adjustment
- Incorporate more fundamental and sentiment indicators
- Develop more intelligent position management algorithms
- Customize personalized parameters for different markets and asset classes
- Integrate real-time news and social media sentiment analysis
Conclusion
This is a multi-dimensional, data-driven short-term trend prediction strategy that aims to improve trading decision accuracy and reliability through complex technical indicator combinations and dynamic risk management mechanisms. Despite its theoretical advantages, practical application requires caution and continuous backtesting and optimization.[/trans]
Source (PineScript)
/*backtest
start: 2024-03-31 00:00:00
end: 2025-03-29 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"ETH_USDT"}]
*/

// © HugoMora
//@version=5
strategy("Short-Term Trend Predictor: Call/Put (5min to 4hr)", overlay=true)

// --- 1. Paramètres (Inputs) ---
// Info-bulle pour short_length
short_length = input.int(5, title="Période SMA Courte", minval=1, tooltip = "Période de la moyenne mobile courte. Utilisée pour identifier les tendances à court terme.")
long_length = input.int(13, title="Période SMA Longue", minval=1, tooltip = "Période de la moyenne mobile longue. Utilisée pour confirmer les tendances à plus long terme.")
rsi_length = input.int(14, title="Période RSI", minval=1, tooltip = "Période de l'indice de force relative (RSI). Mesure la vitesse et l'ampleur des mouvements de prix récents pour évaluer les conditions de surachat ou de survente.")
sma200_length = input.int(200, title="Période SMA 200", minval=1, tooltip = "Période de la moyenne mobile sur 200 périodes. Utilisée pour déterminer la tendance générale du marché (haussière ou baissière).")
resistance_length = input.int(20, title="Période Résistance", minval=1, tooltip="Nombre de périodes utilisées pour calculer les niveaux de résistance et de support.")
macd_fast = input.int(12, title="Longueur Rapide MACD", tooltip = "Période plus courte utilisée dans le calcul de la ligne MACD. Représente les mouvements de prix à court terme.")
macd_slow = input.int(26, title="Longueur Lente MACD", tooltip = "Période plus longue utilisée dans le calcul de la ligne MACD. Représente les mouvements de prix à long terme.")
macd_signal = input.int(9, title="Période Signal MACD", tooltip = "Période de la SMA de la ligne MACD, utilisée comme signal d'achat ou de vente.")
stoch_k = input.int(14, title="Longueur %K Stoch", tooltip = "Période utilisée pour calculer la ligne %K du Stochastic Oscillator, indiquant où le prix de clôture se situe par rapport à la fourchette haute-basse sur cette période.")
stoch_d = input.int(3, title="Longueur %D Stoch", tooltip = "Période utilisée pour calculer la ligne %D, qui est une moyenne mobile de %K. Utilisée pour lisser les fluctuations de %K.")
adx_length = input.int(14, title="Longueur ADX", tooltip = "Période utilisée pour calculer l'Average Directional Index (ADX), qui mesure la force de la tendance.")
adx_smooth = input.int(14, title="Lissage ADX", tooltip = "Période utilisée pour lisser la ligne ADX, réduisant le bruit et fournissant une mesure plus stable de la force de la tendance.")
atrLength = input.int(14, title="Longueur ATR", tooltip = "Période utilisée pour calculer l'Average True Range (ATR), qui mesure la volatilité du marché.")
atrMultiplierSL = input.float(2.0, title="Multiplicateur ATR Stop Loss", minval=0.1, tooltip = "Multiplicateur de l'ATR pour déterminer le niveau de Stop Loss. Un multiplicateur plus élevé signifie un Stop Loss plus éloigné du prix d'entrée.")
atrMultiplierTP = input.float(2.0, title="Multiplicateur ATR Take Profit", minval=0.1, tooltip = "Multiplicateur de l'ATR pour déterminer le niveau de Take Profit. Un multiplicateur plus élevé signifie un Take Profit plus éloigné du prix d'entrée.")
takeProfitRiskRatio = input.float(2.0, title="Ratio Take Profit/Risque", minval=0.1, tooltip = "Ratio du Take Profit par rapport au risque (Stop Loss). Par exemple, un ratio de 2 signifie que le Take Profit est deux fois plus éloigné que le Stop Loss.")
volatility_lookback = input.int(20, title="Volatilité Récente (Périodes)", minval=5, tooltip="Nombre de périodes utilisées pour calculer la volatilité récente du marché, mesurée par l'écart-type des prix de clôture.") // Paramètre pour la volatilité
initialCapital = input.float(100, title="Capital Initial (€)", minval=1, tooltip = "Capital initial utilisé pour le backtest de la stratégie.") // Capital initial de 100€
riskPerTrade = input.float(1.0, title="Risque par Trade (%)", minval=0.01, maxval=1.0, tooltip = "Pourcentage du capital initial risqué par trade. Utilisé pour calculer la taille de la position.") // Risk is 100% of available capital
leverage = input.int(1, title="Levier", minval=1, tooltip = "Effet de levier appliqué aux trades. Multiplie les profits et les pertes.")   // Add leverage input

// --- 2. Calcul des Indicateurs et des Résistances ---
sma_short = ta.sma(close, short_length)
sma_long = ta.sma(close, long_length)
rsi = ta.rsi(close, rsi_length)
sma200 = ta.sma(close, sma200_length)
isUptrend = ta.rising(sma200, 5)
isDowntrend = ta.falling(sma200, 5)
resistance_high = ta.highest(high, resistance_length)
resistance_low = ta.lowest(low, resistance_length)
[macdLine, signalLine, hist] = ta.macd(close, macd_fast, macd_slow, macd_signal)
stochK = ta.stoch(close, high, low, stoch_k)
stochD = ta.sma(stochK, stoch_d)
[diPlus, diMinus, adx] = ta.dmi(adx_length, adx_smooth)
atrValue = ta.atr(atrLength)

// Calcul de la volatilité récente (écart-type des prix)
recentVolatility = ta.stdev(close, volatility_lookback)

// --- 3. Détection des Croisements et Conditions ---
short_above_long = sma_short > sma_long and macdLine > signalLine and stochK > stochD and adx > 25 and diPlus > diMinus
short_below_long = sma_short < sma_long and macdLine < signalLine and stochK < stochD and adx > 25 and diMinus > diPlus // Modified stochK < stochD
long_enter = ta.crossover(sma_short,sma_long)
short_enter = ta.crossunder(sma_short,sma_long)

// --- 4. Analyse de Tendance et Recommandations et Points d'Entrée/Sortie Potentiels ---
var string tendance = ""
var color tendance_couleur = color.gray // Couleur neutre par défaut
var float potentialEntry = na
var float potentialStopLoss = na
var float potentialTakeProfit = na

if (isUptrend and short_above_long)
    tendance := "Haussier Fort (Call)"
    tendance_couleur := color.green
    potentialEntry := high
    // Utilisation de la volatilité récente pour le Stop Loss et le Take Profit
    potentialStopLoss := potentialEntry - (recentVolatility * atrMultiplierSL)
    potentialTakeProfit := potentialEntry + (recentVolatility * atrMultiplierTP)

else if (isUptrend and not short_above_long and not short_below_long) // Added check to prevent both conditions being true
    tendance := "Haussier Modéré (Call)"
    tendance_couleur := color.lime
    potentialEntry := high
    potentialStopLoss := potentialEntry - (recentVolatility * atrMultiplierSL)
    potentialTakeProfit := potentialEntry + (recentVolatility * atrMultiplierTP)

else if (isDowntrend and short_below_long)
    tendance := "Baissier Fort (Put)"
    tendance_couleur := color.red
    potentialEntry := low
    potentialStopLoss := potentialEntry + (recentVolatility * atrMultiplierSL)
    potentialTakeProfit := potentialEntry - (recentVolatility * atrMultiplierTP)

else if (isDowntrend and not short_below_long and not short_above_long) // Added check to prevent both conditions being true
    tendance := "Baissier Modéré (Put)"
    tendance_couleur := color.orange
    potentialEntry := low
    potentialStopLoss := potentialEntry + (recentVolatility * atrMultiplierSL)
    potentialTakeProfit := potentialEntry - (recentVolatility * atrMultiplierTP)

else
    tendance := "Neutre"
    tendance_couleur := color.gray
    potentialEntry := na
    potentialStopLoss := na
    potentialTakeProfit := na

// --- 5. Affichage de la Tendance (Label Persistant) ---
var label tendance_label = na

if (barstate.islast)
    if (na(tendance_label))
        tendance_label := label.new(bar_index, high, text="Tendance: " + tendance, color=tendance_couleur, textcolor=color.white, style=label.style_label_down, yloc=yloc.abovebar, y=high*1.02)
        label.set_tooltip(tendance_label, "Tendance actuelle du marché")  // Ajout du tooltip au label
    else
        label.set_text(tendance_label, "Tendance: " + tendance)
        label.set_x(tendance_label, bar_index)
        label.set_y(tendance_label, high*1.02)
        label.set_color(tendance_label, tendance_couleur)
        label.set_tooltip(tendance_label, "Tendance actuelle du marché")
// --- 6. Tableau d'Information ---
var table info_table = table.new(position.top_right, 2, 12, border_width=1) // Ajout d'une ligne pour le capital
var float currentCapital = initialCapital // Declare currentCapital here

table.cell(info_table, 0, 0, "Indicateur", bgcolor=color.gray, text_color=color.white)
table.cell(info_table, 1, 0, "Valeur", bgcolor=color.gray, text_color=color.white)
table.cell(info_table, 0, 1, "SMA Courte", bgcolor=color.white, text_color=color.black)
table.cell(info_table, 1, 1, str.tostring(sma_short, "#.##"), bgcolor=color.white, text_color=color.black)
table.cell_set_tooltip(info_table, 0, 1, "Moyenne mobile courte")
table.cell_set_tooltip(info_table, 1, 1, str.tostring(sma_short, "#.##"))

table.cell(info_table, 0, 2, "SMA Longue", bgcolor=color.white, text_color=color.black)
table.cell(info_table, 1, 2, str.tostring(sma_long, "#.##"), bgcolor=color.white, text_color=color.black)
table.cell_set_tooltip(info_table, 0, 2, "Moyenne mobile longue")
table.cell_set_tooltip(info_table, 1, 2, str.tostring(sma_long, "#.##"))

table.cell(info_table, 0, 3, "RSI", bgcolor=color.white, text_color=color.black)
table.cell(info_table, 1, 3, str.tostring(rsi, "#.##"), bgcolor=color.white, text_color=color.black)
table.cell_set_tooltip(info_table, 0, 3, "Indice de force relative")
table.cell_set_tooltip(info_table, 1, 3, str.tostring(rsi, "#.##"))

table.cell(info_table, 0, 4, "Tendance", bgcolor=color.white, text_color=color.black)
table.cell(info_table, 1, 4, tendance, bgcolor=color.white, text_color=color.black)
table.cell_set_tooltip(info_table, 0, 4, "Tendance actuelle du marché")
table.cell_set_tooltip(info_table, 1, 4, tendance)

table.cell(info_table, 0, 5, "Point d'entrée Potentiel", bgcolor=color.white, text_color=color.black)
table.cell(info_table, 1, 5, str.tostring(potentialEntry, "#.##"), bgcolor=color.white, text_color=color.black)
table.cell_set_tooltip(info_table, 0, 5, "Point d'entrée suggéré pour un trade")
table.cell_set_tooltip(info_table, 1, 5, str.tostring(potentialEntry, "#.##"))

table.cell(info_table, 0, 6, "Stop Loss Potentiel", bgcolor=color.white, text_color=color.black)
table.cell(info_table, 1, 6, str.tostring(potentialStopLoss, "#.##"), bgcolor=color.white, text_color=color.black)
table.cell_set_tooltip(info_table, 0, 6, "Niveau de prix auquel fermer automatiquement une position pour limiter les pertes")
table.cell_set_tooltip(info_table, 1, 6, str.tostring(potentialStopLoss, "#.##"))

table.cell(info_table, 0, 7, "Take Profit Potentiel", bgcolor=color.white, text_color=color.black)
table.cell(info_table, 1, 7, str.tostring(potentialTakeProfit, "#.##"), bgcolor=color.white, text_color=color.black)
table.cell_set_tooltip(info_table, 0, 7, "Niveau de prix auquel fermer automatiquement une position pour sécuriser les profits")
table.cell_set_tooltip(info_table, 1, 7, str.tostring(potentialTakeProfit, "#.##"))

table.cell(info_table, 0, 8, "Résistance Haute", bgcolor=color.white, text_color=color.red)
table.cell(info_table, 1, 8, str.tostring(resistance_high, "#.##"), bgcolor=color.white, text_color=color.red)
table.cell_set_tooltip(info_table, 0, 8, "Niveau de prix auquel on s'attend à ce que la pression vendeuse l'emporte sur la pression acheteuse")
table.cell_set_tooltip(info_table, 1, 8, str.tostring(resistance_high, "#.##"))

table.cell(info_table, 0, 9, "Résistance Basse", bgcolor=color.white, text_color=color.green)
table.cell(info_table, 1, 9, str.tostring(resistance_low, "#.##"), bgcolor=color.white, text_color=color.green)
table.cell_set_tooltip(info_table, 0, 9, "Niveau de prix auquel on s'attend à ce que la pression acheteuse l'emporte sur la pression vendeuse")
table.cell_set_tooltip(info_table, 1, 9, str.tostring(resistance_low, "#.##"))

table.cell(info_table, 0, 10, "ATR", bgcolor=color.white, text_color=color.black)
table.cell(info_table, 1, 10, str.tostring(atrValue, "#.##"), bgcolor=color.white, text_color=color.black)
table.cell_set_tooltip(info_table, 0, 10, "Average True Range")
table.cell_set_tooltip(info_table, 1, 10, str.tostring(atrValue, "#.##"))

table.cell(info_table, 0, 11, "Volatilité Récente", bgcolor=color.white, text_color=color.black)
table.cell(info_table, 1, 11, str.tostring(recentVolatility, "#.##"), bgcolor=color.white, text_color=color.black)
table.cell_set_tooltip(info_table, 0, 11, "Volatilité du marché calculée sur les dernières périodes")
table.cell_set_tooltip(info_table, 1, 11, str.tostring(recentVolatility, "#.##"))
// --- 7. Tracé des Indicateurs et des Résistances ---
plot(sma_short, color=color.blue, title="SMA Courte")
plot(sma_long, color=color.orange, title="SMA Longue")
plot(sma200, color=color.yellow, title="SMA 200", linewidth=2)
plot(resistance_high, color=color.red, title="Résistance Haute", linewidth=2, style=plot.style_linebr)
plot(resistance_low, color=color.green, title="Résistance Basse (Support)", linewidth=2, style=plot.style_linebr)

// --- 8. Tracé des Points d'Entrée et de Sortie Potentiels ---
plotshape(isUptrend and short_above_long, title="Entrée Call Potentielle", style=shape.triangleup, location=location.belowbar, color=color.green, size=size.small, offset=0)
plotshape(isDowntrend and short_below_long, title="Entrée Put Potentielle", style=shape.triangledown, location=location.abovebar, color=color.red, size=size.small, offset=0)

plot(potentialStopLoss, color=color.red, title="Stop Loss Potentiel", linewidth=1, style=plot.style_linebr)
plot(potentialTakeProfit, color=color.green, title="Take Profit Potentiel", linewidth=1, style=plot.style_linebr)

// --- 9. Ajout des Noms des Courbes ---
if barstate.islast
    var label_sma_short = label.new(bar_index, sma_short, "SMA Courte", color=color.blue, style=label.style_label_left)
    label.set_tooltip(label_sma_short, "Moyenne mobile Courte")
    var label_sma_long = label.new(bar_index, sma_long, "SMA Longue", color=color.orange, style=label.style_label_left)
    label.set_tooltip(label_sma_long, "Moyenne mobile Longue")
    var label_sma200 = label.new(bar_index, sma200, "SMA 200", color=color.yellow, style=label.style_label_left)
    label.set_tooltip(label_sma200, "Moyenne mobile 200")
    var label_resistance_high = label.new(bar_index, resistance_high, "Résistance Haute", color=color.red, style=label.style_label_left)
    label.set_tooltip(label_resistance_high, "Niveau de Résistance Haute")
    var label_resistance_low = label.new(bar_index, resistance_low, "Résistance Basse", color=color.green, style=label.style_label_left)
    label.set_tooltip(label_resistance_low, "Niveau de Résistance Basse")

// --- 10. Backtest ---
var int tradesCount = 0
var int winningTradesCount = 0
var int losingTradesCount = 0
var float totalProfit = 0.0
var float maxDrawdown = 0.0
var float previousPeak = initialCapital
var int currentPosition = 0 // 0: no position, 1: long (Call), -1: short (Put)
var float entryPrice = 0.0
var float positionSize = 0.0
var float stopLossPrice = 0.0
var float takeProfitPrice = 0.0
var int entryDate = 0
var int exitDate = 0
var float exitPrice = 0.0 // Declare exitPrice here
var float tradeProfit = 0.0
currentCapital := initialCapital // Reset capital at the beginning of the backtest

if (currentPosition == 0) // No open position
    if (isUptrend and short_above_long)
        // Enter a long position (Call)
        tradesCount := tradesCount + 1
        entryPrice := potentialEntry
        positionSize := math.floor((currentCapital * riskPerTrade * leverage) / (entryPrice - potentialStopLoss)) // Position size based on risk
        if (positionSize > 0) // check if positionSize is valid
            currentPosition := 1
            stopLossPrice := potentialStopLoss
            takeProfitPrice := potentialTakeProfit
            entryDate := time
            strategy.entry("Call", strategy.long, qty=positionSize, comment="Call Entry", stop=stopLossPrice, limit=takeProfitPrice) // Utilisez strategy.entry
    else if (isDowntrend and short_below_long)
        // Enter a short position (Put)
        tradesCount := tradesCount + 1
        entryPrice := potentialEntry
        positionSize := math.floor((currentCapital * riskPerTrade * leverage) / (potentialStopLoss - entryPrice)) // Position size based on risk
        if (positionSize > 0) // check if positionSize is valid
            currentPosition := -1
            stopLossPrice := potentialStopLoss
            takeProfitPrice := potentialTakeProfit
            entryDate := time
            strategy.entry("Put", strategy.short, qty=positionSize, comment="Put Entry", stop=stopLossPrice, limit=takeProfitPrice) // Utilisez strategy.entry

else if (currentPosition != 0) // There is an open position
    if (currentPosition == 1) // Long position (Call)
        if (low <= stopLossPrice or high >= takeProfitPrice)
            // Exit the long position
            exitPrice := low <= stopLossPrice ? stopLossPrice : takeProfitPrice
            tradeProfit := positionSize * (exitPrice - entryPrice)
            currentCapital := currentCapital + tradeProfit
            totalProfit := totalProfit + tradeProfit
            if (tradeProfit > 0)
                winningTradesCount := winningTradesCount + 1
            else
                losingTradesCount := losingTradesCount + 1
            currentPosition := 0
            exitDate := time
            strategy.close("Call", comment="Call Exit", qty=positionSize) // Utilisez strategy.close
    else if (currentPosition == -1) // Short position (Put)
        if (high >= stopLossPrice or low <= takeProfitPrice)
            // Exit the short position
            exitPrice := high >= stopLossPrice ? stopLossPrice : takeProfitPrice
            tradeProfit := positionSize * (entryPrice - exitPrice)  // Short position profit
            currentCapital := currentCapital + tradeProfit
            totalProfit := totalProfit + tradeProfit
            if (tradeProfit > 0)
                winningTradesCount := winningTradesCount + 1
            else
                losingTradesCount := losingTradesCount + 1
            currentPosition := 0
            exitDate := time
            strategy.close("Put", comment="Put Exit", qty=positionSize) // Utilisez strategy.close

// --- 11. Calcul des métriques de performance ---
if (currentCapital > previousPeak)
    previousPeak := currentCapital
var float drawdown = 0.0
drawdown := previousPeak - currentCapital
if (drawdown > maxDrawdown)
    maxDrawdown := drawdown

var float winRate = 0.0
var float averageProfit = 0.0
var float averageLoss = 0.0
var float profitFactor = 0.0

winRate := tradesCount > 0 ? (winningTradesCount / tradesCount) * 100 : 0
averageProfit := winningTradesCount > 0 ? totalProfit / winningTradesCount : 0
averageLoss := losingTradesCount > 0 ? totalProfit / losingTradesCount : 0
profitFactor := averageLoss != 0 ? math.abs(averageProfit / averageLoss) : 0
Detail
https://www.fmz.com/strategy/488890
Last Modified
2025-03-31 16:30:52