
8.6 KiB
Name
多级布林带回归交易策略-Multi-Level-Bollinger-Bands-Mean-Reversion-Trading-Strategy
Author
ianzeng123
Strategy Description
[trans]
概述
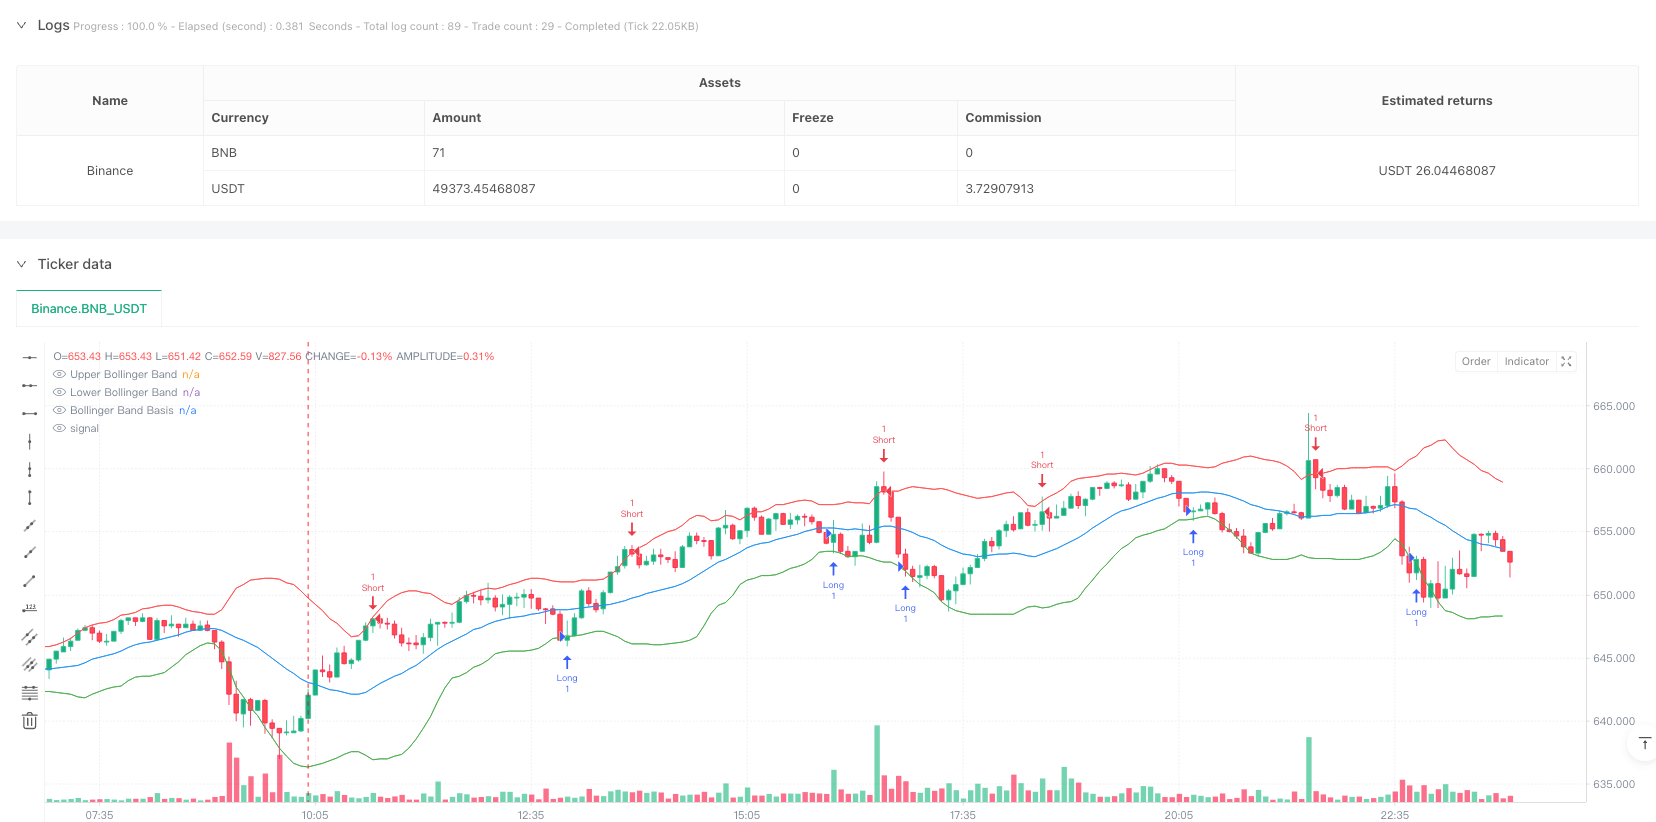
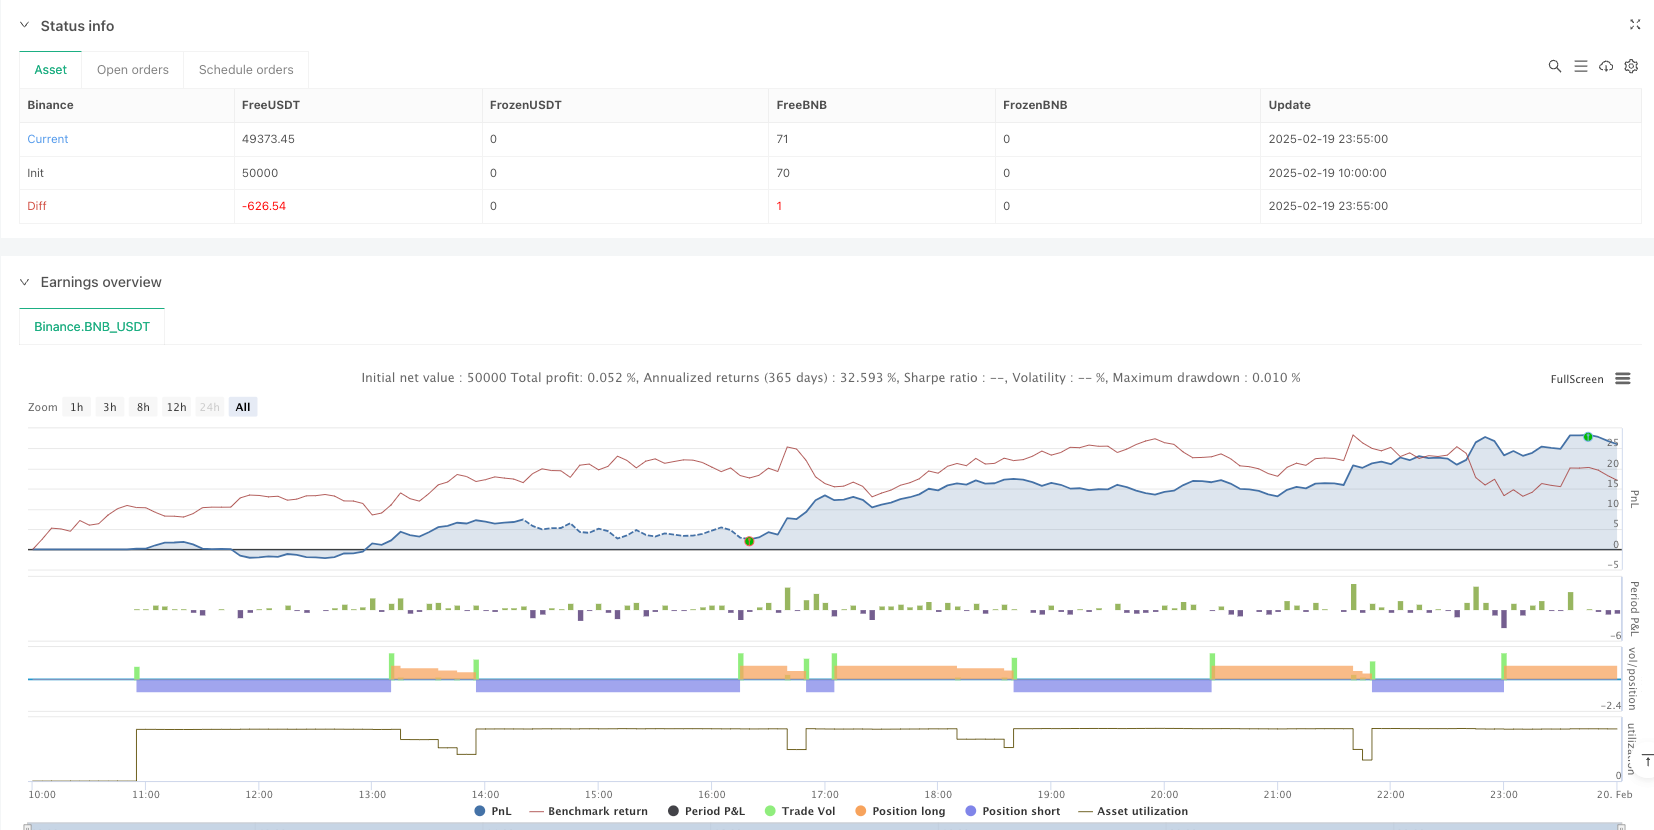
这是一个基于布林带均值回归原理的交易策略,通过多个止盈等级实现分批获利。策略在价格突破布林带后回归时进行交易,并设置了5个不同的止盈水平来逐步减持仓位。同时设置了动态止损来控制风险。策略可以在自定义的交易时段内运行,并支持加仓操作。
策略原理
策略基于20周期的布林带指标,使用2倍标准差作为波动区间。当价格从下方突破下轨并收盘在带内时,触发做多信号;当价格从上方突破上轨并收盘在带内时,触发做空信号。入场后,策略采用5级止盈机制,分别在0.5%、1%、1.5%、2%和2.5%的位置设置止盈点,每个止盈点平仓20%的仓位。最后一级止盈设在相对的布林带位置。同时设置1%的止损来控制风险。
策略优势
- 采用多级止盈机制,能够在趋势延续时获取更多收益,同时确保部分利润兑现
- 支持在交易方向正确时进行加仓,提高盈利能力
- 利用布林带作为动态支撑阻力位,适应市场波动
- 可自定义交易时段,避免非交易时段的干扰
- 设置了止损机制,有效控制风险
策略风险
- 在高波动市场中可能频繁触发假突破信号
- 快速趋势行情中可能错过更大的盈利机会
- 加仓机制在市场反转时可能导致更大损失
- 多个止盈订单可能因流动性不足无法完全执行 建议通过调整布林带参数和止盈止损比例来适应不同市场环境。
策略优化方向
- 引入成交量指标作为信号过滤条件,提高突破的可靠性
- 根据波动率动态调整止盈止损位置
- 增加趋势过滤指标,避免在强趋势中逆势交易
- 优化加仓逻辑,设置最大持仓限制
- 考虑增加移动止损功能,更好地保护利润
总结
该策略通过布林带指标捕捉均值回归机会,采用多级止盈和动态止损来管理风险。策略的优势在于其灵活的仓位管理和风险控制机制,但在使用时需要注意市场环境的适配性。通过添加额外的过滤指标和优化止盈止损参数,可以进一步提高策略的稳定性和盈利能力。 ||
Overview
This is a mean reversion trading strategy based on Bollinger Bands with multiple take-profit levels. The strategy enters trades when price rebounds after breaking the bands, with 5 different take-profit levels for gradual position reduction. It implements dynamic stop-loss for risk control and can operate during custom trading sessions with position adding capability.
Strategy Principle
The strategy uses 20-period Bollinger Bands with 2 standard deviations as the volatility range. Long signals are triggered when price breaks below the lower band and closes inside, while short signals occur when price breaks above the upper band and closes inside. After entry, the strategy employs a 5-level take-profit mechanism, setting profit targets at 0.5%, 1%, 1.5%, 2%, and 2.5%, each closing 20% of the position. The final take-profit is set at the opposite Bollinger Band. A 1% stop-loss is implemented for risk control.
Strategy Advantages
- Multi-level take-profit mechanism captures extended trends while securing partial profits
- Supports position adding when trade direction is correct, enhancing profit potential
- Uses Bollinger Bands as dynamic support/resistance levels, adapting to market volatility
- Customizable trading sessions to avoid off-hours interference
- Implements stop-loss mechanism for effective risk control
Strategy Risks
- May trigger frequent false breakout signals in highly volatile markets
- Could miss larger profit opportunities in rapid trend movements
- Position adding mechanism may lead to larger losses during market reversals
- Multiple take-profit orders may not fully execute due to insufficient liquidity Recommend adjusting Bollinger Band parameters and profit/loss ratios for different market conditions.
Optimization Directions
- Incorporate volume indicators as signal filters to improve breakout reliability
- Dynamically adjust take-profit and stop-loss levels based on volatility
- Add trend filtering indicators to avoid counter-trend trading in strong trends
- Optimize position adding logic with maximum position limits
- Consider adding trailing stop-loss functionality for better profit protection
Summary
The strategy captures mean reversion opportunities using Bollinger Bands, employing multiple take-profit levels and dynamic stop-loss for risk management. Its strengths lie in flexible position management and risk control mechanisms, but market environment compatibility must be considered. Strategy stability and profitability can be further enhanced by adding additional filtering indicators and optimizing profit/loss parameters.[/trans]
Source (PineScript)
/*backtest
start: 2025-02-19 10:00:00
end: 2025-02-20 00:00:00
period: 5m
basePeriod: 5m
exchanges: [{"eid":"Binance","currency":"BNB_USDT"}]
*/

//@version=5
strategy("Bollinger Band Reentry Strategy", overlay=true)

// Inputs
bbLength = input.int(20, title="Bollinger Band Length")
bbMult = input.float(2.0, title="Bollinger Band Multiplier")
stopLossPerc = input.float(1.0, title="Stop Loss (%)") / 100
tp1Perc = input.float(0.5, title="Take Profit 1 (%)") / 100
tp2Perc = input.float(1.0, title="Take Profit 2 (%)") / 100
tp3Perc = input.float(1.5, title="Take Profit 3 (%)") / 100
tp4Perc = input.float(2.0, title="Take Profit 4 (%)") / 100
tp5Perc = input.float(2.5, title="Take Profit 5 (%)") / 100
allowAddToPosition = input.bool(true, title="Allow Adding to Position")
customSession = input.timeframe("0930-1600", title="Custom Trading Session")

// Calculate Bollinger Bands
basis = ta.sma(close, bbLength)
dev = ta.stdev(close, bbLength)
upperBB = basis + bbMult * dev
lowerBB = basis - bbMult * dev

// Plot Bollinger Bands
plot(upperBB, color=color.red, title="Upper Bollinger Band")
plot(lowerBB, color=color.green, title="Lower Bollinger Band")
plot(basis, color=color.blue, title="Bollinger Band Basis")

// Entry Conditions
longCondition = (ta.crossover(close, lowerBB) or (low < lowerBB and close > lowerBB)) and time(timeframe.period, customSession)
shortCondition = (ta.crossunder(close, upperBB) or (high > upperBB and close < upperBB)) and time(timeframe.period, customSession)

// Execute Trades
if (longCondition)
    strategy.entry("Long", strategy.long, when=allowAddToPosition or strategy.position_size == 0)
if (shortCondition)
    strategy.entry("Short", strategy.short, when=allowAddToPosition or strategy.position_size == 0)

// Take-Profit and Stop-Loss Levels for Long Trades
if (strategy.position_size > 0)
    strategy.exit("TP1", "Long", limit=strategy.position_avg_price * (1 + tp1Perc), qty=strategy.position_size * 0.2) // Take 20% profit
    strategy.exit("TP2", "Long", limit=strategy.position_avg_price * (1 + tp2Perc), qty=strategy.position_size * 0.2)
    strategy.exit("TP3", "Long", limit=strategy.position_avg_price * (1 + tp3Perc), qty=strategy.position_size * 0.2)
    strategy.exit("TP4", "Long", limit=strategy.position_avg_price * (1 + tp4Perc), qty=strategy.position_size * 0.2)
    strategy.exit("TP5", "Long", limit=upperBB, qty=strategy.position_size * 0.2) // Take final 20% at opposite band
    strategy.exit("Stop Loss", "Long", stop=strategy.position_avg_price * (1 - stopLossPerc))

// Take-Profit and Stop-Loss Levels for Short Trades
if (strategy.position_size < 0)
    strategy.exit("TP1", "Short", limit=strategy.position_avg_price * (1 - tp1Perc), qty=strategy.position_size * 0.2)
    strategy.exit("TP2", "Short", limit=strategy.position_avg_price * (1 - tp2Perc), qty=strategy.position_size * 0.2)
    strategy.exit("TP3", "Short", limit=strategy.position_avg_price * (1 - tp3Perc), qty=strategy.position_size * 0.2)
    strategy.exit("TP4", "Short", limit=strategy.position_avg_price * (1 - tp4Perc), qty=strategy.position_size * 0.2)
    strategy.exit("TP5", "Short", limit=lowerBB, qty=strategy.position_size * 0.2)
    strategy.exit("Stop Loss", "Short", stop=strategy.position_avg_price * (1 + stopLossPerc))

// Alerts
alertcondition(longCondition, title="Long Signal", message="Price closed inside Bollinger Band from below.")
alertcondition(shortCondition, title="Short Signal", message="Price closed inside Bollinger Band from above.")
Detail
https://www.fmz.com/strategy/483086
Last Modified
2025-02-21 13:06:24