
19 KiB
Name
多均线趋势突破回踩交易系统与ATR动态止损-Multi-MA-Trend-Breakout-Pullback-System-with-ATR-Dynamic-Stop-Loss
Author
ianzeng123
Strategy Description
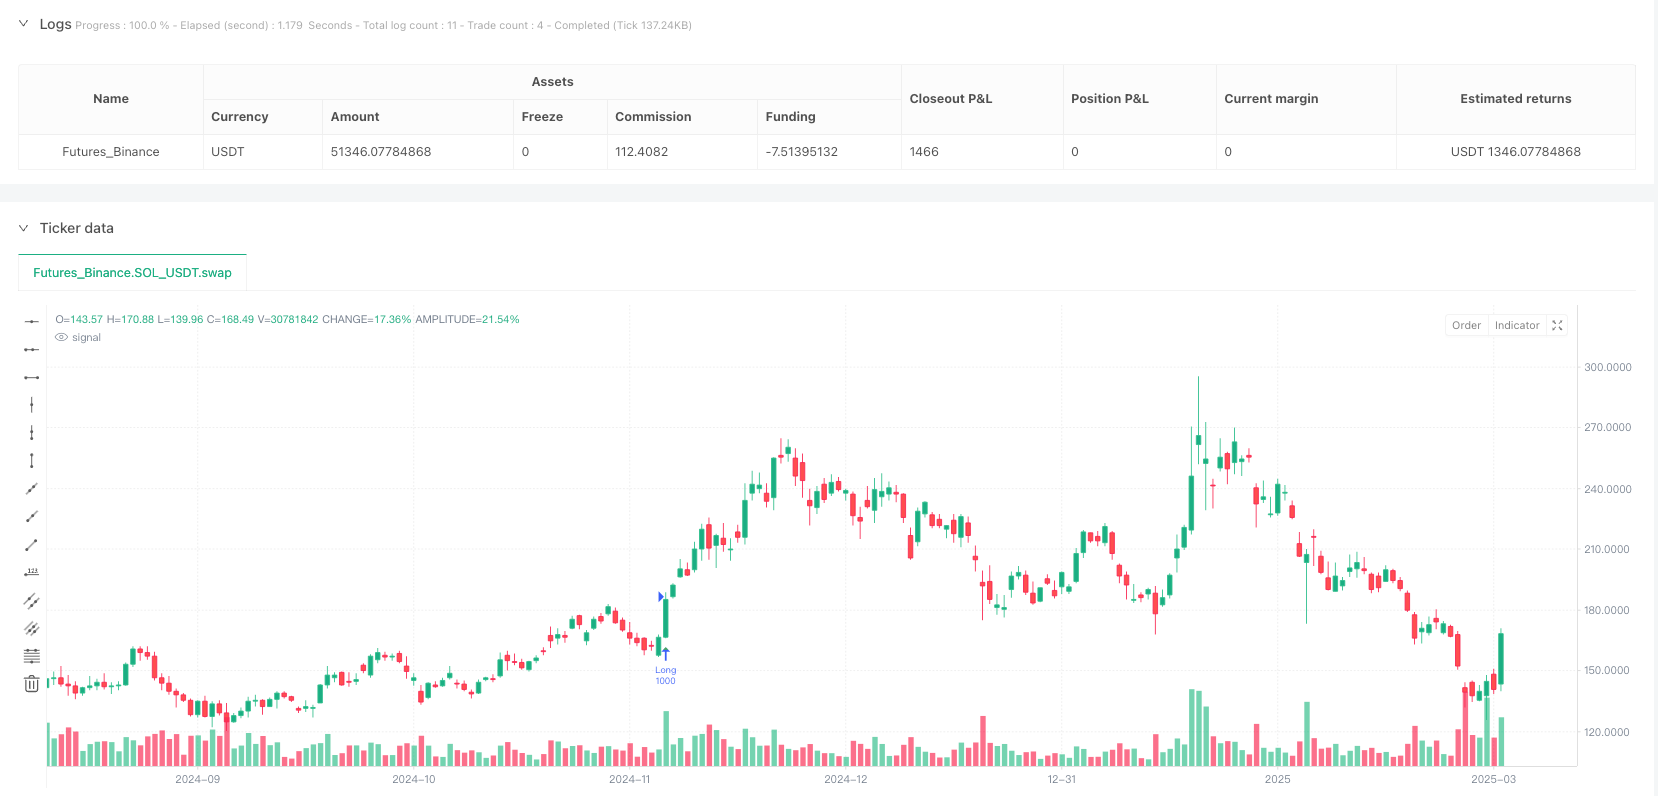
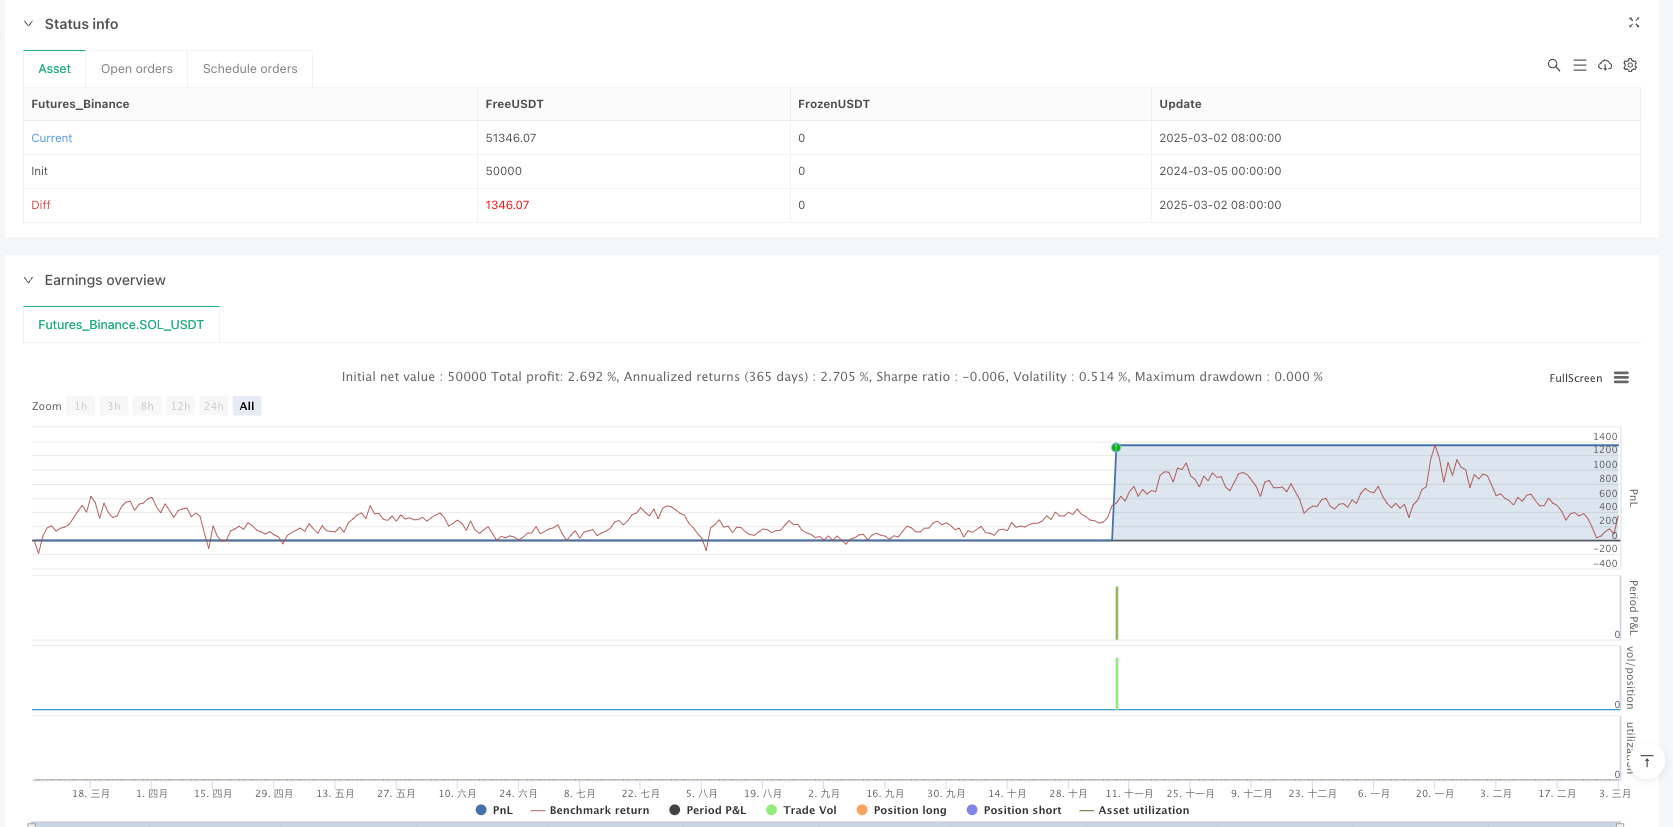
[trans]## 策略概述
该策略是一个基于多周期均线、趋势识别和量能分析的交易系统,核心思想是通过识别短期和中期均线形成的密集区,结合长期均线确认的趋势方向,在价格突破密集区后回踩时入场交易,并采用ATR动态止损和移动止盈机制管理风险。策略在传统均线系统基础上进行了优化,增加了成交量过滤、趋势过滤和精准的回踩入场条件,使得交易信号更加可靠。
策略原理
该策略的核心原理基于以下几个关键组件:
-
均线密集区识别:策略使用20日(短期)和60日(中期)均线形成密集区,这一区域通常代表市场参与者的共识价值区,具有一定的支撑或阻力作用。
-
趋势方向确认:通过比较60日(中期)和120日(长期)均线的相对位置来确定整体趋势方向。当中期均线位于长期均线之上时,被识别为上升趋势;反之为下降趋势。
-
突破后回踩入场:策略的独特之处在于不直接在突破点入场,而是等待价格在突破后回踩至密集区时再入场,这种做法可以有效减少虚假突破带来的风险。
-
成交量确认:入场信号需要满足成交量超过20日平均成交量的1.5倍的条件,确保市场有足够的参与度支持价格运动。
-
风险管理:策略使用基于ATR指标的动态止损和移动止盈机制,使止损止盈水平能够根据市场波动性自动调整,适应不同市场环境。
从代码实现来看,多头入场条件为:前一日价格突破密集区上轨(smaShort和smaMid的最大值),当日价格回踩但仍在密集区内(不低于下轨),且中期趋势向上(smaMid > smaLong),同时成交量条件满足。空头入场条件与之相反。
策略优势
通过深入分析该策略的代码实现,可以总结出以下优势:
-
多层级确认机制:策略综合考虑了短、中、长三个时间周期的均线指标,并结合价格行为和成交量,形成多层级的信号确认机制,有效降低了误判率。
-
回踩入场降低风险:与传统的突破策略直接在突破点入场不同,该策略通过等待回踩入场,能够获得更好的入场价格,降低交易成本和风险。
-
趋势过滤提高胜率:通过中长期均线关系确定大趋势方向,只在趋势方向明确时交易,避免了震荡市中频繁交易带来的亏损。
-
动态风险管理:基于ATR的止损和移动止盈机制能够根据市场波动性自动调整保护位置,在保护利润的同时给予价格足够的呼吸空间。
-
成交量确认增强可靠性:通过要求成交量大于平均水平1.5倍,确保交易发生在市场活跃度高的时期,减少低流动性环境中的误判。
-
参数可调节性强:策略提供了多个可调参数,如均线周期、ATR倍数、成交量阈值等,使交易者可以根据不同市场环境和交易偏好进行灵活调整。
策略风险
尽管该策略设计较为全面,但仍存在以下潜在风险:
-
均线滞后性:均线本质上是滞后指标,在剧烈波动的市场中可能无法及时反映价格变化,导致入场或出场信号延迟。解决方法是考虑在高波动市场中适当缩短均线周期,或结合其他领先指标辅助决策。
-
频繁假突破:在横盘震荡市场中,价格可能频繁突破密集区后又回归,导致频繁交易和累积亏损。建议增加额外过滤条件,如要求突破幅度达到一定百分比,或结合支撑阻力位分析。
-
止损范围设置风险:固定倍数的ATR止损可能在不同市场环境中过松或过紧。应该根据具体品种的波动特性和历史回测结果调整ATR倍数参数。
-
过度依赖成交量:某些市场的成交量数据可能不够透明或准确,过度依赖成交量条件可能导致错过有效信号。可以考虑将成交量条件设置为可选,或结合价格行为分析。
-
参数优化过度拟合:多参数系统容易陷入过度拟合陷阱,在历史数据上表现良好但实盘效果不佳。建议使用走样测试(Walk-Forward Analysis)验证策略在不同时间段的稳定性。
策略优化方向
基于代码分析,该策略可以从以下几个方向进行优化:
-
增加时间框架过滤:考虑添加更大时间框架的趋势确认,确保交易方向与更大周期趋势一致。这样做的原因是大周期趋势通常具有更强的持续性和可靠性。
-
引入价格波动率自适应机制:可以根据近期市场波动率自动调整均线周期和ATR倍数,使策略在不同市场环境中都能保持良好表现。在波动率高的市场中适当延长均线周期,降低信号频率;在波动率低的市场中适当缩短均线周期,提高灵敏度。
-
加入季节性和时间过滤:某些市场存在明显的季节性特征或日内时间效应,可以添加时间过滤条件,避开历史上表现不佳的时间段。
-
优化回踩确认逻辑:当前回踩确认仅基于价格是否在密集区内,可以考虑增加更精细的回踩深度要求,如要求回踩至密集区的特定比例位置(如38.2%、50%回撤位),或结合K线形态确认回踩结束。
-
增加资金管理模块:当前策略使用固定数量交易,可以改进为基于账户规模和风险比例的动态仓位管理,如固定风险比例或凯利公式,以优化资金曲线和最大回撤控制。
-
加入市场环境识别:增加市场环境的分类识别(趋势市/震荡市),在不同市场环境中采用不同的参数设置或甚至不同的交易策略,这样可以避免在不适合的市场环境中频繁交易。
总结
"多均线趋势突破回踩交易系统与ATR动态止损"是一个结合了技术分析中多种成熟理念的量化交易策略。它通过均线密集区识别价值区间,利用均线系统确定趋势方向,结合突破回踩的价格行为和成交量确认,构建了一个相对完善的交易系统。该策略的优势在于多层级的信号确认机制和灵活的风险管理体系,适合中长期趋势跟踪交易。
该策略在实际应用中需要注意均线系统的滞后性问题和参数优化的过度拟合风险。通过增加自适应机制、市场环境识别和更精细的回踩确认逻辑,该策略有较大的提升空间。此外,结合更完善的资金管理系统,将进一步提高策略的稳定性和长期盈利能力。
总的来说,这是一个设计合理、逻辑清晰的交易系统,体现了"趋势跟随+动态风险管理"的核心交易理念,适合有一定经验的交易者在趋势明确的市场中应用。|| ## Strategy Overview
This strategy is a trading system based on multiple-period moving averages, trend identification, and volume analysis. The core idea is to identify dense zones formed by short-term and mid-term moving averages, confirm trend direction using long-term moving averages, enter trades when price pulls back to the dense zone after a breakout, and manage risk using ATR dynamic stop loss and trailing profit mechanisms. The strategy optimizes traditional moving average systems by adding volume filtering, trend filtering, and precise pullback entry conditions, making trading signals more reliable.
Strategy Principles
The core principles of this strategy are based on the following key components:
-
Moving Average Dense Zone Identification: The strategy uses 20-day (short-term) and 60-day (mid-term) moving averages to form a dense zone, which typically represents the consensus value area of market participants and has certain support or resistance effects.
-
Trend Direction Confirmation: The overall trend direction is determined by comparing the relative positions of the 60-day (mid-term) and 120-day (long-term) moving averages. When the mid-term moving average is above the long-term moving average, it is identified as an uptrend; otherwise, it is a downtrend.
-
Pullback Entry After Breakout: The unique aspect of the strategy is that it doesn't enter directly at the breakout point but waits for the price to pull back to the dense zone after breaking out, which can effectively reduce the risk of false breakouts.
-
Volume Confirmation: Entry signals require volume to exceed 1.5 times the 20-day average volume, ensuring sufficient market participation to support price movement.
-
Risk Management: The strategy uses ATR-based dynamic stop loss and trailing profit mechanisms, allowing stop loss and profit levels to automatically adjust according to market volatility, adapting to different market environments.
From the code implementation, the long entry conditions are: the previous day's price breaks above the upper boundary of the dense zone (maximum of smaShort and smaMid), the current day's price pulls back but remains within the dense zone (not below the lower boundary), the mid-term trend is up (smaMid > smaLong), and volume conditions are met. Short entry conditions are the opposite.
Strategy Advantages
Through in-depth analysis of the strategy's code implementation, the following advantages can be summarized:
-
Multi-level Confirmation Mechanism: The strategy comprehensively considers moving average indicators from short, medium, and long time periods, combined with price action and volume, forming a multi-level signal confirmation mechanism that effectively reduces misjudgment rates.
-
Pullback Entry Reduces Risk: Unlike traditional breakout strategies that enter directly at the breakout point, this strategy waits for pullbacks to enter, obtaining better entry prices and reducing trading costs and risks.
-
Trend Filtering Improves Win Rate: By determining major trend direction through the relationship between mid and long-term moving averages, trading only when the trend direction is clear avoids losses from frequent trading in oscillating markets.
-
Dynamic Risk Management: ATR-based stop loss and trailing profit mechanisms automatically adjust protection positions based on market volatility, protecting profits while giving price sufficient breathing room.
-
Volume Confirmation Enhances Reliability: By requiring volume greater than 1.5 times the average level, trades occur during periods of high market activity, reducing misjudgments in low-liquidity environments.
-
Strong Parameter Adjustability: The strategy provides multiple adjustable parameters, such as moving average periods, ATR multiples, volume thresholds, allowing traders to make flexible adjustments based on different market environments and trading preferences.
Strategy Risks
Despite the comprehensive design of this strategy, there are still the following potential risks:
-
Moving Average Lag: Moving averages are inherently lagging indicators and may not reflect price changes in a timely manner in violently fluctuating markets, leading to delayed entry or exit signals. The solution is to consider shortening moving average periods in high-volatility markets or combining with other leading indicators to assist decision-making.
-
Frequent False Breakouts: In sideways oscillating markets, prices may frequently break through the dense zone and then return, leading to frequent trading and accumulated losses. It is recommended to add additional filtering conditions, such as requiring breakout amplitude to reach a certain percentage, or combining support and resistance level analysis.
-
Stop Loss Range Setting Risk: Fixed multiple ATR stops may be too loose or too tight in different market environments. The ATR multiple parameter should be adjusted based on the volatility characteristics of the specific instrument and historical backtesting results.
-
Over-reliance on Volume: Volume data in some markets may not be transparent or accurate enough, and over-reliance on volume conditions may cause missed valid signals. Consider setting volume conditions as optional or combining with price action analysis.
-
Parameter Optimization Overfitting: Multi-parameter systems are prone to overfitting traps, performing well on historical data but poorly in live trading. It is recommended to use Walk-Forward Analysis to verify strategy stability across different time periods.
Strategy Optimization Directions
Based on code analysis, the strategy can be optimized in the following directions:
-
Add Timeframe Filtering: Consider adding larger timeframe trend confirmation to ensure trading direction is consistent with larger cycle trends. This is because larger cycle trends typically have stronger persistence and reliability.
-
Introduce Price Volatility Adaptive Mechanism: Automatically adjust moving average periods and ATR multiples based on recent market volatility, maintaining good performance in different market environments. In high-volatility markets, appropriately extend moving average periods to reduce signal frequency; in low-volatility markets, appropriately shorten moving average periods to increase sensitivity.
-
Add Seasonality and Time Filtering: Some markets have obvious seasonal characteristics or intraday time effects. Adding time filtering conditions can avoid historically poor-performing time periods.
-
Optimize Pullback Confirmation Logic: Current pullback confirmation is only based on whether the price is within the dense zone. Consider adding more refined pullback depth requirements, such as requiring pullbacks to specific percentage positions in the dense zone (e.g., 38.2%, 50% retracement levels), or combining candlestick patterns to confirm the end of pullbacks.
-
Add Money Management Module: The current strategy uses fixed quantity trading. It can be improved to dynamic position management based on account size and risk proportion, such as fixed risk proportion or Kelly formula, to optimize equity curve and maximum drawdown control.
-
Add Market Environment Recognition: Add classification recognition of market environments (trending/oscillating markets) and adopt different parameter settings or even different trading strategies in different market environments, avoiding frequent trading in unsuitable market environments.
Summary
The "Multi-MA Trend Breakout Pullback System with ATR Dynamic Stop Loss" is a quantitative trading strategy that combines multiple mature concepts in technical analysis. It identifies value zones through moving average dense zones, determines trend direction using moving average systems, and builds a relatively complete trading system by combining breakout pullback price action and volume confirmation. The strategy's advantages lie in its multi-level signal confirmation mechanism and flexible risk management system, suitable for medium to long-term trend-following trading.
In practical application, this strategy needs to pay attention to the lagging problem of moving average systems and the risk of overfitting in parameter optimization. There is considerable room for improvement through adding adaptive mechanisms, market environment recognition, and more refined pullback confirmation logic. Additionally, combining with a more complete money management system will further enhance the strategy's stability and long-term profitability.
Overall, this is a reasonably designed trading system with clear logic, reflecting the core trading philosophy of "trend following + dynamic risk management," suitable for experienced traders to apply in markets with clear trends.[/trans]
Source (PineScript)
/*backtest
start: 2024-03-05 00:00:00
end: 2025-03-03 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"SOL_USDT"}]
*/

//@version=5
strategy("均线密集区交易系统(优化版2)", shorttitle="MA_Zone_Opt2", overlay=true, initial_capital=10000, default_qty_type=strategy.fixed, default_qty_value=1000, commission_value=0.1)

// === 输入参数 ===
smaShortPeriod = input.int(20, title="短期SMA周期", minval=1)
smaMidPeriod = input.int(60, title="中期SMA周期", minval=1)
smaLongPeriod = input.int(120, title="长期SMA周期", minval=1)
atrPeriod = input.int(14, title="ATR周期", minval=1)
atrMultiplierStop = input.float(3.0, title="止损ATR倍数", minval=1.0)
atrMultiplierTrail = input.float(2.0, title="移动止盈ATR倍数", minval=1.0)
volPeriod = input.int(20, title="成交量周期", minval=1)
volThreshold = input.float(1.5, title="成交量倍数", minval=1.0)

// === 计算均线 ===
smaShort = ta.sma(close, smaShortPeriod)  // MA20
smaMid = ta.sma(close, smaMidPeriod)      // MA60
smaLong = ta.sma(close, smaLongPeriod)    // MA120

// === 计算 ATR 和成交量 ===
atrValue = ta.atr(atrPeriod)
volAvg = ta.sma(volume, volPeriod)
volCondition = volume > volAvg * volThreshold  // 成交量高于平均值 1.5 倍

// === 定义均线密集区(只用 SMA20 和 SMA60) ===
maMax = math.max(smaShort, smaMid)
maMin = math.min(smaShort, smaMid)

// === 趋势过滤:SMA60 和 SMA120 的相对位置 ===
trendUp = smaMid > smaLong  // 60日均线上穿120日均线,上升趋势
trendDown = smaMid < smaLong  // 60日均线下穿120日均线,下降趋势

// === 交易信号逻辑 ===
// 涨破密集区:K线收盘价突破 maMax
breakUp = ta.crossover(close, maMax)
// 跌破密集区:K线收盘价跌破 maMin
breakDown = ta.crossunder(close, maMin)
// 回踩条件:
// 买入 - 前一根K线跌至密集区内,当前K线仍在密集区内,且趋势向上
pullbackUp = close[1] <= maMax and close[1] >= maMin and close >= maMin and trendUp and volCondition
// 卖出 - 前一根K线涨至密集区内,当前K线仍在密集区内,且趋势向下
pullbackDown = close[1] >= maMin and close[1] <= maMax and close <= maMax and trendDown and volCondition

// === 买卖逻辑 ===
// 买入(多单):涨破后回踩,且趋势向上
if breakUp[1] and pullbackUp
    strategy.entry("Long", strategy.long)
// 动态止损和移动止盈
stopLossPrice = strategy.position_avg_price * (1 - atrMultiplierStop * atrValue / close)
trailStopPrice = close * (1 - atrMultiplierTrail * atrValue / close)
strategy.exit("Long_Exit", "Long", stop=stopLossPrice, trail_points=trailStopPrice, trail_offset=0)

// 卖出(空单):跌破后回踩,且趋势向下
if breakDown[1] and pullbackDown
    strategy.entry("Short", strategy.short)
// 动态止损和移动止盈
stopLossPriceShort = strategy.position_avg_price * (1 + atrMultiplierStop * atrValue / close)
trailStopPriceShort = close * (1 + atrMultiplierTrail * atrValue / close)
strategy.exit("Short_Exit", "Short", stop=stopLossPriceShort, trail_points=trailStopPriceShort, trail_offset=0)

// === 绘制信号点 ===
plotshape(breakUp[1] and pullbackUp, title="买入信号", location=location.belowbar, color=color.green, style=shape.triangleup, size=size.small)
plotshape(breakDown[1] and pullbackDown, title="卖出信号", location=location.abovebar, color=color.red, style=shape.triangledown, size=size.small)
Detail
https://www.fmz.com/strategy/484917
Last Modified
2025-03-05 09:58:09