
7.1 KiB
Name
增强趋势多重信号动态交易策略-Enhanced-Trend-Multi-Signal-Dynamic-Trading-Strategy
Author
ChaoZhang
Strategy Description
[trans]
概述
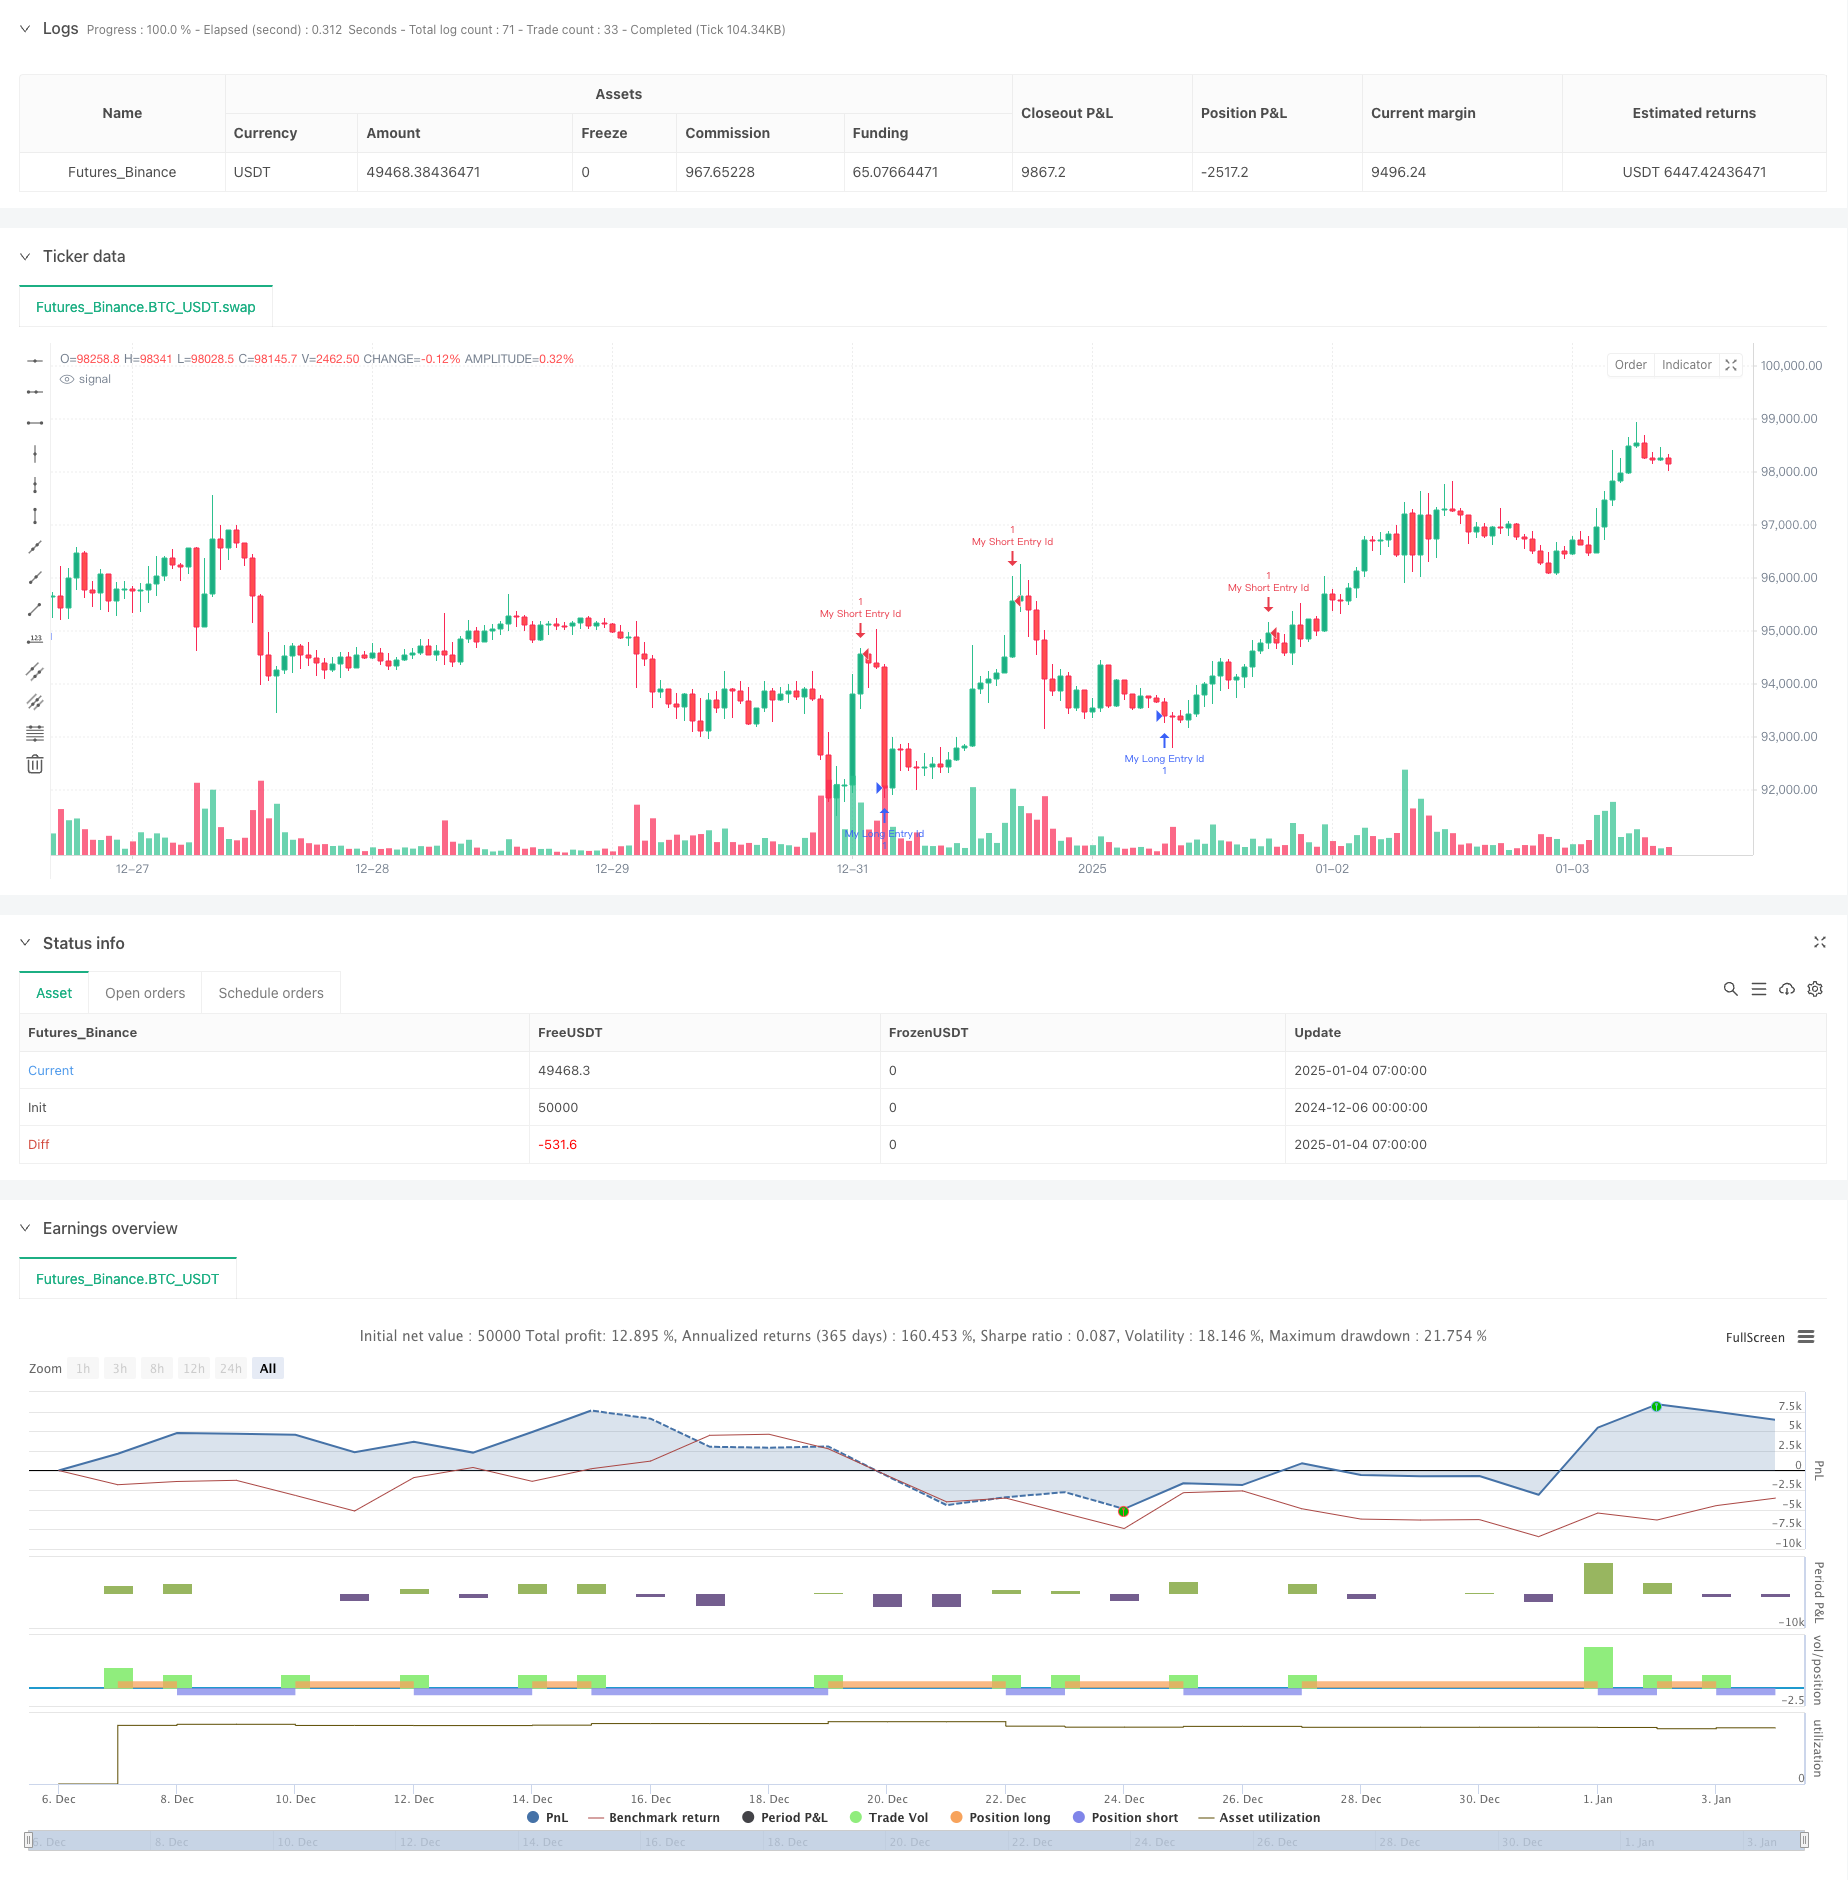
该策略是一个基于Supertrend指标的高级趋势跟踪交易系统,结合了多重信号确认机制和动态持仓管理。策略核心是通过ATR(真实波幅均值)来计算Supertrend线,并结合价格走势和持仓时间窗口来生成交易信号,实现对市场趋势的智能捕捉。
策略原理
策略采用了三层信号过滤机制:
- 基础趋势判断:使用Supertrend指标(参数:ATR周期10,因子3.0)识别主要趋势方向
- 方向确认系统:通过direction变量跟踪趋势变化,在趋势转向时生成交易信号
- 信号强化机制:在基本入场信号后的15-19个周期内,通过连续3根K线的走势来确认趋势的可靠性
策略在资金管理方面采用账户权益的15%作为单次交易量,这种保守的仓位控制有助于风险管理。
策略优势
- 多重信号确认:通过Supertrend指标和价格行为分析的结合,显著降低假信号
- 动态持仓控制:基于时间窗口的信号确认机制,避免过度交易
- 风险管理完善:采用百分比持仓策略,有效控制每笔交易的风险敞口
- 趋势适应性强:策略能够在不同市场环境下自适应调整,提高盈利稳定性
策略风险
- 趋势反转风险:在震荡市场中可能产生假信号,导致连续止损
- 参数敏感性:ATR周期和因子的设置对策略表现影响较大
- 滑点影响:在市场流动性不足时可能面临较大滑点
- 信号滞后:多重确认机制可能导致入场时机略有延迟
策略优化方向
- 引入波动率过滤:建议添加ATR标准差指标,在高波动率期间调整交易参数
- 优化信号确认机制:可考虑引入成交量作为辅助指标,提高信号可靠性
- 完善止损机制:建议增加追踪止损功能,更好地锁定利润
- 市场环境分类:可添加市场环境识别模块,在不同市场状态下使用不同的参数组合
总结
这是一个结构完善、逻辑严谨的趋势跟踪策略,通过多重信号确认机制和完善的风险管理体系,具有较好的实战应用价值。策略的可扩展性强,通过建议的优化方向可进一步提升其稳定性和盈利能力。 ||
Overview
This strategy is an advanced trend-following trading system based on the Supertrend indicator, incorporating multiple signal confirmation mechanisms and dynamic position management. The core of the strategy calculates the Supertrend line using ATR (Average True Range) and generates trading signals by combining price movements and position time windows to achieve intelligent market trend capture.
Strategy Principle
The strategy employs a three-layer signal filtering mechanism:
- Basic Trend Identification: Uses Supertrend indicator (parameters: ATR period 10, factor 3.0) to identify primary trend direction
- Direction Confirmation System: Tracks trend changes through direction variable, generating trading signals at trend reversals
- Signal Enhancement Mechanism: Confirms trend reliability through continuous 3-bar price action within 15-19 periods after basic entry signals
The strategy employs 15% of account equity as position size per trade, supporting conservative risk management.
Strategy Advantages
- Multiple Signal Confirmation: Significantly reduces false signals by combining Supertrend indicator and price action analysis
- Dynamic Position Control: Signal confirmation mechanism based on time windows prevents overtrading
- Robust Risk Management: Percentage-based position sizing effectively controls risk exposure per trade
- Strong Trend Adaptability: Strategy self-adapts to different market environments, improving profit stability
Strategy Risks
- Trend Reversal Risk: May generate false signals in choppy markets leading to consecutive stops
- Parameter Sensitivity: Strategy performance heavily depends on ATR period and factor settings
- Slippage Impact: May face significant slippage in low liquidity conditions
- Signal Lag: Multiple confirmation mechanisms might cause slight delays in entry timing
Strategy Optimization Directions
- Implement Volatility Filtering: Suggest adding ATR standard deviation indicator to adjust trading parameters during high volatility periods
- Optimize Signal Confirmation: Consider incorporating volume as a supplementary indicator to improve signal reliability
- Enhance Stop Loss Mechanism: Recommend adding trailing stop functionality for better profit protection
- Market Environment Classification: Add market state recognition module to use different parameter combinations in different market conditions
Summary
This is a well-structured and logically rigorous trend-following strategy with practical application value through its multiple signal confirmation mechanisms and comprehensive risk management system. The strategy's strong expandability allows for further stability and profitability improvements through the suggested optimization directions.[/trans]
Source (PineScript)
/*backtest
start: 2024-12-06 00:00:00
end: 2025-01-04 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Supertrend Strategy", overlay=true)
atrPeriod = input(10, "ATR Length")
factor = input.float(3.0, "Factor", step=0.01)

// Compute supertrend values
[supertrendValue, supertrendDirection] = ta.supertrend(factor, atrPeriod)
var float direction = na
if not na(supertrendDirection[1]) and supertrendDirection[1] != supertrendDirection
    direction := supertrendDirection > 0 ? 1 : -1

// Variables to track conditions
var int lastShortTime = na
var int lastLongTime = na

// Detecting short and long entries
if direction == -1
    strategy.entry("My Short Entry Id", strategy.short)
    lastShortTime := bar_index

if direction == 1
    strategy.entry("My Long Entry Id", strategy.long)
    lastLongTime := bar_index

// Custom signal logic
bool bullishSignal = false
bool bearishSignal = false

// Define bullish signal conditions
if not na(lastShortTime) and (bar_index - lastShortTime >= 15 and bar_index - lastShortTime <= 19)
    if close > open and close[1] > open[1] and close[2] > open[2]
        bullishSignal := true

// Define bearish signal conditions
if not na(lastLongTime) and (bar_index - lastLongTime >= 15 and bar_index - lastLongTime <= 19)
    if close < open and close[1] < open[1] and close[2] < open[2]
        bearishSignal := true

// Plot signals
if bullishSignal
    strategy.entry("Bullish Upward Signal", strategy.long)
    label.new(bar_index, close, text="Bullish", style=label.style_circle, color=color.green, textcolor=color.white)

if bearishSignal
    strategy.entry("Bearish Downward Signal", strategy.short)
    label.new(bar_index, close, text="Bearish", style=label.style_circle, color=color.red, textcolor=color.white)

// Optionally plot the strategy equity
//plot(strategy.equity, title="Equity", color=color.red, linewidth=2, style=plot.style_areabr)
Detail
https://www.fmz.com/strategy/477519
Last Modified
2025-01-06 11:06:26