
7.2 KiB
Name
基于RSI超买超卖的自适应市场交易策略-Adaptive-Market-Trading-Strategy-Based-on-RSI-Overbought-Oversold
Author
ianzeng123
Strategy Description
[trans]
概述
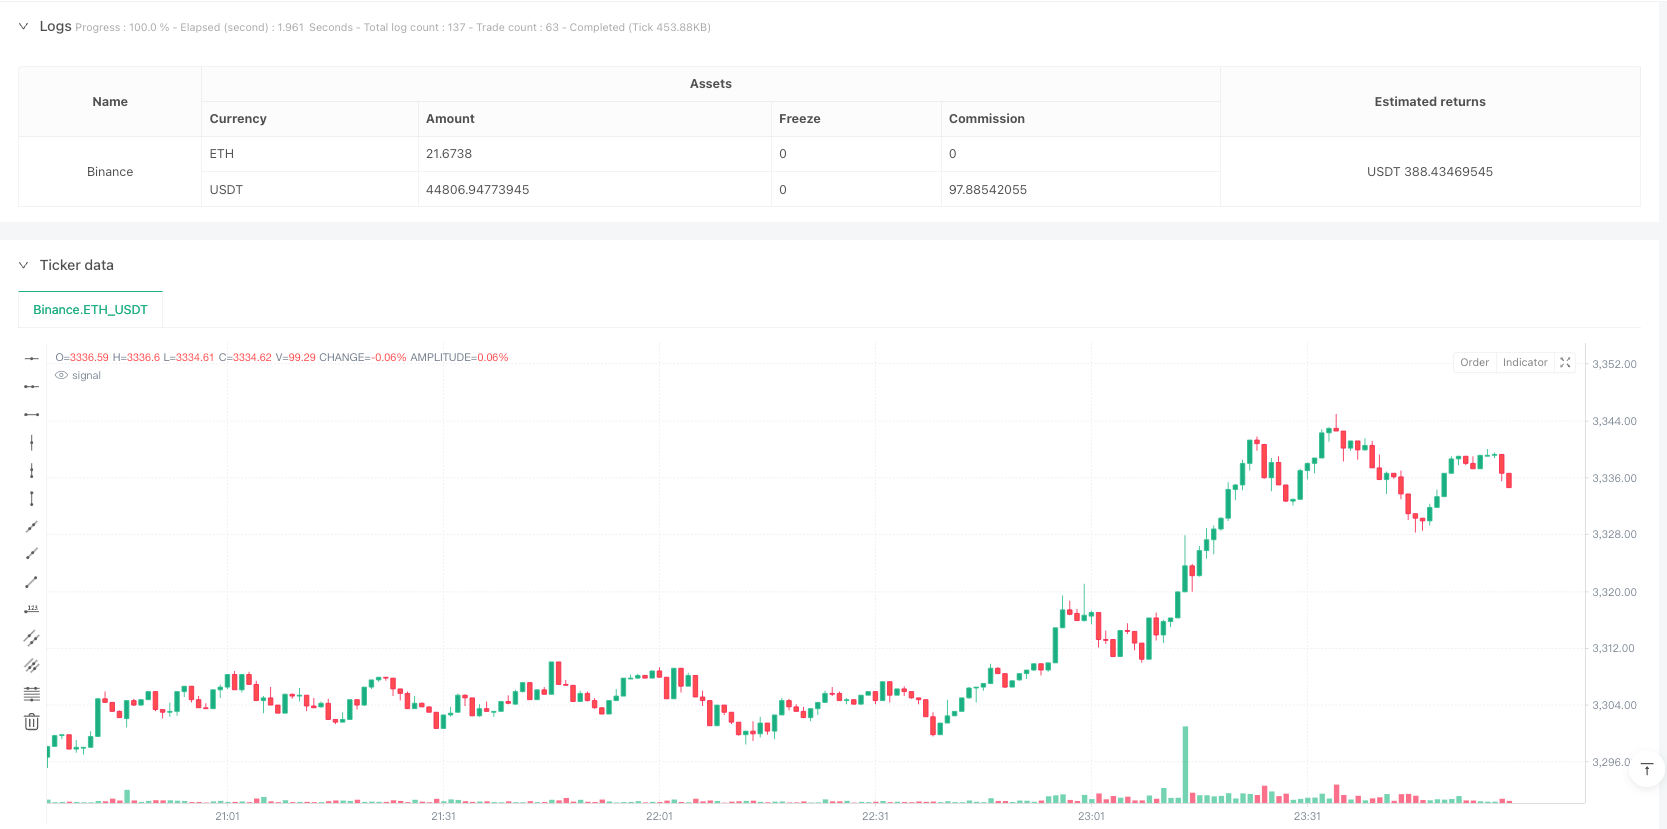
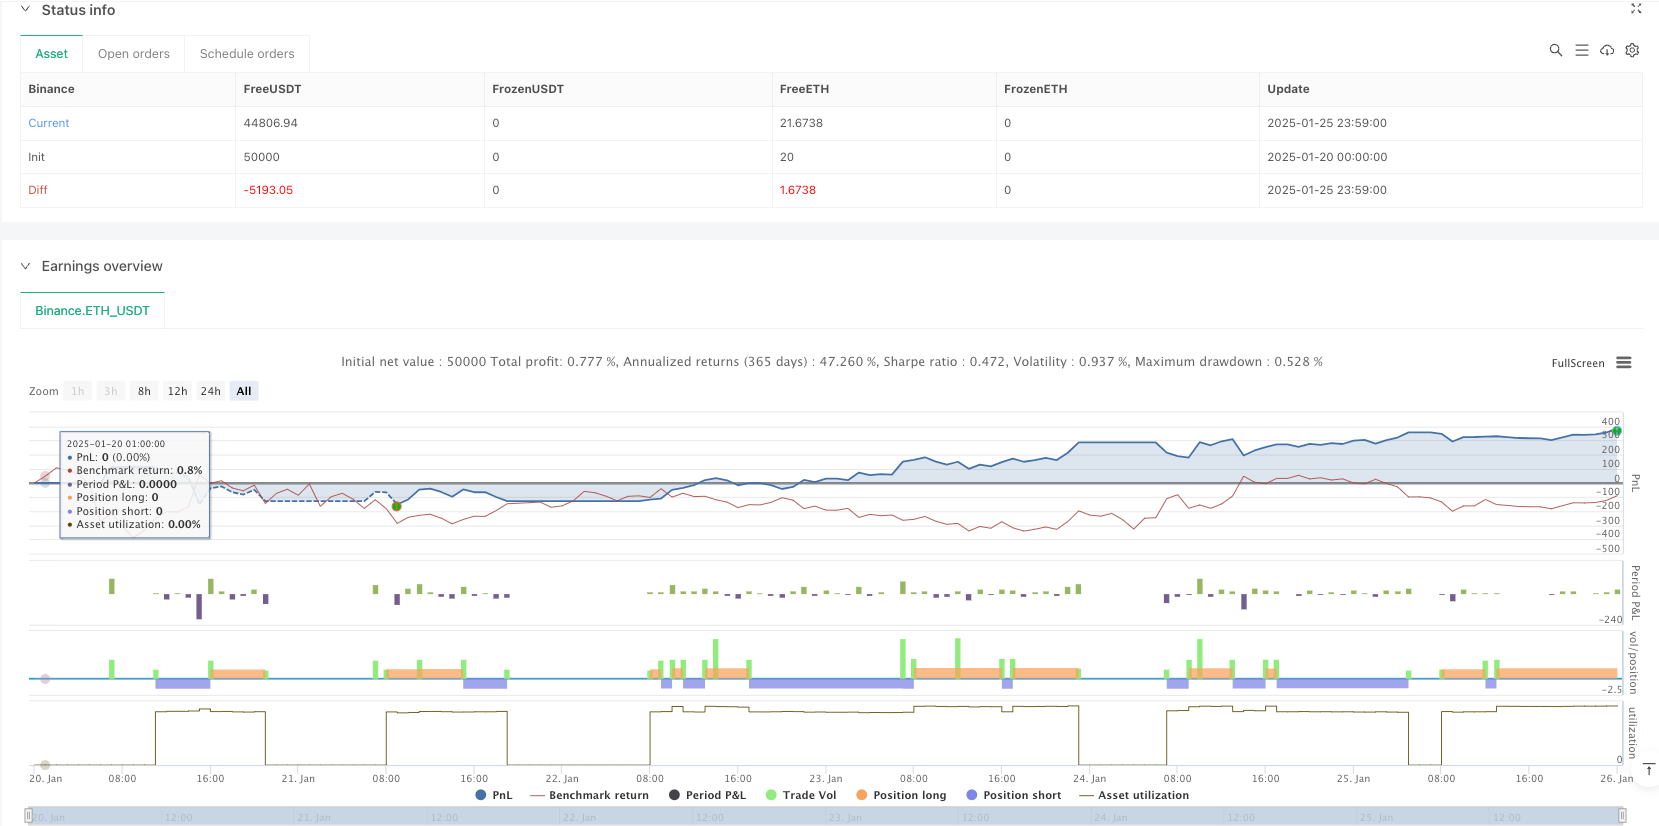
该策略是一个基于相对强弱指标(RSI)的自适应交易系统。策略在M5时间周期上运行,通过监控RSI指标的超买超卖水平来识别潜在的交易机会。系统设置了固定的止损和止盈比例,并限制在特定的交易时段内执行。策略采用资金百分比管理方式,每次交易投入总资金的10%。
策略原理
策略的核心是利用RSI指标在14周期内的波动特征进行交易。当RSI低于30的超卖水平时,系统发出做多信号;当RSI高于70的超买水平时,系统发出做空信号。交易仅在6:00-17:00的时间窗口内执行,这有助于避开市场波动较大的时段。每笔交易都设置了1%的止损和2%的止盈水平,这种非对称的风险收益比有利于长期盈利。
策略优势
- 指标选择科学:RSI是一个经过市场验证的动量指标,能够有效捕捉价格超涨超跌的反转机会。
- 风险控制完善:策略采用固定百分比的止损止盈设置,可以有效控制每笔交易的风险。
- 时间管理合理:通过限制交易时间窗口,避免了市场流动性差的时段。
- 资金管理稳健:每次交易使用10%的资金比例,既保证了收益潜力,又避免了过度冒险。
策略风险
- 趋势市场风险:在强趋势市场中,RSI可能长期处于超买或超卖区间,导致假信号增多。
- 滑点风险:在行情剧烈波动时,实际成交价格可能与信号价格存在较大偏差。
- 固定参数风险:RSI的参数和超买超卖阈值固定,可能不适应所有市场环境。
策略优化方向
- 引入趋势过滤器:可以添加移动平均线等趋势指标,在主趋势方向上交易。
- 动态参数优化:考虑使用自适应的RSI周期和超买超卖阈值,以适应不同的市场环境。
- 优化交易时间:可以根据市场统计数据,进一步细化最佳交易时段。
- 完善资金管理:可以根据波动率动态调整持仓规模,实现更精细的风险控制。
总结
这是一个设计合理、逻辑清晰的交易策略。通过RSI指标捕捉市场超买超卖机会,结合严格的风险控制和时间管理,具有较好的实战应用价值。策略的主要优势在于系统的完整性和操作的明确性,但在实盘交易中仍需注意市场环境对策略表现的影响,并根据实际情况进行适当的参数优化。 ||
Overview
This strategy is an adaptive trading system based on the Relative Strength Index (RSI). Operating on the M5 timeframe, it identifies potential trading opportunities by monitoring RSI overbought and oversold levels. The system implements fixed stop-loss and take-profit ratios and operates within specific trading hours. The strategy employs percentage-based money management, investing 10% of total capital per trade.
Strategy Principles
The core mechanism relies on RSI fluctuations over a 14-period cycle. The system generates long signals when RSI falls below the oversold level of 30 and short signals when RSI exceeds the overbought level of 70. Trading is restricted to the 6:00-17:00 time window, helping avoid highly volatile market periods. Each trade is set with a 1% stop-loss and 2% take-profit level, creating an asymmetric risk-reward ratio favorable for long-term profitability.
Strategy Advantages
- Scientific Indicator Selection: RSI is a market-proven momentum indicator effective at capturing price reversal opportunities in overbought and oversold conditions.
- Comprehensive Risk Control: The strategy employs fixed percentage-based stop-loss and take-profit settings, effectively controlling risk per trade.
- Rational Time Management: By restricting trading hours, the strategy avoids periods of poor market liquidity.
- Robust Money Management: Using 10% capital allocation per trade ensures good profit potential while avoiding excessive risk.
Strategy Risks
- Trend Market Risk: In strong trend markets, RSI may remain in overbought or oversold zones for extended periods, increasing false signals.
- Slippage Risk: During volatile market conditions, actual execution prices may significantly deviate from signal prices.
- Fixed Parameter Risk: The fixed RSI parameters and overbought/oversold thresholds may not adapt to all market conditions.
Optimization Directions
- Introduce Trend Filters: Add trend indicators like moving averages to trade in the direction of the main trend.
- Dynamic Parameter Optimization: Consider using adaptive RSI periods and overbought/oversold thresholds to suit different market conditions.
- Optimize Trading Hours: Further refine optimal trading periods based on market statistics.
- Enhance Money Management: Dynamically adjust position sizes based on volatility for more precise risk control.
Summary
This is a well-designed trading strategy with clear logic. It captures market overbought and oversold opportunities through the RSI indicator, combined with strict risk control and time management, demonstrating good practical application value. The strategy's main strengths lie in its system completeness and operational clarity, but attention must be paid to market conditions' impact on strategy performance in live trading, with appropriate parameter optimization based on actual circumstances.[/trans]
Source (PineScript)
/*backtest
start: 2025-01-20 00:00:00
end: 2025-01-26 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Binance","currency":"ETH_USDT"}]
*/

//@version=6
strategy("Gold Trading RSI", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=10)

// Input parameters configuration
rsi_length = input.int(14, title="RSI Period") // RSI period
rsi_overbought = input.int(70, title="RSI Overbought Level") // Overbought level
rsi_oversold = input.int(30, title="RSI Oversold Level") // Oversold level
sl_percent = input.float(1.0, title="Stop Loss (%)") / 100 // Stop loss percentage
tp_percent = input.float(2.0, title="Take Profit (%)") / 100 // Take profit percentage

capital = strategy.equity // Current equity

// Calculate RSI on the 5-minute timeframe
rsi_m5 = ta.rsi(close, rsi_length)

// Get the current hour based on the chart's timezone
current_hour = hour(time)

// Limit trading to the hours between 6:00 AM and 5:00 PM
is_trading_time = current_hour >= 6 and current_hour < 17

// Entry conditions
long_condition = is_trading_time and rsi_m5 < rsi_oversold
short_condition = is_trading_time and rsi_m5 > rsi_overbought

// Calculate Stop Loss and Take Profit levels
sl_long = close * (1 - sl_percent)
tp_long = close * (1 + tp_percent)

sl_short = close * (1 + sl_percent)
tp_short = close * (1 - tp_percent)

// Enter trade
if (long_condition)
    strategy.entry("Buy", strategy.long)
    strategy.exit("Exit Buy", from_entry="Buy", stop=sl_long, limit=tp_long)

if (short_condition)
    strategy.entry("Sell", strategy.short)
    strategy.exit("Exit Sell", from_entry="Sell", stop=sl_short, limit=tp_short)
Detail
https://www.fmz.com/strategy/482895
Last Modified
2025-02-27 17:28:19