
10 KiB
Name
基于Chaikin资金流量CMF指标策略This-strategy-generates-trading-signals-based-on-the-Chaikin-Money-Flow-CMF
Author
ChaoZhang
Strategy Description
 CASHISKING | CASHISKING
CMF, EMA, SMA
[trans]
概述
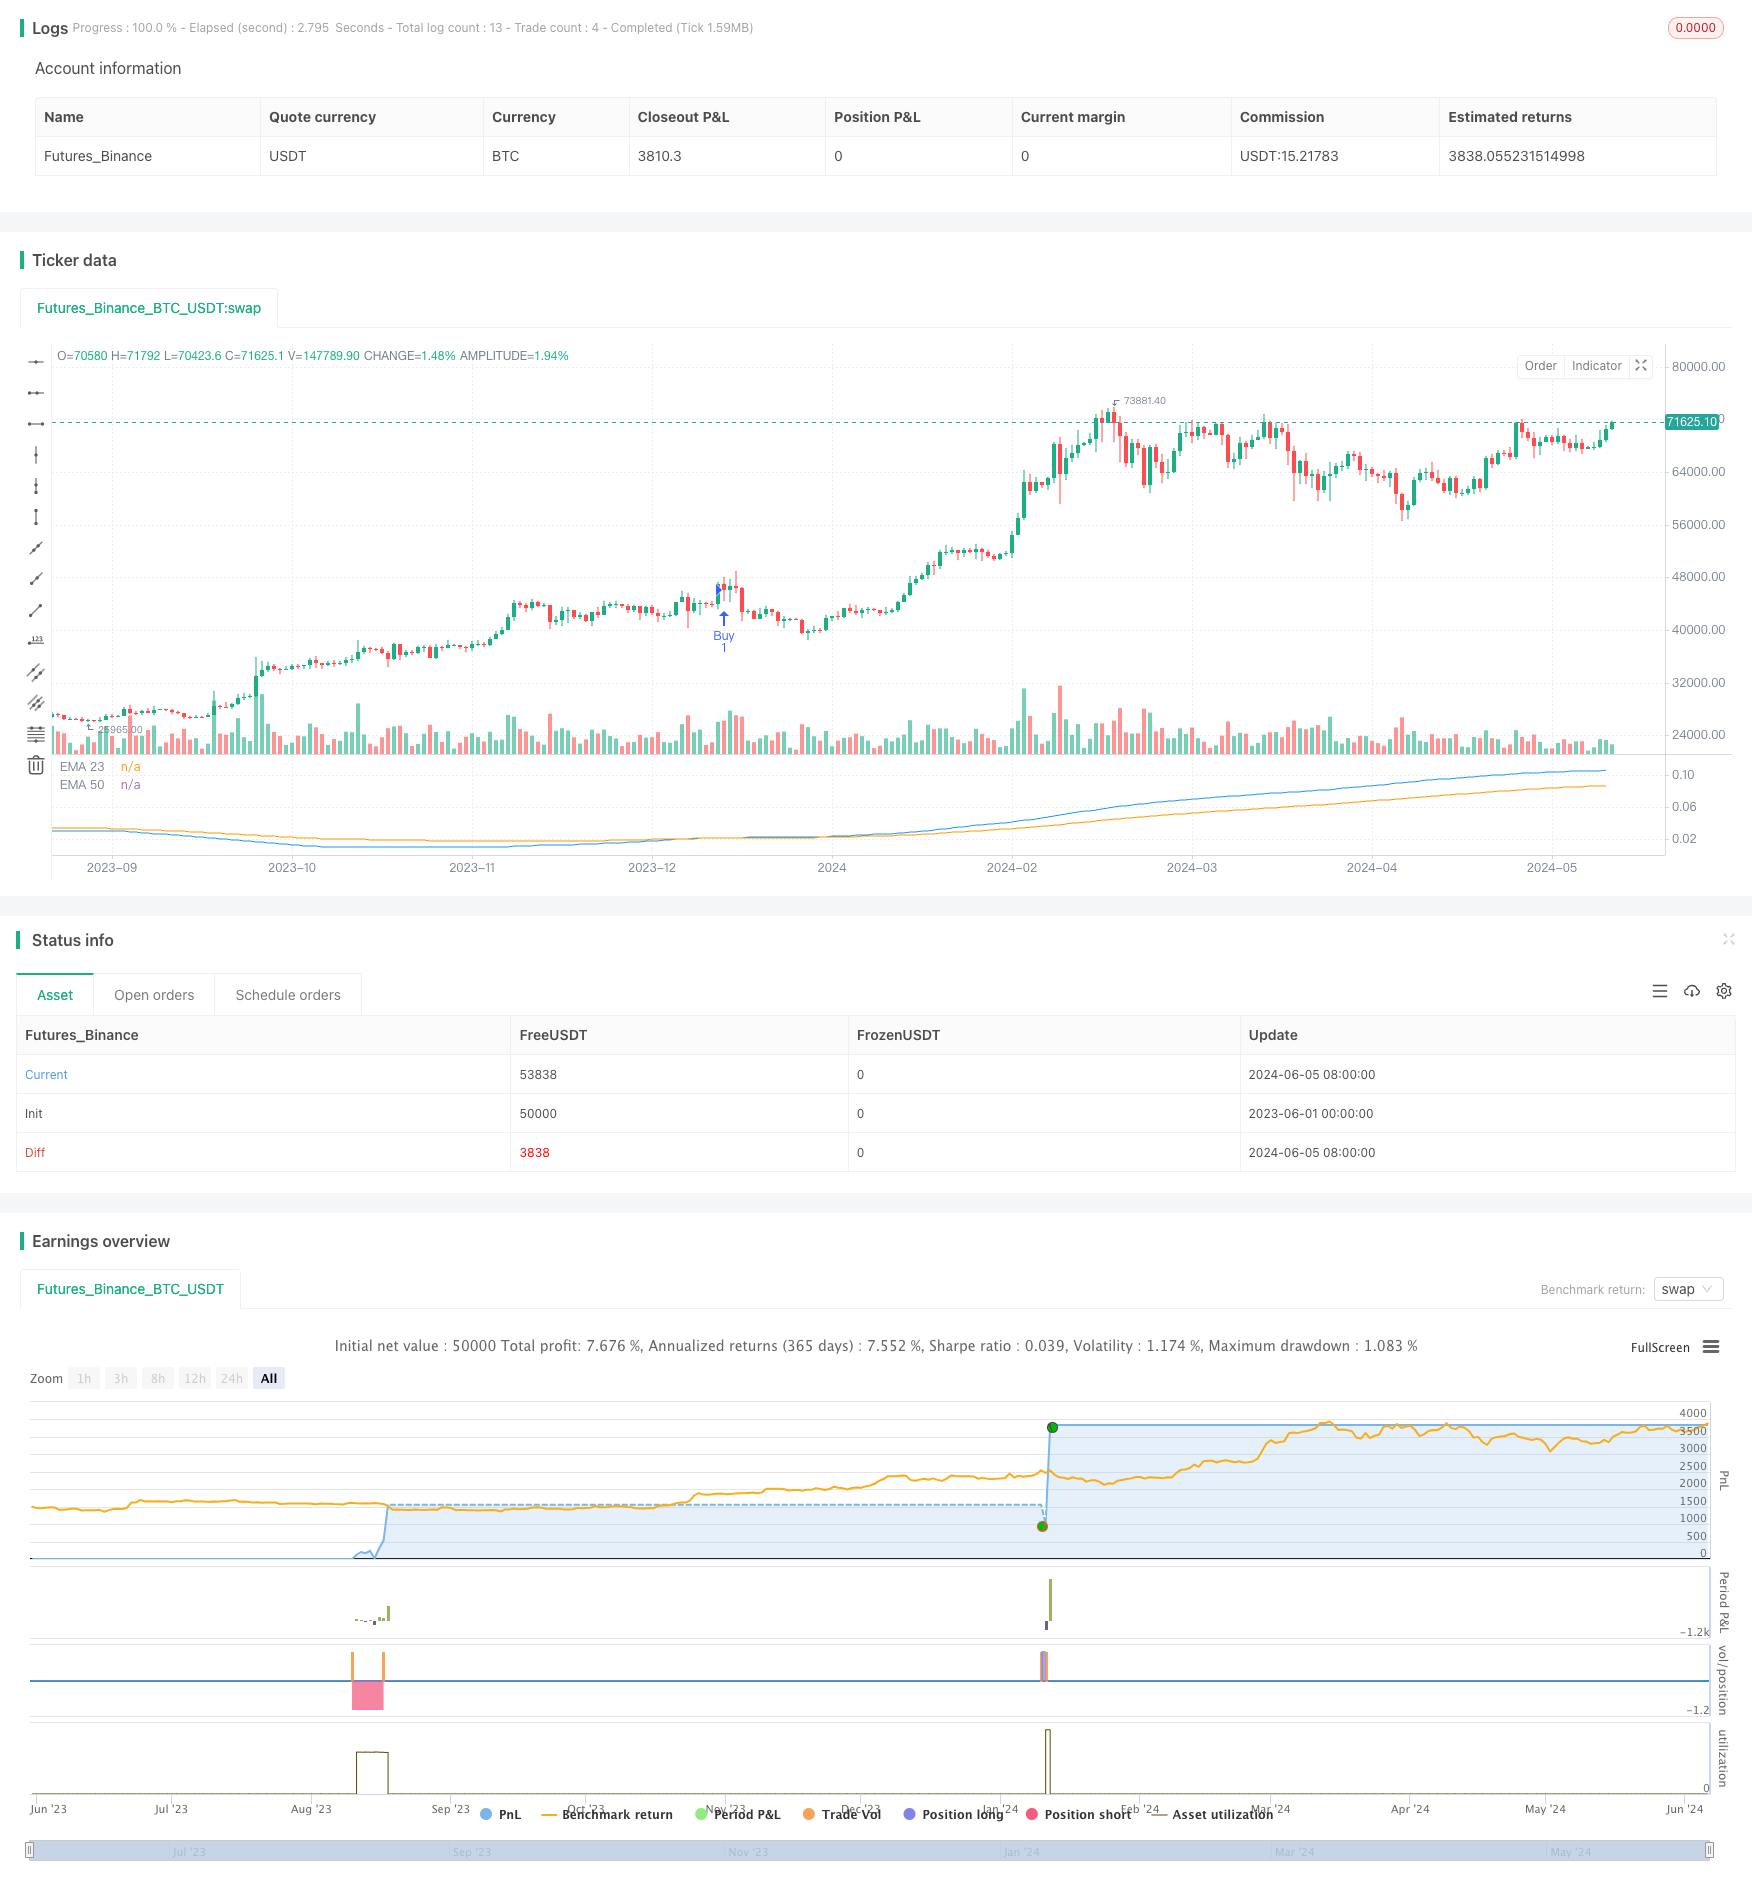
该策略基于Chaikin资金流量(CMF)指标和指数移动平均线(EMA)来生成交易信号。首先计算指定周期内的CMF值,然后使用两条不同周期的EMA来平滑CMF数据。当快速EMA在慢速EMA上方交叉时产生买入信号,反之则产生卖出信号。该策略还设置了止损和止盈条件,以控制风险和锁定利润。
策略原理
- 计算指定周期内的Chaikin资金流量(CMF)值,CMF指标结合了价格和成交量数据,用于衡量资金流入和流出的强度。
- 使用两条不同周期的指数移动平均线(EMA)对CMF数据进行平滑处理,快速EMA用于捕捉短期趋势,慢速EMA用于确定长期趋势。
- 当快速EMA在慢速EMA上方交叉时,产生买入信号;当快速EMA在慢速EMA下方交叉时,产生卖出信号。
- 在产生交易信号后,策略会等待两根K线的确认,以避免假信号。
- 设置止损和止盈条件,止损价格为开仓价格的一定百分比,止盈价格为开仓价格的一定百分比。
优势分析
- 结合价格和成交量数据:CMF指标综合考虑了价格和成交量数据,能够更全面地反映市场资金流动情况,提供更可靠的交易信号。
- 趋势跟踪:通过使用不同周期的EMA,策略能够同时捕捉短期和长期趋势,适应不同的市场环境。
- 信号确认:在产生交易信号后,策略会等待两根K线的确认,有效过滤掉一些假信号,提高交易的成功率。
- 风险控制:设置了止损和止盈条件,能够有效控制单笔交易的风险,同时锁定已获得的利润。
风险分析
- 参数优化:策略的表现依赖于CMF和EMA的周期选择,不同的市场环境可能需要不同的参数设置,因此需要定期进行参数优化。
- 趋势识别:在震荡市或者趋势转折点,策略可能会产生较多的假信号,导致频繁交易和资金损失。
- 滑点和交易成本:频繁的交易可能会增加滑点和交易成本,影响策略的整体收益。
优化方向
- 动态调整参数:根据市场环境的变化,动态调整CMF和EMA的周期参数,以适应不同的市场状态。
- 引入其他指标:结合其他技术指标,如相对强弱指数(RSI)、平均真实波幅(ATR)等,以提高趋势识别的准确性和信号的可靠性。
- 优化止损和止盈:根据市场波动性和风险偏好,动态调整止损和止盈的百分比,以更好地控制风险和锁定利润。
- 加入仓位管理:根据市场趋势和信号强度,动态调整仓位大小,在趋势明确时加大仓位,在不确定时减小仓位。
总结
该策略利用Chaikin资金流量指标和指数移动平均线,结合价格和成交量数据,以趋势跟踪为主要思路,同时设置了止损和止盈条件来控制风险。策略的优势在于能够综合考虑多方面因素,捕捉不同时间尺度的趋势,但在参数设置和趋势识别方面仍有优化空间。未来可以通过动态调整参数、引入其他指标、优化止损止盈以及加入仓位管理等方式,进一步提高策略的稳定性和盈利能力。
||
Overview
This strategy generates trading signals based on the Chaikin Money Flow (CMF) indicator and Exponential Moving Averages (EMA). It first calculates the CMF values for a specified period, then uses two EMAs with different periods to smooth the CMF data. A buy signal is generated when the fast EMA crosses above the slow EMA, while a sell signal is generated when the fast EMA crosses below the slow EMA. The strategy also sets stop-loss and take-profit conditions to manage risk and lock in profits.
Strategy Principles
- Calculate the Chaikin Money Flow (CMF) values for a specified period. CMF incorporates both price and volume data to measure the strength of money flow into and out of the market.
- Apply two Exponential Moving Averages (EMAs) with different periods to smooth the CMF data. The fast EMA captures short-term trends, while the slow EMA identifies long-term trends.
- Generate a buy signal when the fast EMA crosses above the slow EMA, and a sell signal when the fast EMA crosses below the slow EMA.
- After a trading signal is generated, the strategy waits for confirmation from two candles to avoid false signals.
- Set stop-loss and take-profit conditions. The stop-loss price is a certain percentage of the entry price, while the take-profit price is a certain percentage of the entry price.
Advantage Analysis
- Combines price and volume data: The CMF indicator comprehensively considers both price and volume data, providing a more reliable reflection of market money flow and generating more accurate trading signals.
- Trend tracking: By utilizing EMAs with different periods, the strategy can capture both short-term and long-term trends, adapting to various market environments.
- Signal confirmation: After a trading signal is generated, the strategy waits for confirmation from two candles, effectively filtering out some false signals and improving the success rate of trades.
- Risk management: The strategy incorporates stop-loss and take-profit conditions, which effectively controls the risk of individual trades while securing obtained profits.
Risk Analysis
- Parameter optimization: The performance of the strategy depends on the selection of CMF and EMA periods. Different market environments may require different parameter settings, necessitating periodic parameter optimization.
- Trend recognition: In choppy markets or at trend turning points, the strategy may generate more false signals, leading to frequent trades and capital losses.
- Slippage and trading costs: Frequent trading may increase slippage and trading costs, affecting the overall profitability of the strategy.
Optimization Directions
- Dynamic parameter adjustment: Dynamically adjust the CMF and EMA period parameters based on changes in market conditions to adapt to different market states.
- Incorporate other indicators: Combine other technical indicators, such as the Relative Strength Index (RSI) and Average True Range (ATR), to improve the accuracy of trend recognition and the reliability of signals.
- Optimize stop-loss and take-profit: Dynamically adjust the stop-loss and take-profit percentages based on market volatility and risk preferences to better manage risk and lock in profits.
- Implement position sizing: Dynamically adjust position sizes based on market trends and signal strength. Increase position sizes when trends are clear and reduce position sizes during uncertain periods.
Summary
This strategy utilizes the Chaikin Money Flow indicator and Exponential Moving Averages, combining price and volume data with a primary focus on trend tracking. It also sets stop-loss and take-profit conditions to manage risk. The strategy's advantages lie in its ability to comprehensively consider multiple factors and capture trends on different time scales. However, there is still room for optimization in parameter settings and trend recognition. In the future, the strategy's stability and profitability can be further improved through dynamic parameter adjustment, incorporation of other indicators, optimization of stop-loss and take-profit, and implementation of position sizing. [/trans]
Source (PineScript)
/*backtest
start: 2023-06-01 00:00:00
end: 2024-06-06 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("CASHISKING", overlay=false)

// Kullanıcı girişleri ile parametreler
cmfPeriod = input.int(200, "CMF Periyodu", minval=1)
emaFastPeriod = input.int(80, "Hızlı EMA Periyodu", minval=1)
emaSlowPeriod = input.int(160, "Yavaş EMA Periyodu", minval=1)
stopLossPercent = input.float(3, "Stop Loss Yüzdesi", minval=0.1) / 100
stopGainPercent = input.float(5, "Stop Gain Yüzdesi", minval=0.1) / 100

// CMF hesaplama fonksiyonu
cmfFunc(close, high, low, volume, length) =>
    clv = ((close - low) - (high - close)) / (high - low)
    valid = not na(clv) and not na(volume) and (high != low)
    clv_volume = valid ? clv * volume : na
    sum_clv_volume = ta.sma(clv_volume, length)
    sum_volume = ta.sma(volume, length)
    cmf = sum_volume != 0 ? sum_clv_volume / sum_volume : na
    cmf

// CMF değerlerini hesaplama
cmf = cmfFunc(close, high, low, volume, cmfPeriod)

// EMA hesaplamaları
emaFast = ta.ema(cmf, emaFastPeriod)
emaSlow = ta.ema(cmf, emaSlowPeriod)

// Göstergeleri çiz
plot(emaFast, color=color.blue, title="EMA 23")
plot(emaSlow, color=color.orange, title="EMA 50")

// Alım ve Satım Sinyalleri
crossOverHappened = ta.crossover(emaFast, emaSlow)
crossUnderHappened = ta.crossunder(emaFast, emaSlow)

// Kesişme sonrası bekleme sayacı
var int crossOverCount = na
var int crossUnderCount = na

if (crossOverHappened)
    crossOverCount := 0

if (crossUnderHappened)
    crossUnderCount := 0

if (not na(crossOverCount))
    crossOverCount += 1

if (not na(crossUnderCount))
    crossUnderCount += 1

// Alım ve Satım işlemleri
if (crossOverCount == 2)
    strategy.entry("Buy", strategy.long)
    crossOverCount := na  // Sayaç sıfırlanır

if (crossUnderCount == 2)
    strategy.entry("Sell", strategy.short)
    crossUnderCount := na  // Sayaç sıfırlanır

// Stop Loss ve Stop Gain hesaplama
longStopPrice = strategy.position_avg_price * (1 - stopLossPercent)
shortStopPrice = strategy.position_avg_price * (1 + stopLossPercent)
longTakeProfitPrice = strategy.position_avg_price * (1 + stopGainPercent)
shortTakeProfitPrice = strategy.position_avg_price * (1 - stopGainPercent)

// Stop Loss ve Stop Gain'i uygula
if (strategy.position_size > 0 and strategy.position_avg_price > 0)
    strategy.exit("Stop", "Buy", stop=longStopPrice, limit=longTakeProfitPrice)
else if (strategy.position_size < 0 and strategy.position_avg_price > 0)
    strategy.exit("Stop", "Sell", stop=shortStopPrice, limit=shortTakeProfitPrice)
Detail
https://www.fmz.com/strategy/453670
Last Modified
2024-06-07 17:05:04