
7.8 KiB
Name
基于频道和线性回归的Hull-MA摆荡策略Hull-MA-Channel-and-Linear-Regression-Swing-Trading-Strategy
Author
ChaoZhang
Strategy Description
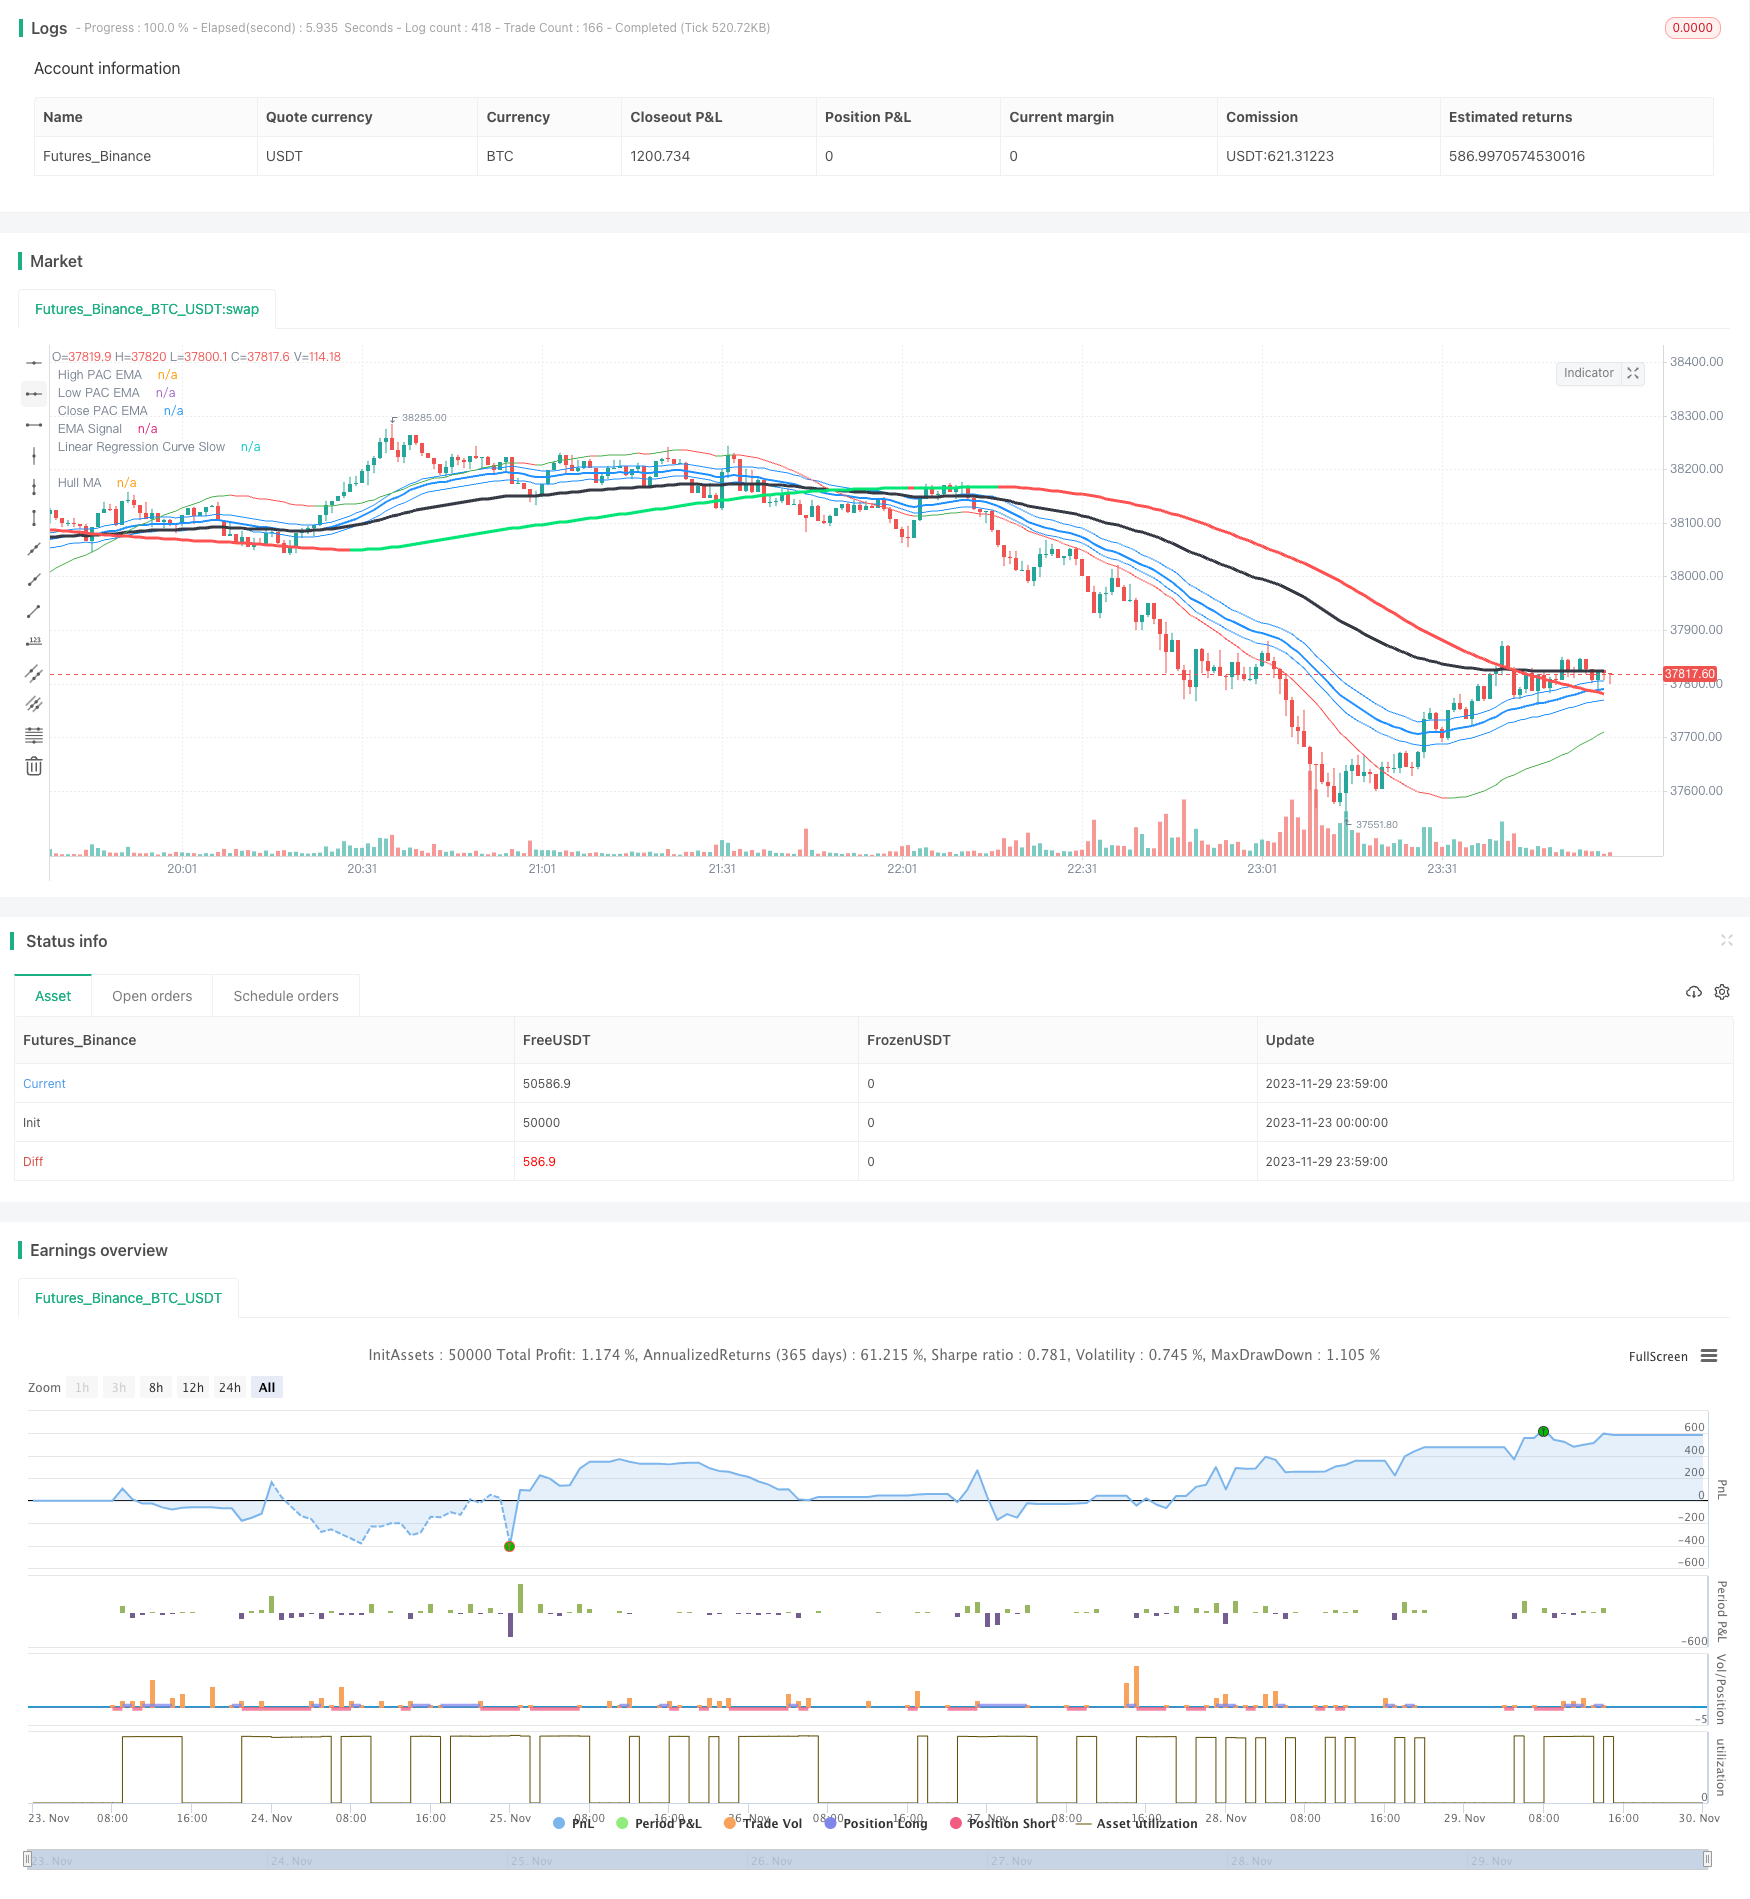 [trans]
概述
本策略是一个结合Hull MA、价格频道、EMA信号和线性回归的摆荡交易策略。该策略利用Hull MA判断市场趋势方向,价格频道和线性回归判断底部区域,EMA信号判断入市时机,以捕捉中短线趋势。
策略原理
该策略主要由以下几部分指标组成:
- Hull MA
- Hull MA一般参数期间为337,代表中长线趋势方向
- 当2倍18周期WMA高于337周期WMA时为多头市场,反之为空头市场
- 价格频道
- 价格频道由高低价EMA组成,代表容易形成支撑和阻力的区域
- EMA信号
- EMA信号期间一般为89周期,代表短线趋势和入市信号
- 线性回归
- 快线6周期,判断底部和突破
- 慢线89周期,判断中长线趋势方向
入场逻辑:
多头入场:Hull MA向上且价格高于上轨,线性回归向上穿越短期EMA 空头入场:Hull MA向下且价格低于下轨,线性回归向下穿越短期EMA
出场逻辑:
多头出场:价格低于下轨且穿越线性回归向下 空头出场:价格高于上轨且穿越线性回归向上
优势分析
该策略具有以下优势:
- 多指标组合,判断更准确
- Hull MA判断主趋势,频道判断支撑压力,EMA判断入场时机
- 摆荡交易,捕捉中短线趋势
- 策略为反转为主的摆荡交易策略,能捕捉每个中短线周期的趋势
- 风险可控,回撤较小
- 策略只在高概率区域发出信号,避免追高杀跌
风险分析
该策略也存在一定的风险:
- 参数优化空间有限
- 主要参数如EMA周期较为固定,优化空间小
- 震荡行情中可能亏损
- 价格横盘震荡时,止损可能被触发
- 需要一定的技术分析基础
- 策略思路需要一定的价格行为和指标知识,不适合所有人
可以从以下几点进行优化:
- 调整止损策略,例如余震止损
- 优化进场离场逻辑
- 增加其他指标过滤,例如MACD
总结
本策略综合运用Hull MA、价格频道、EMA和线性回归等多个指标,形成一个较为完整的中短线摆荡交易策略。相比单一指标,该策略可以大大提高判断准确性,在趋势和反转中捕捉利润。但也存在一定风险,需要技术分析基础。通过参数调整和进场离场逻辑优化,可以进一步提高策略稳定性。
||
Overview
This is a swing trading strategy that combines Hull MA, price channel, EMA signal and linear regression. It uses Hull MA to determine market trend direction, price channel and linear regression to identify bottom area, EMA signal to time market entry, in order to capture medium-term trends.
Strategy Logic
The strategy consists of the following main indicators:
- Hull MA
- Typical period of Hull MA is 337, representing medium to long term trend direction
- When 2 times 18-period WMA is above 337-period WMA, it's a bull market, otherwise it's a bear market
- Price Channel
- Price channel plots EMA high and EMA low, representing support and resistance area
- EMA Signal
- Typical period is 89, representing short-term trend and entry signal
- Linear Regression
- Fast line of 6 period for bottom and breakout
- Slow line of 89 period for medium to long term trend
Entry Logic:
Long Entry: Hull MA pointing up and price above upper band, linear regression crossing up EMA signal Short Entry: Hull MA pointing down and price below lower band, linear regression crossing down EMA signal
Exit Logic:
Long Exit: Price below lower band and crossing down linear regression Short Exit: Price above upper band and crossing up linear regression
Advantage Analysis
The strategy has the following advantages:
- Higher accuracy with multiple indicators
- Hull MA for main trend, channel for support/resistance, EMA for entry
- Swing trading to capture medium-term trends
- Strategy mainly reversals to capture each medium-term cycle
- Controllable risk and smaller drawdown
- Signal only generated at high probability area, avoiding chase high kill low
Risk Analysis
There are also some risks:
- Limited optimization space
- Main parameters like EMA period is fixed, with small optimization space
- May lose in range-bound market
- Stop loss may be triggered in sideways range
- Need some technical analysis knowledge
- Strategy logic needs price action and indicator knowledge, not suitable for everyone
Improvements:
- Adjust stop loss strategy, e.g. trailing stop loss
- Optimize entry and exit logic
- Add other filter indicators like MACD
Summary
The strategy combines Hull MA, price channel, EMA and linear regression for a complete medium-term swing trading strategy. Compared to single indicator strategies, it improves accuracy significantly in catching trends and reversals. But there are still risks, requiring technical analysis knowledge. Further improvements on parameters and logic can enhance stability.
[/trans]
Strategy Arguments
| Argument | Default | Description |
|---|---|---|
| v_input_1 | 377 | HullMA Period |
| v_input_2 | 89 | EMA Signal |
| v_input_3 | 34 | High Low channel Length |
| v_input_4 | 89 | Linear Regression Length |
Source (PineScript)
/*backtest
start: 2023-11-23 00:00:00
end: 2023-11-30 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy("Swing Hull/SonicR/EMA/Linear Regression Strategy", overlay=true)
//Hull MA
n=input(title="HullMA Period",defval=377)
//
n2ma=2*wma(close,round(n/2))
nma=wma(close,n)
diff=n2ma-nma
sqn=round(sqrt(n))
//
n2ma1=2*wma(close[1],round(n/2))
nma1=wma(close[1],n)
diff1=n2ma1-nma1
sqn1=round(sqrt(n))
//
n1=wma(diff,sqn)
n2=wma(diff1,sqn)
condDown = n2 >= n1
condUp = condDown != true
col =condUp ? lime : condDown ? red : yellow
plot(n1,title="Hull MA", color=col,linewidth=3)
// SonicR + Line reg
EMA = input(defval=89, title="EMA Signal")
HiLoLen     = input(34, minval=2,title="High Low channel Length")
lr     = input(89, minval=2,title="Linear Regression Length")
pacC        = ema(close,HiLoLen)
pacL        = ema(low,HiLoLen)
pacH        = ema(high,HiLoLen)
DODGERBLUE = #1E90FFFF
// Plot the Price Action Channel (PAC) base on EMA high,low and close//
L=plot(pacL, color=DODGERBLUE, linewidth=1, title="High PAC EMA",transp=90)
H=plot(pacH, color=DODGERBLUE, linewidth=1, title="Low PAC EMA",transp=90)
C=plot(pacC, color=DODGERBLUE, linewidth=2, title="Close PAC EMA",transp=80)
//Moving Average//
signalMA =ema(close,EMA)
plot(signalMA,title="EMA Signal",color=black,linewidth=3,style=line)
linereg = linreg(close, lr, 0)
lineregf = linreg(close, HiLoLen, 0)
cline=linereg>linereg[1]?green:red
cline2= lineregf>lineregf[1]?green:red
plot(linereg, color = cline, title = "Linear Regression Curve Slow", style = line, linewidth = 1)
//plot(lineregf, color = cline2, title = "Linear Regression Curve Fast", style = line, linewidth = 1)
longCondition = n1>n2
shortCondition = longCondition != true
closeLong =  lineregf-pacH>(pacH-pacL)*2 and close<lineregf and linereg>signalMA
closeShort = pacL-lineregf>(pacH-pacL)*2 and close>lineregf and linereg<signalMA
if shortCondition
    if (close[0] < signalMA[0] and close[1] > pacL[1] and linereg>pacL and close<n1 and pacL<n1) //cross entry
        strategy.entry("SHORT", strategy.short, comment="Short")
strategy.close("SHORT", when=closeShort) //output logic
if longCondition // swing condition
    if (close[0] > signalMA[0] and close[1] < pacH[1] and linereg<pacH and close>n1 and pacH>n1) //cross entry
        strategy.entry("LONG", strategy.long, comment="Long")
strategy.close("LONG", when=closeLong) //output logic
Detail
https://www.fmz.com/strategy/433948
Last Modified
2023-12-01 16:47:01