
14 KiB
Name
基于量化指标的蜡烛情绪动量趋势交易策略-Candlestick-Emotion-Momentum-Trend-Trading-Strategy-Based-on-Quantitative-Indicators
Author
ianzeng123
Strategy Description
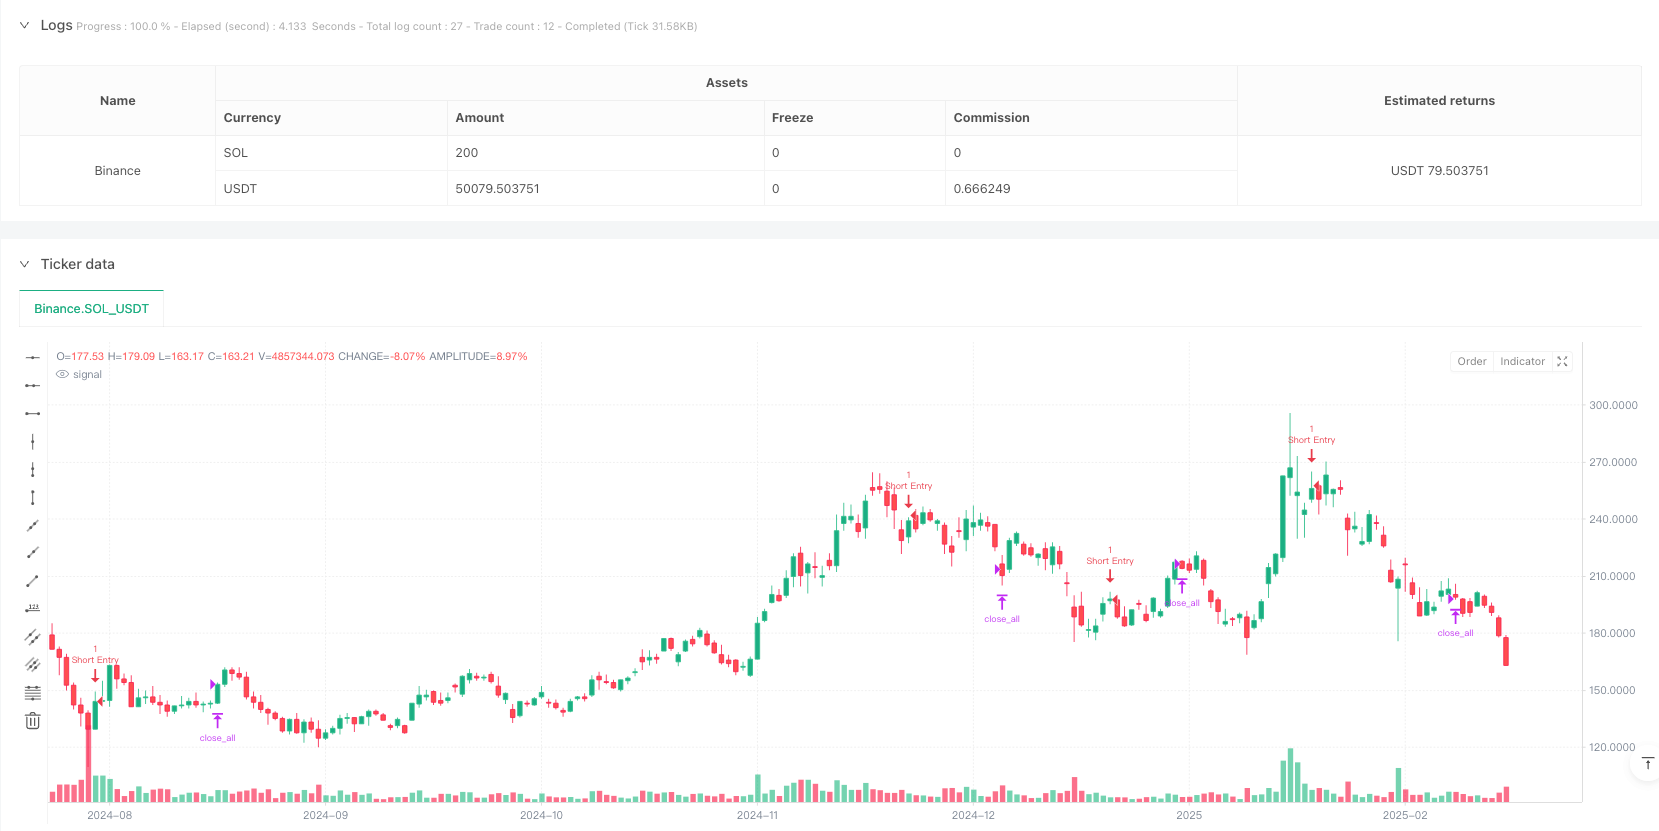
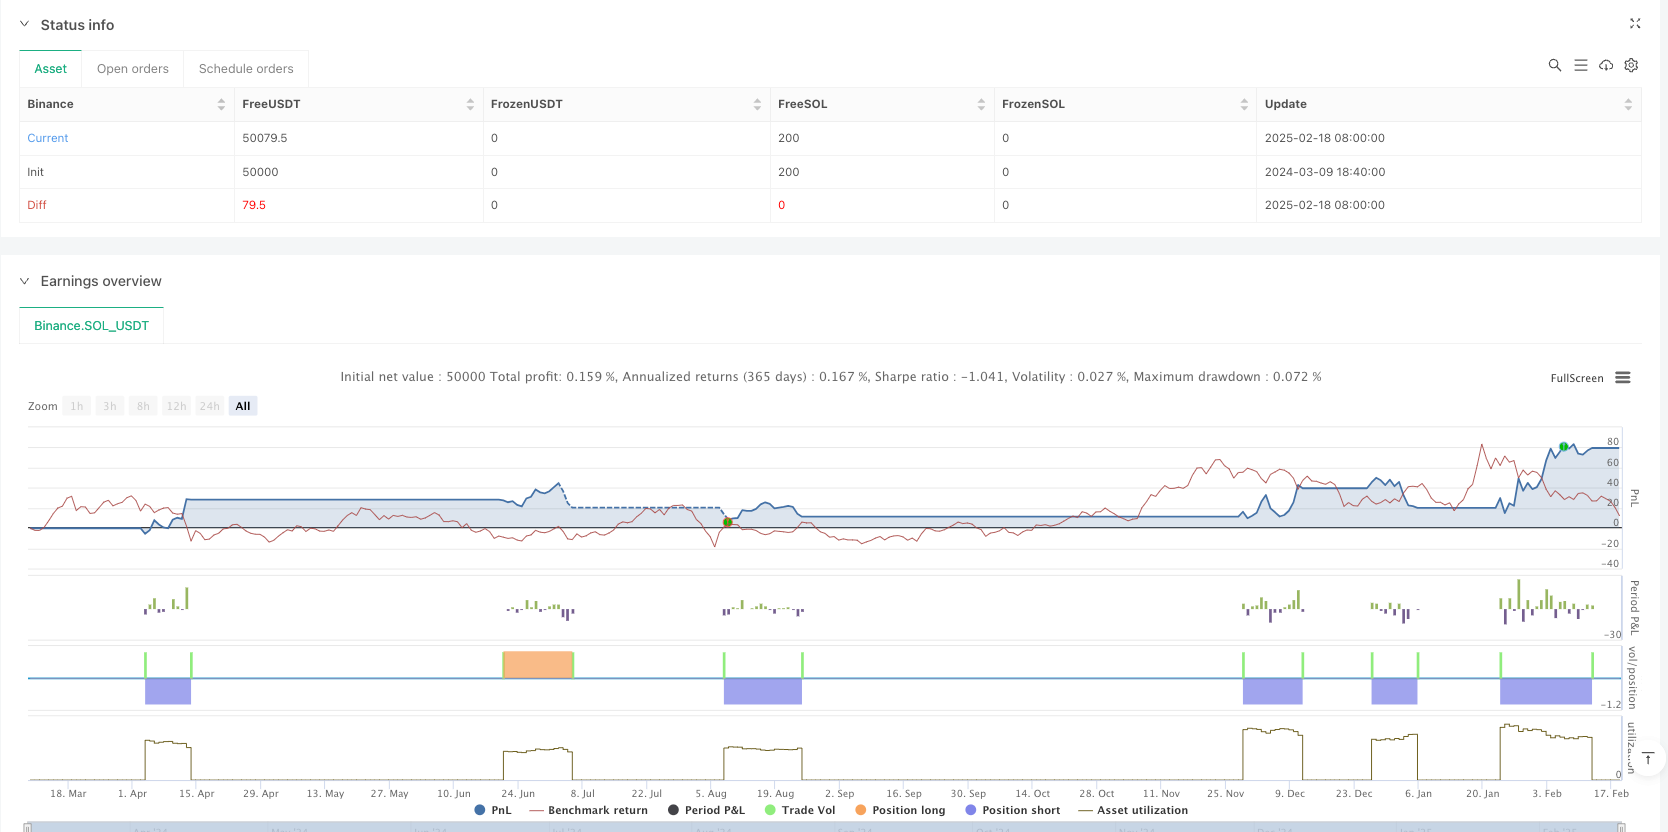
[trans]
概述
该策略基于蜡烛图形态分析市场情绪,通过三个核心振荡器(犹豫振荡器、恐惧振荡器和贪婪振荡器)来量化市场心理。策略综合了动量和趋势指标,同时结合成交量确认,构建了一个完整的交易系统。该策略适用于希望通过市场情绪分析来识别高概率交易机会的交易者。
策略原理
策略的核心是通过分析不同的蜡烛图形态来构建三个情绪振荡器:
- 犹豫振荡器 - 通过十字星和陀螺形态来衡量市场的不确定性
- 恐惧振荡器 - 通过流星、上吊线和看跌吞没形态来跟踪空头情绪
- 贪婪振荡器 - 通过光头阳线、锤子线、看涨吞没和三白兵来检测多头情绪
这三个振荡器的平均值构成了蜡烛情绪指数(CEI)。当CEI突破不同阈值时触发多空交易信号,并通过成交量确认。
策略优势
- 系统化的情绪分析 - 通过量化蜡烛图形态将主观分析转化为客观指标
- 风险管理完善 - 包含最大持仓期限、止盈止损和冷却期等机制
- 灵活的恢复机制 - 当交易出现亏损时,策略会尝试通过突破平衡点来恢复
- 多市场适用性 - 可应用于股票、外汇和加密货币等多个市场
- 信号可靠性高 - 通过成交量确认和多重技术指标验证来提高准确率
策略风险
- 参数敏感性 - 各类阈值的设置需要充分测试和优化
- 市场环境依赖 - 在震荡市场中可能产生错误信号
- 滑点风险 - 在流动性较差的市场可能面临执行风险
- 过度交易风险 - 需要合理设置冷却期来避免频繁交易
- 系统性风险 - 在重大市场事件中可能遭受较大损失
策略优化方向
- 动态阈值 - 根据市场波动率自动调整各类阈值
- 市场状态分类 - 增加趋势和震荡市场的识别机制
- 机器学习优化 - 使用机器学习算法优化参数组合
- 风险管理增强 - 加入资金管理和仓位控制模块
- 信号过滤 - 整合更多技术指标来过滤虚假信号
总结
这是一个将技术分析与量化交易相结合的创新策略。通过系统化的情绪分析和严格的风险管理,该策略能够为交易者提供可靠的交易信号。虽然存在一定的优化空间,但策略的基本框架是稳健的,适合进一步开发和实盘应用。
||
Overview
This strategy analyzes market sentiment through candlestick patterns using three core oscillators (Indecision, Fear, and Greed) to quantify market psychology. It combines momentum and trend indicators with volume confirmation to build a complete trading system. The strategy is suitable for traders who want to identify high-probability trading opportunities through market sentiment analysis.
Strategy Principles
The core of the strategy is built on three sentiment oscillators derived from candlestick patterns:
- Indecision Oscillator - Measures market uncertainty through Doji and Spinning Top patterns
- Fear Oscillator - Tracks bearish sentiment through Shooting Star, Hanging Man, and Bearish Engulfing patterns
- Greed Oscillator - Detects bullish sentiment through Marubozu, Hammer, Bullish Engulfing, and Three White Soldiers
The average of these three oscillators forms the Candle Emotion Index (CEI). Trading signals are triggered when CEI breaks different thresholds, confirmed by volume analysis.
Strategy Advantages
- Systematic Sentiment Analysis - Transforms subjective candlestick analysis into objective indicators
- Comprehensive Risk Management - Includes maximum holding period, profit/loss limits, and cooldown periods
- Flexible Recovery Mechanism - Attempts to recover through breakeven points when trades move against position
- Multi-Market Compatibility - Applicable across stocks, forex, and cryptocurrency markets
- High Signal Reliability - Uses volume confirmation and multiple technical indicators for validation
Strategy Risks
- Parameter Sensitivity - Various thresholds require thorough testing and optimization
- Market Environment Dependency - May generate false signals in ranging markets
- Slippage Risk - Execution risks in markets with poor liquidity
- Overtrading Risk - Requires proper cooldown periods to avoid excessive trading
- Systematic Risk - May suffer significant losses during major market events
Optimization Directions
- Dynamic Thresholds - Automatically adjust thresholds based on market volatility
- Market State Classification - Add trend and range market identification mechanisms
- Machine Learning Optimization - Use machine learning algorithms to optimize parameter combinations
- Enhanced Risk Management - Add money management and position sizing modules
- Signal Filtering - Integrate more technical indicators to filter false signals
Summary
This innovative strategy combines technical analysis with quantitative trading. Through systematic sentiment analysis and strict risk management, it provides reliable trading signals for traders. While there is room for optimization, the basic framework is robust and suitable for further development and live trading implementation.[/trans]
Source (PineScript)
/*backtest
start: 2024-03-09 18:40:00
end: 2025-02-19 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Binance","currency":"SOL_USDT"}]
*/

//@version=6
strategy("Candle Emotion Index Strategy", shorttitle="CEI Strategy", overlay=true)

// User Inputs
length = input.int(14, title="Lookback Period", minval=1)
dojiThreshold = input.float(0.1, title="Doji Threshold", minval=0.01, maxval=0.5)
spinningTopThreshold = input.float(0.3, title="Spinning Top Threshold", minval=0.1, maxval=0.5)
shootingStarThreshold = input.float(0.5, title="Shooting Star Threshold", minval=0.1, maxval=1.0)
hangingManThreshold = input.float(0.5, title="Hanging Man Threshold", minval=0.1, maxval=1.0)
engulfingThreshold = input.float(0.5, title="Engulfing Threshold", minval=0.1, maxval=1.0)
marubozuThreshold = input.float(0.9, title="Marubozu Threshold", minval=0.5, maxval=1.0)
hammerThreshold = input.float(0.5, title="Hammer Threshold", minval=0.1, maxval=1.0)
threeWhiteSoldiersThreshold = input.float(0.5, title="Three White Soldiers Threshold", minval=0.1, maxval=1.0)

// Volume Multiplier Input
volumeMultiplier = input.float(1.5, title="Volume Multiplier", minval=1.0)

// Cooldown Period Input
cooldownPeriod = input.int(10, title="Cooldown Period (Candles)", minval=1)

// Maximum Holding Period Inputs
maxHoldingPeriod = input.int(20, title="Maximum Holding Period (Candles)", minval=1)
lossHoldingPeriod = input.int(10, title="Loss Exit Holding Period (Candles)", minval=1)
lossThreshold = input.float(0.02, title="Loss Threshold (as % of Entry Price)", minval=0.01, maxval=1.0)

// --- Indecision Oscillator Functions ---
isDoji(open, close, high, low, threshold) =>
    bodySize = math.abs(close - open)
    rangeSize = high - low
    bodySize / rangeSize < threshold

isSpinningTop(open, close, high, low, threshold) =>
    bodySize = math.abs(close - open)
    rangeSize = high - low
    bodySize / rangeSize < threshold and bodySize / rangeSize >= dojiThreshold

indecisionOscillator() =>
    var float dojiScore = 0.0
    var float spinningTopScore = 0.0
    for i = 1 to length
        if isDoji(open[i], close[i], high[i], low[i], dojiThreshold)
            dojiScore := dojiScore + 1.0
        if isSpinningTop(open[i], close[i], high[i], low[i], spinningTopThreshold)
            spinningTopScore := spinningTopScore + 1.0
    dojiScore := dojiScore / length
    spinningTopScore := spinningTopScore / length
    (dojiScore + spinningTopScore) / 2

// --- Fear Oscillator Functions ---
isShootingStar(open, close, high, low, threshold) =>
    bodySize = math.abs(close - open)
    upperWick = high - math.max(open, close)
    lowerWick = math.min(open, close) - low
    upperWick / bodySize > threshold and lowerWick < bodySize

isHangingMan(open, close, high, low, threshold) =>
    bodySize = math.abs(close - open)
    upperWick = high - math.max(open, close)
    lowerWick = math.min(open, close) - low
    lowerWick / bodySize > threshold and upperWick < bodySize

isBearishEngulfing(open, close, openPrev, closePrev, threshold) =>
    bodySize = math.abs(close - open)
    prevBodySize = math.abs(closePrev - openPrev)
    close < openPrev and open > closePrev and bodySize / prevBodySize > threshold

fearOscillator() =>
    var float shootingStarScore = 0.0
    var float hangingManScore = 0.0
    var float engulfingScore = 0.0
    for i = 1 to length
        if isShootingStar(open[i], close[i], high[i], low[i], shootingStarThreshold)
            shootingStarScore := shootingStarScore + 1.0
        if isHangingMan(open[i], close[i], high[i], low[i], hangingManThreshold)
            hangingManScore := hangingManScore + 1.0
        if isBearishEngulfing(open[i], close[i], open[i+1], close[i+1], engulfingThreshold)
            engulfingScore := engulfingScore + 1.0
    shootingStarScore := shootingStarScore / length
    hangingManScore := hangingManScore / length
    engulfingScore := engulfingScore / length
    (shootingStarScore + hangingManScore + engulfingScore) / 3

// --- Greed Oscillator Functions ---
isMarubozu(open, close, high, low, threshold) =>
    bodySize = math.abs(close - open)
    totalRange = high - low
    bodySize / totalRange > threshold

isHammer(open, close, high, low, threshold) =>
    bodySize = math.abs(close - open)
    lowerWick = math.min(open, close) - low
    upperWick = high - math.max(open, close)
    lowerWick / bodySize > threshold and upperWick < bodySize

isBullishEngulfing(open, close, openPrev, closePrev, threshold) =>
    bodySize = math.abs(close - open)
    prevBodySize = math.abs(closePrev - openPrev)
    close > openPrev and open < closePrev and bodySize / prevBodySize > threshold

isThreeWhiteSoldiers(open, close, openPrev, closePrev, openPrev2, closePrev2, threshold) =>
    close > open and closePrev > openPrev and closePrev2 > openPrev2 and close > closePrev and closePrev > closePrev2

greedOscillator() =>
    var float marubozuScore = 0.0
    var float hammerScore = 0.0
    var float engulfingScore = 0.0
    var float soldiersScore = 0.0
    for i = 1 to length
        if isMarubozu(open[i], close[i], high[i], low[i], marubozuThreshold)
            marubozuScore := marubozuScore + 1.0
        if isHammer(open[i], close[i], high[i], low[i], hammerThreshold)
            hammerScore := hammerScore + 1.0
        if isBullishEngulfing(open[i], close[i], open[i+1], close[i+1], engulfingThreshold)
            engulfingScore := engulfingScore + 1.0
        if isThreeWhiteSoldiers(open[i], close[i], open[i+1], close[i+1], open[i+2], close[i+2], threeWhiteSoldiersThreshold)
            soldiersScore := soldiersScore + 1.0
    marubozuScore := marubozuScore / length
    hammerScore := hammerScore / length
    engulfingScore := engulfingScore / length
    soldiersScore := soldiersScore / length
    (marubozuScore + hammerScore + engulfingScore + soldiersScore) / 4

// --- Final Calculations ---
indecision = indecisionOscillator()
fear = fearOscillator()
greed = greedOscillator()

// Calculate the average of the three oscillators
averageOscillator = (indecision + fear + greed) / 3

// --- Combined Strategy Logic ---
var float entryPriceLong = na
var float entryPriceShort = na
var int holdingPeriodLong = 0
var int holdingPeriodShort = 0
var int cooldownCounter = 0

// Buy Signal Logic for Long and Short
longBuySignal = ta.crossover(averageOscillator, 0.1)
shortBuySignal = ta.crossover(averageOscillator, 0.2)

// Calculate average volume over the lookback period
avgVolume = ta.sma(volume, length)

// Take Profit Conditions
longTakeProfitCondition = close > open and volume > avgVolume * volumeMultiplier
shortTakeProfitCondition = close < open and volume > avgVolume * volumeMultiplier

// Buy Logic for Long Positions
if longBuySignal and strategy.position_size == 0 and cooldownCounter <= 0
    entryPriceLong := close
    strategy.entry("Long Entry", strategy.long)
    cooldownCounter := cooldownPeriod
    holdingPeriodLong := 0

// Increment holding period if in a long position
if strategy.position_size > 0
    holdingPeriodLong := holdingPeriodLong + 1

// Sell Logic for Long Positions
if longTakeProfitCondition and strategy.position_size > 0 and close > entryPriceLong
    strategy.close_all()
    cooldownCounter := cooldownPeriod

if holdingPeriodLong >= maxHoldingPeriod and strategy.position_size > 0 and close >= entryPriceLong
    strategy.close_all()
    cooldownCounter := cooldownPeriod

if holdingPeriodLong >= lossHoldingPeriod and strategy.position_size > 0 and close < entryPriceLong * (1 - lossThreshold)
    strategy.close_all()
    cooldownCounter := cooldownPeriod

// Short Logic for Short Positions
if shortBuySignal and strategy.position_size == 0 and cooldownCounter <= 0
    entryPriceShort := close
    strategy.entry("Short Entry", strategy.short)
    cooldownCounter := cooldownPeriod
    holdingPeriodShort := 0

// Increment holding period if in a short position
if strategy.position_size < 0
    holdingPeriodShort := holdingPeriodShort + 1

// Cover Logic for Short Positions
if shortTakeProfitCondition and strategy.position_size < 0 and close < entryPriceShort
    strategy.close_all()
    cooldownCounter := cooldownPeriod

if holdingPeriodShort >= maxHoldingPeriod and strategy.position_size < 0 and close <= entryPriceShort
    strategy.close_all()
    cooldownCounter := cooldownPeriod

if holdingPeriodShort >= lossHoldingPeriod and strategy.position_size < 0 and close > entryPriceShort * (1 + lossThreshold)
    strategy.close_all()
    cooldownCounter := cooldownPeriod

// Decrement the cooldown counter each candle
if cooldownCounter > 0
    cooldownCounter := cooldownCounter - 1
Detail
https://www.fmz.com/strategy/483093
Last Modified
2025-02-21 13:23:51