
7.0 KiB
Name
基于交易量加权的双重趋势判断系统-Volume-Weighted-Dual-Trend-Detection-System
Author
ChaoZhang
Strategy Description
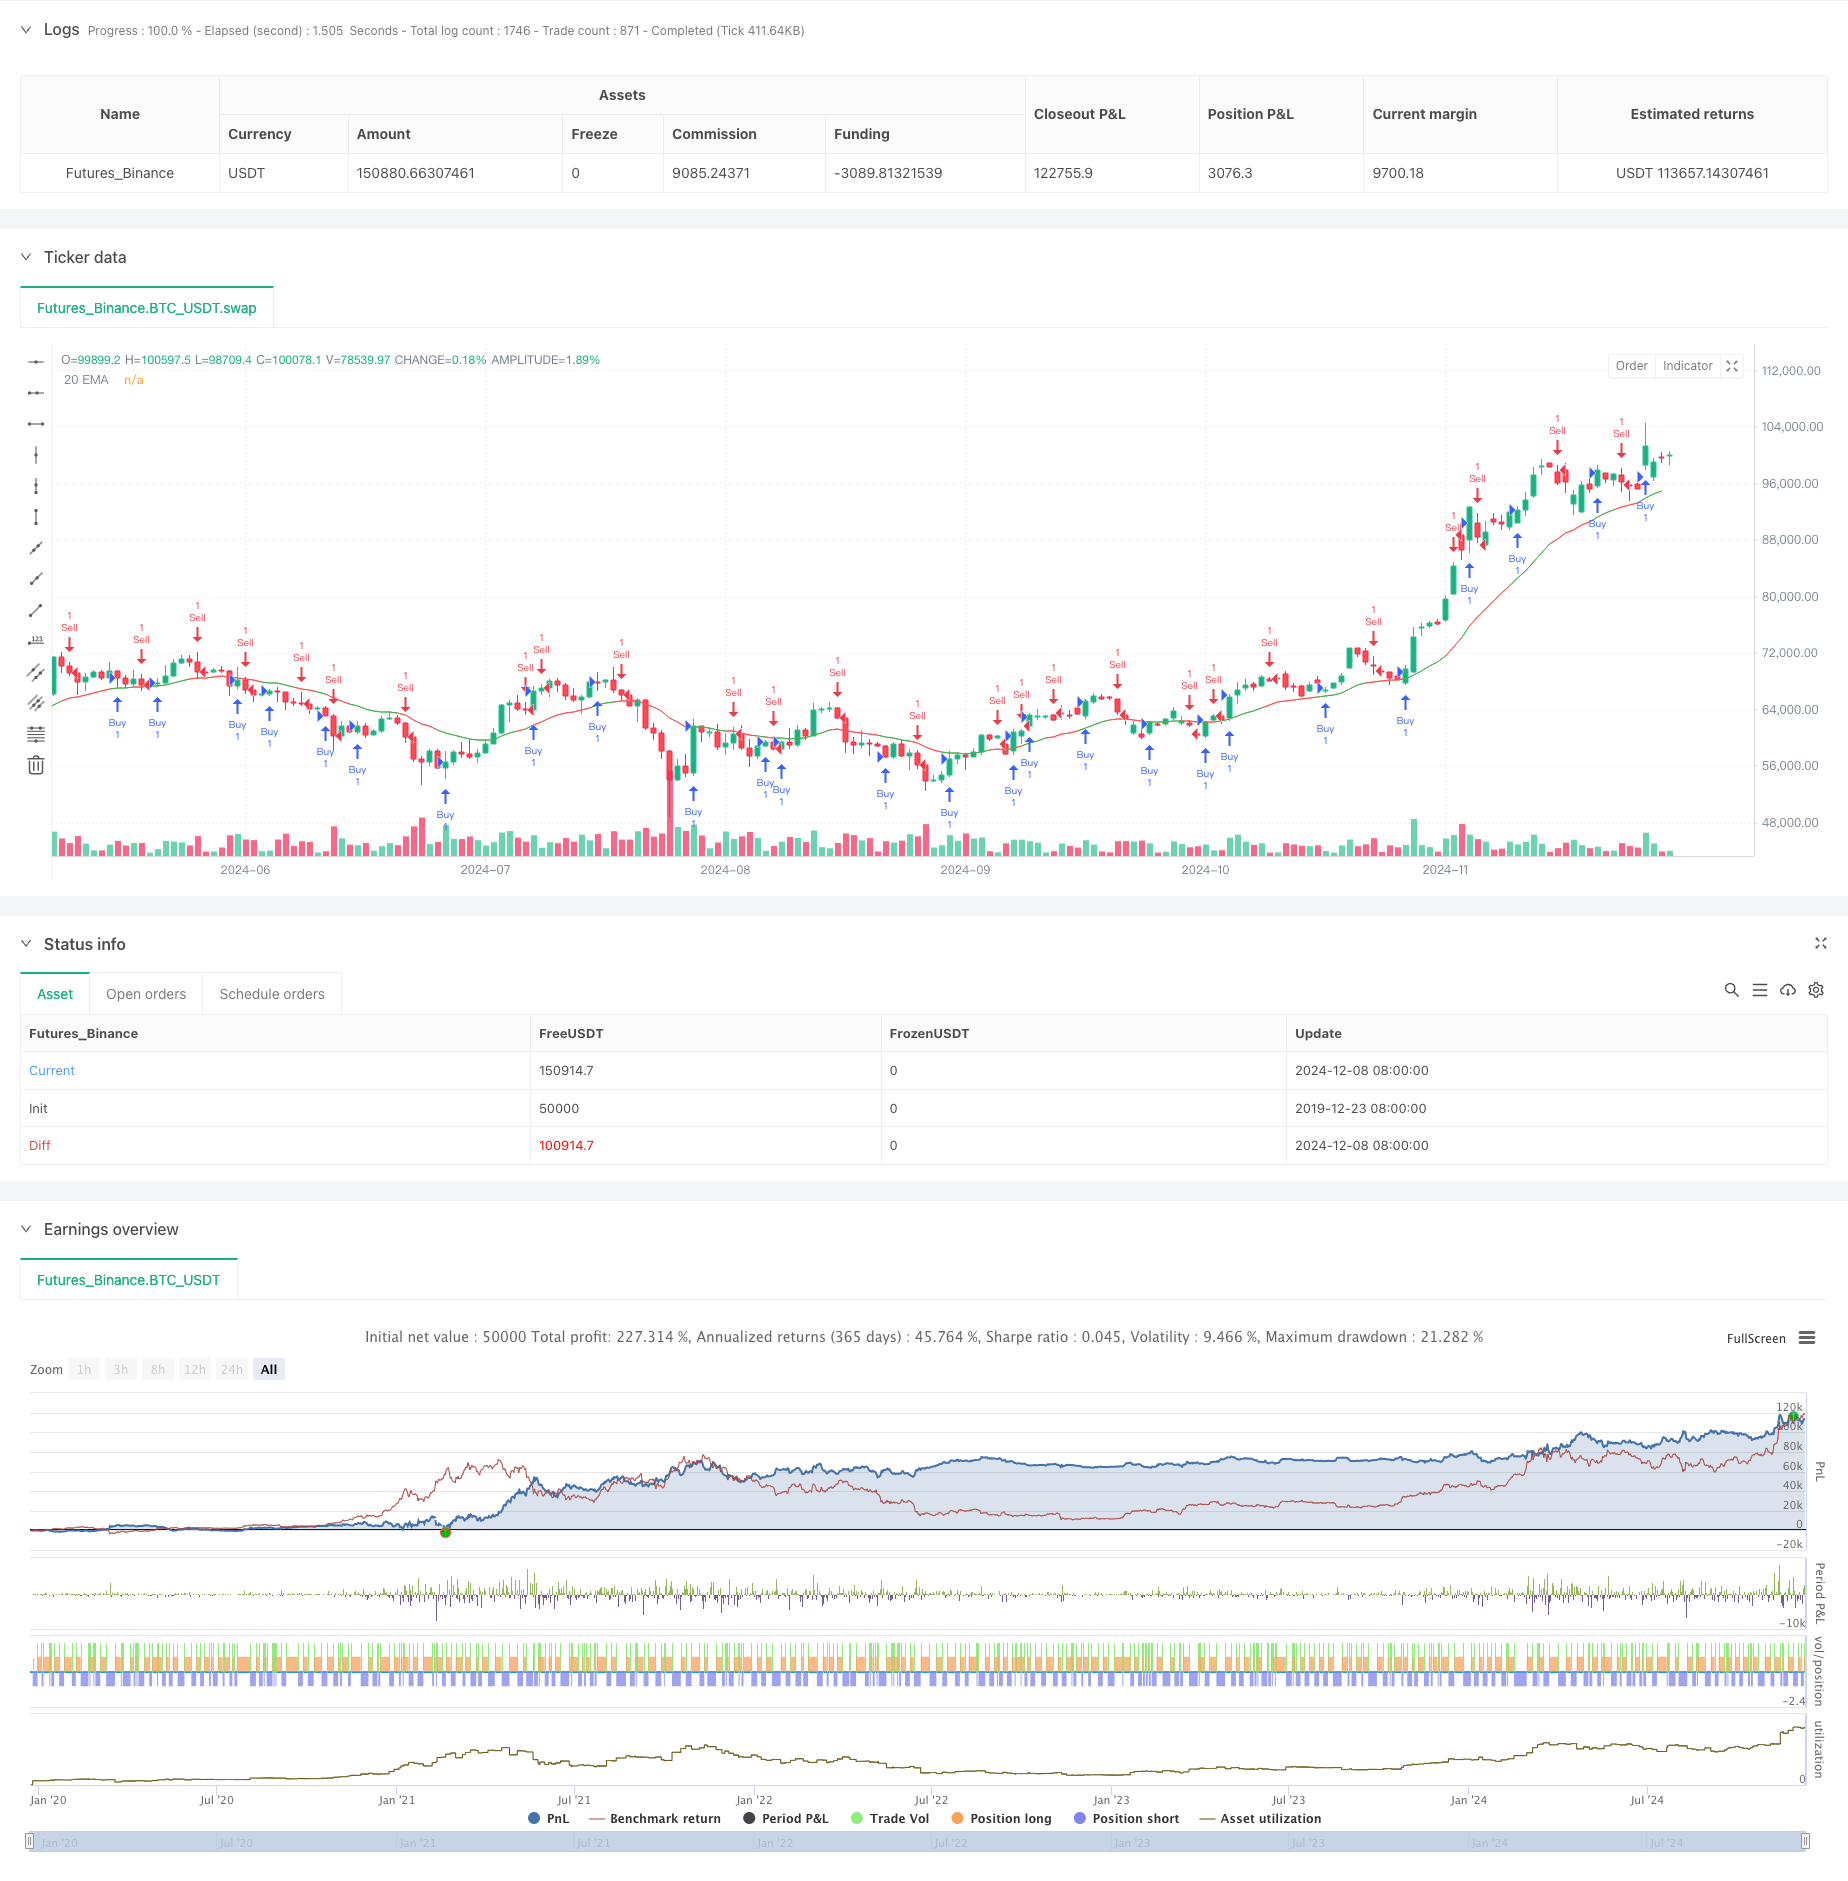
[trans]
概述
这是一个结合了交易量权重和价格波动的趋势判断系统。该系统通过计算开盘价与收盘价之间的差值(Delta值),并结合交易量进行加权,形成了一个独特的趋势指标。系统还整合了移动平均线(SMA)作为信号确认,通过比较Delta值与其SMA的关系来判断市场走势。此外,系统还引入了EMA作为辅助指标,共同构成了一个多维度的分析框架。
策略原理
- Delta值计算:使用特定周期内的开盘价与收盘价差值,并以该周期的交易量进行加权
- 信号生成机制:
- 当Delta值上穿其SMA时,系统识别为看跌信号
- 当Delta值下穿其SMA时,系统识别为看涨信号
- EMA指标配合:
- 系统使用20周期EMA作为趋势确认
- EMA颜色随Delta值与其SMA的位置关系变化
- 交易量过滤:设置交易量阈值,确保在充足的流动性条件下进行交易
策略优势
- 多维度分析:结合价格、交易量和均线系统,提供更全面的市场视角
- 信号可靠性:通过交易量加权,降低了价格波动的随机性影响
- 适应性强:可在4小时和日线等多个时间周期上运行
- 参数灵活:提供多个可调整参数,便于根据不同市场特征进行优化
- 风险控制:内置交易量过滤机制,有效规避低流动性环境
策略风险
- 趋势反转风险:在剧烈波动市场中可能产生错误信号
- 参数敏感性:不同参数组合可能导致策略表现差异较大
- 时滞风险:均线系统固有的滞后性可能导致入场时机延迟
- 市场环境依赖:在横盘整理市场中可能产生频繁交易信号
策略优化方向
- 引入动态参数:
- 根据市场波动率自动调整Delta计算周期
- 基于交易量变化动态调整交易量阈值
- 增强信号过滤:
- 添加趋势强度确认指标
- 整合价格形态识别系统
- 完善风险管理:
- 建立动态止损机制
- 引入仓位管理系统
总结
这是一个将价格动量、交易量和趋势指标有机结合的系统化策略。通过多维度分析和严格的交易条件筛选,该策略在保持较高可靠性的同时,也具备了良好的适应性和可扩展性。策略的核心优势在于其对市场趋势的立体化判断,而其最大的发展潜力在于参数的动态优化和风险管理系统的完善。 ||
Overview
This is a trend detection system that combines trading volume weighting and price movement. The system calculates the difference between opening and closing prices (Delta value), weighted by trading volume, to form a unique trend indicator. The system also integrates a Simple Moving Average (SMA) for signal confirmation, determining market trends by comparing the Delta value with its SMA. Additionally, the system incorporates EMA as an auxiliary indicator, forming a multi-dimensional analytical framework.
Strategy Principles
- Delta Value Calculation: Uses the difference between opening and closing prices within a specific period, weighted by trading volume
- Signal Generation Mechanism:
- When Delta crosses above its SMA, the system identifies a bearish signal
- When Delta crosses below its SMA, the system identifies a bullish signal
- EMA Integration:
- System uses 20-period EMA for trend confirmation
- EMA color changes based on Delta value's position relative to its SMA
- Volume Filter: Sets volume threshold to ensure trading occurs under sufficient liquidity conditions
Strategy Advantages
- Multi-dimensional Analysis: Combines price, volume, and moving average systems for a more comprehensive market perspective
- Signal Reliability: Reduces random price fluctuation effects through volume weighting
- Strong Adaptability: Operates effectively across multiple timeframes, including 4-hour and daily
- Parameter Flexibility: Offers multiple adjustable parameters for optimization across different market characteristics
- Risk Control: Built-in volume filtering mechanism effectively avoids low liquidity environments
Strategy Risks
- Trend Reversal Risk: May generate false signals in volatile markets
- Parameter Sensitivity: Different parameter combinations may lead to significant strategy performance variations
- Time Lag Risk: Inherent lag in moving average systems may delay entry timing
- Market Environment Dependency: May generate frequent trading signals in sideways markets
Strategy Optimization Directions
- Introduce Dynamic Parameters:
- Automatically adjust Delta calculation period based on market volatility
- Dynamically adjust volume threshold based on volume changes
- Enhance Signal Filtering:
- Add trend strength confirmation indicators
- Integrate price pattern recognition systems
- Improve Risk Management:
- Establish dynamic stop-loss mechanism
- Introduce position management system
Summary
This is a systematic strategy that organically combines price momentum, trading volume, and trend indicators. Through multi-dimensional analysis and strict trading condition screening, the strategy maintains high reliability while demonstrating good adaptability and scalability. The core advantage lies in its three-dimensional judgment of market trends, while its greatest development potential lies in dynamic parameter optimization and risk management system improvement.[/trans]
Source (PineScript)
/*backtest
start: 2019-12-23 08:00:00
end: 2024-12-09 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Volume-Weighted Delta Strategy", overlay=true)

// Input-parametrit
length_delta = input.int(5, minval=1, title="Delta Length")
length_ma = input.int(5, minval=1, title="MA Length")
length_sma = input.int(5, minval=1, title="MA Length")
volume_threshold = input.float(100000, title="Volume Threshold")

// Funktio delta-arvojen laskemiseksi ja volyymin mukaan painottamiseksi
calculate_volume_weighted_delta(delta_length) =>
    delta_sum = 0.0
    for i = 0 to delta_length - 1
        delta_sum := delta_sum + ((close[i] - open[i]) * volume[i])
    delta_sum


// Laskenta
delta_value = calculate_volume_weighted_delta(length_delta)
ma_value = ta.sma(delta_value, length_sma)


ema20 = ta.ema(close, 20)
// EMA:n värin määrittely
ema_color = delta_value  > ma_value ? color.green : color.red

positive = ta.crossover(delta_value, ma_value)
negative = ta.crossunder(delta_value, ma_value)

// Piirretään graafit

plot(ema20, color=ema_color, title="20 EMA")


BullishCond = ta.crossover(ma_value, delta_value)
BearishCond = ta.crossunder(ma_value, delta_value)


if (BullishCond)
    strategy.entry("Sell", strategy.short)


if (BearishCond)
    strategy.entry("Buy", strategy.long)
Detail
https://www.fmz.com/strategy/474711
Last Modified
2024-12-11 17:41:23