
11 KiB
Name
回弹趋势双均线交易系统结合ATR动态止损优化策略-Dual-EMA-Pullback-Trading-System-with-ATR-Based-Dynamic-Stop-Loss-Optimization
Author
ChaoZhang
Strategy Description
[trans]
概述
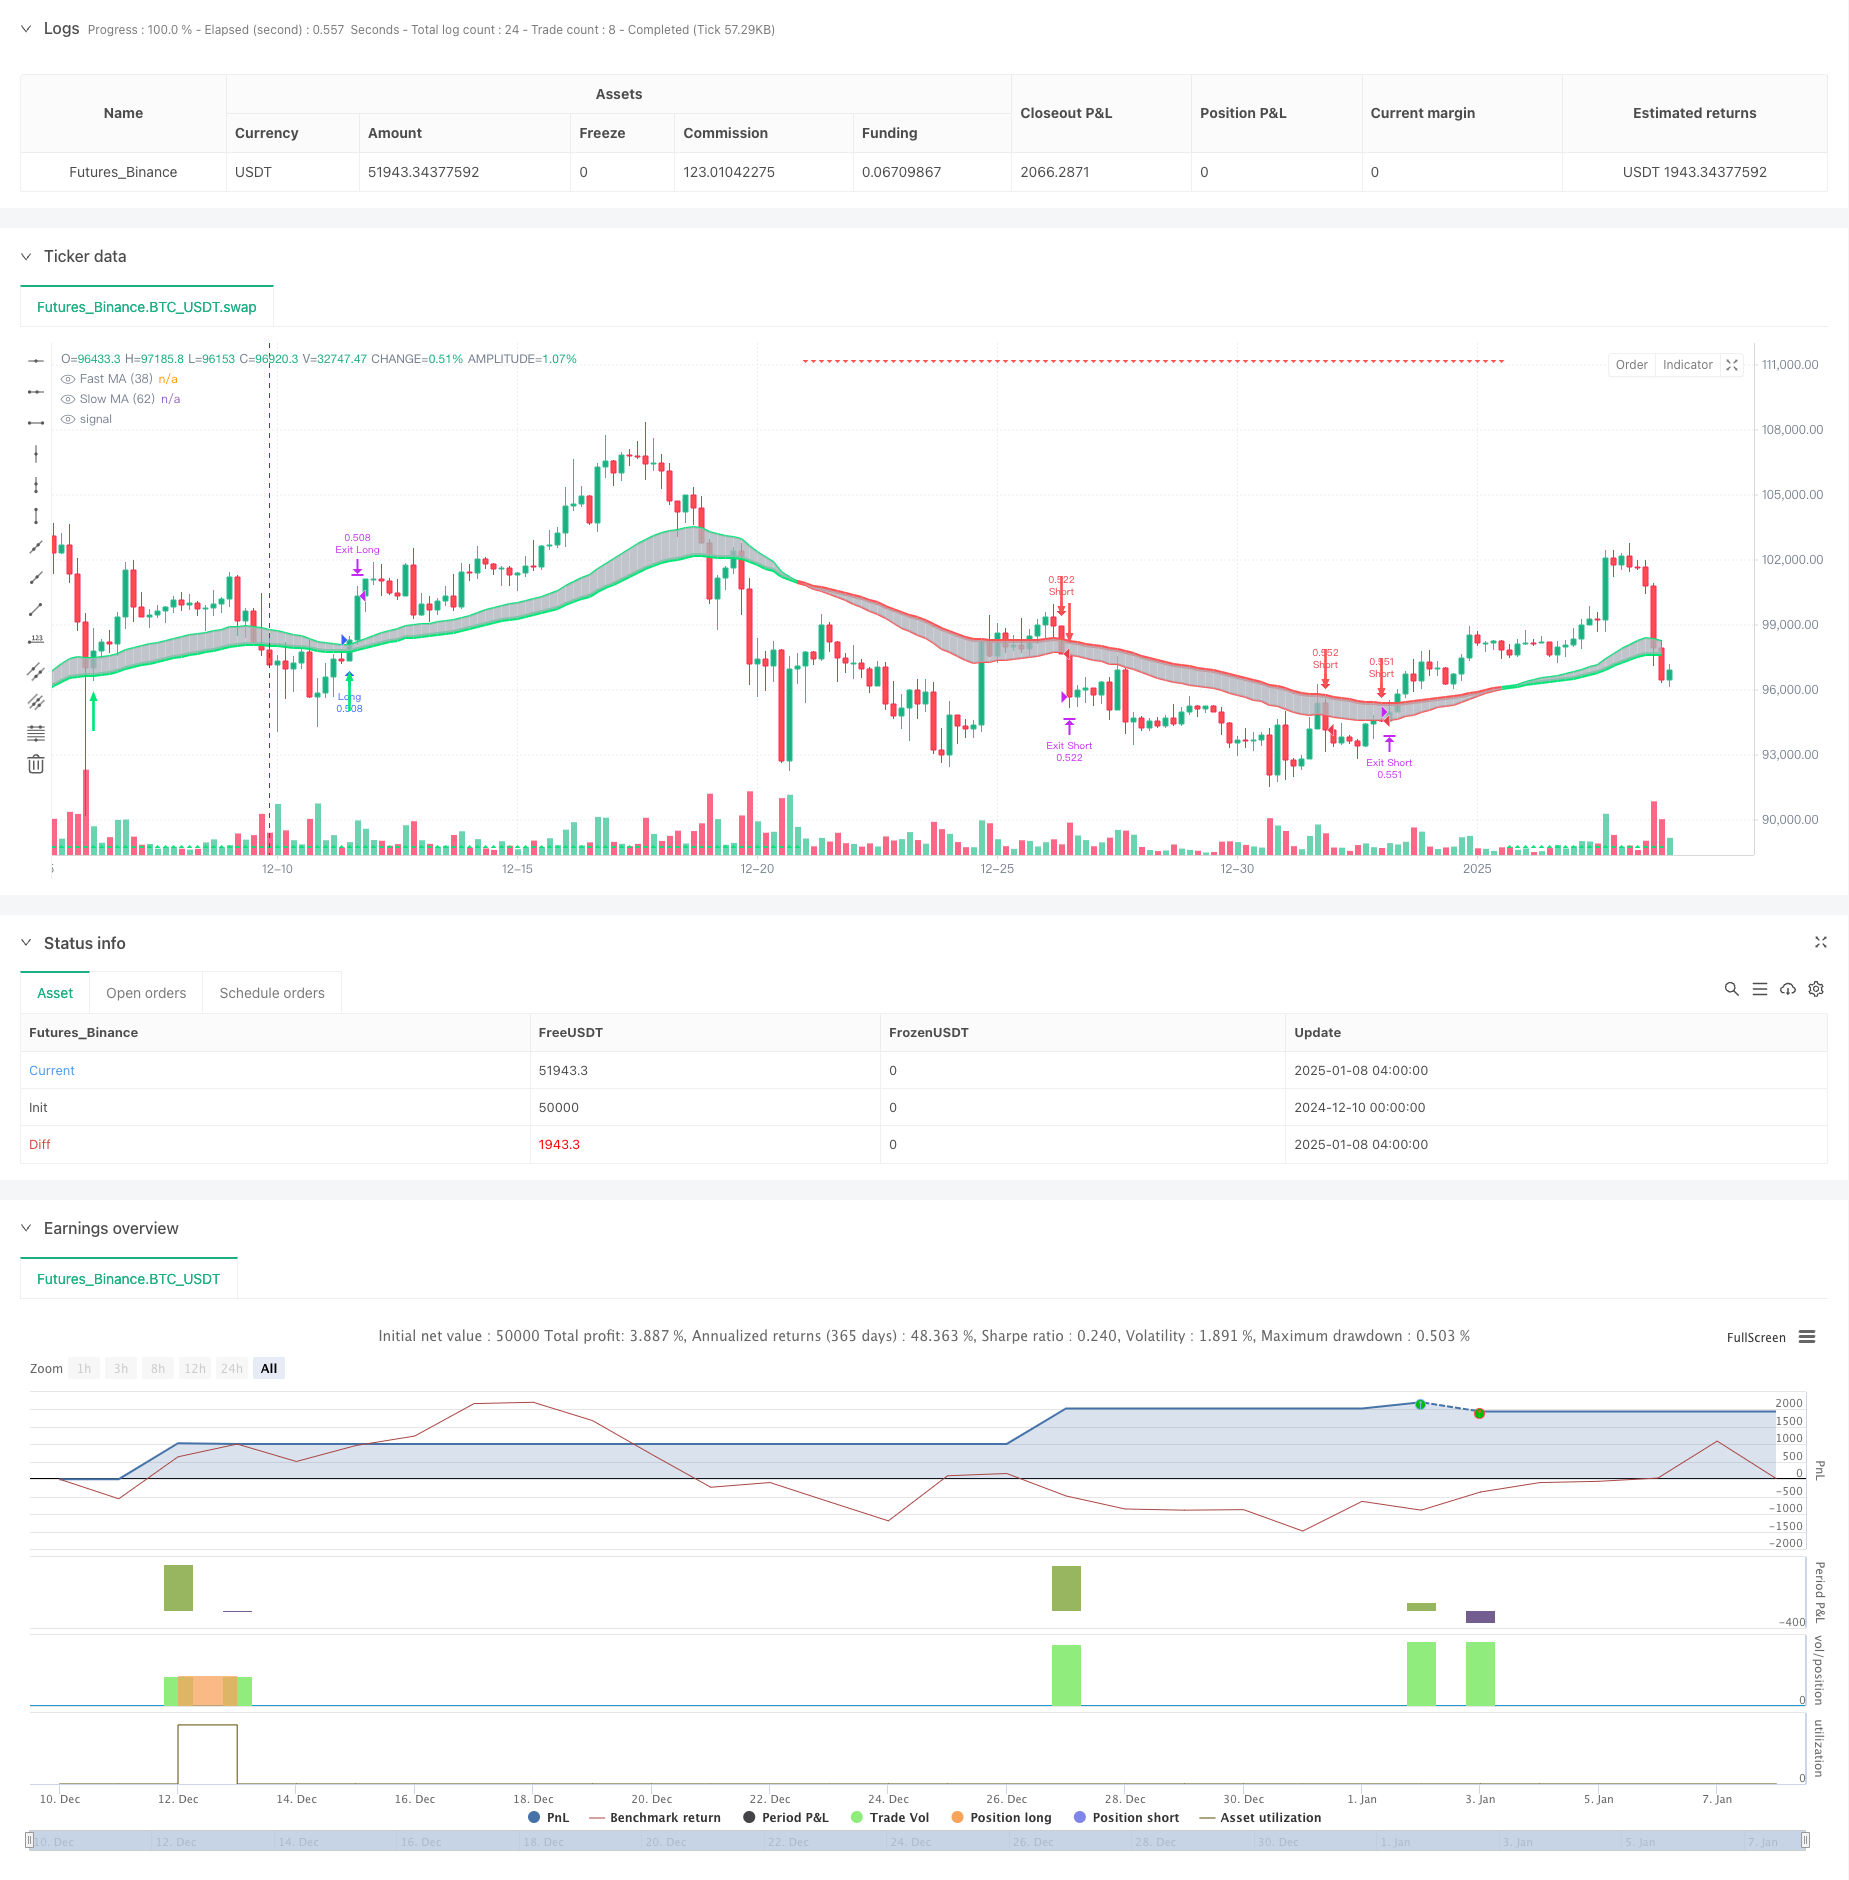
该策略是一个基于双均线系统和ATR动态止损的趋势跟踪交易系统。它使用38周期和62周期的指数移动平均线(EMA)来识别市场趋势,通过价格与快速EMA的交叉来确定入场信号,并结合ATR指标进行动态止损管理。策略同时提供了激进和保守两种交易模式,以适应不同风险偏好的交易者。
策略原理
策略的核心逻辑基于以下几个关键要素:
- 趋势判定: 通过38周期和62周期EMA的位置关系判断当前市场趋势。当快速EMA在慢速EMA之上时为上升趋势,反之为下降趋势。
- 入场信号: 在上升趋势中,当价格从下方突破快速EMA时产生做多信号;在下降趋势中,当价格从上方跌破快速EMA时产生做空信号。
- 风险管理: 采用基于ATR的动态止损系统,止损位随着价格的有利移动而相应调整,既保护已有利润又不会过早离场。同时设置了固定百分比的止损和获利目标。
策略优势
- 趋势跟踪性能优越: 通过双均线系统可以有效捕捉中长期趋势,避免在震荡市场中频繁交易。
- 风险控制完善: 结合固定止损和动态止损,既能限制最大风险,又能保护盈利。
- 适应性强: 提供激进和保守两种交易模式,可根据市场环境和个人风险偏好灵活调整。
- 视觉反馈清晰: 通过不同颜色的K线和箭头标记,直观显示市场状态和交易信号。
策略风险
- 趋势转折风险: 在趋势转折点可能会出现连续止损。建议在趋势明确时才进行交易。
- 滑点风险: 在市场波动剧烈时,实际成交价格可能与信号价格有较大偏差。应适当放宽止损范围。
- 参数敏感性: 均线周期和ATR倍数的选择会显著影响策略表现。需要针对不同市场环境进行优化。
策略优化方向
- 增加趋势强度过滤: 可引入ADX等趋势强度指标,仅在趋势明确时入场。
- 优化止损机制: 可根据波动率动态调整ATR倍数,使止损更具适应性。
- 加入成交量确认: 在入场信号出现时,结合成交量分析提高信号可靠性。
- 市场环境分类: 根据不同的市场环境(趋势/震荡)动态调整策略参数。
总结
该策略通过结合经典的双均线系统和现代的动态止损技术,构建了一个完整的趋势跟踪交易系统。策略的优势在于风险控制完善、适应性强,但仍需要交易者根据具体市场环境进行参数优化和风险管理。通过建议的优化方向,策略的稳定性和盈利能力有望得到进一步提升。
||
Overview
This strategy is a trend-following trading system based on dual EMA and ATR dynamic stop-loss. It uses 38-period and 62-period Exponential Moving Averages (EMA) to identify market trends, determines entry signals through price crossovers with the fast EMA, and incorporates ATR indicator for dynamic stop-loss management. The strategy offers both aggressive and conservative trading modes to accommodate traders with different risk preferences.
Strategy Principles
The core logic is based on the following key elements:
- Trend Determination: Market trend is identified through the relative position of 38-period and 62-period EMAs. An uptrend is confirmed when the fast EMA is above the slow EMA, and vice versa.
- Entry Signals: Long signals are generated when price breaks above the fast EMA during uptrends; short signals occur when price breaks below the fast EMA during downtrends.
- Risk Management: Employs an ATR-based dynamic stop-loss system that adjusts the stop level as price moves favorably, protecting profits while avoiding premature exits. Fixed percentage stop-loss and profit targets are also implemented.
Strategy Advantages
- Superior Trend Following: The dual EMA system effectively captures medium to long-term trends while avoiding frequent trades in ranging markets.
- Comprehensive Risk Control: Combines fixed and dynamic stops to limit maximum risk while protecting profits.
- High Adaptability: Offers both aggressive and conservative trading modes, adaptable to market conditions and personal risk preferences.
- Clear Visual Feedback: Market conditions and trading signals are intuitively displayed through colored bars and arrows.
Strategy Risks
- Trend Reversal Risk: May experience consecutive stops at trend reversal points. Trading should be limited to periods of clear trends.
- Slippage Risk: Actual execution prices may significantly deviate from signal prices during high volatility. Stop-loss ranges should be appropriately widened.
- Parameter Sensitivity: Strategy performance is significantly affected by EMA periods and ATR multiplier selection. Optimization for different market conditions is necessary.
Strategy Optimization Directions
- Add Trend Strength Filter: Incorporate trend strength indicators like ADX to enter only during clear trends.
- Optimize Stop-Loss Mechanism: Dynamically adjust ATR multiplier based on volatility for more adaptive stops.
- Include Volume Confirmation: Enhance signal reliability by incorporating volume analysis at entry points.
- Market Environment Classification: Dynamically adjust strategy parameters based on different market conditions (trending/ranging).
Summary
This strategy builds a complete trend-following trading system by combining classic dual EMA system with modern dynamic stop-loss techniques. Its strengths lie in comprehensive risk control and high adaptability, though traders still need to optimize parameters and manage risks according to specific market conditions. Through the suggested optimization directions, the strategy's stability and profitability can be further enhanced. [/trans]
Source (PineScript)
/*backtest
start: 2024-12-10 00:00:00
end: 2025-01-08 08:00:00
period: 4h
basePeriod: 4h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © aalapsharma

//@version=5
strategy(title="CM_SlingShotSystem - Strategy", shorttitle="SlingShotSys_Enhanced_v5", overlay=true, initial_capital=100000, default_qty_type=strategy.percent_of_equity, default_qty_value=100, pyramiding=1)

// Inputs
sae = input.bool(true, "Show Aggressive Entry Bars? (Highlight only)")
sce = input.bool(true, "Show Conservative Entry Bars? (Highlight only)")
st = input.bool(true, "Show Trend Arrows (Top/Bottom)?")
def = input.bool(false, "(Unused) Only Choose 1 - Either Conservative Entry Arrows or 'B'-'S' Letters")
pa = input.bool(true, "Show Conservative Entry Arrows?")
sl = input.bool(false, "Show 'B'-'S' Letters?")
useStopLoss = input.bool(true, "Use Stop-Loss?")
stopLossPerc = input.float(5.0, "Stop-Loss (%)", step=0.1)
useTakeProfit = input.bool(true, "Use Take-Profit?")
takeProfitPerc = input.float(20.0, "Take-Profit (%)", step=0.1)
useTrailingStop = input.bool(false, "Use ATR Trailing Stop?")
atrLength = input.int(14, "ATR Length", minval=1)
atrMult = input.float(2.0, "ATR Multiple for Trailing Stop", step=0.1)

// Calculations
emaSlow = ta.ema(close, 62)
emaFast = ta.ema(close, 38)
upTrend = emaFast >= emaSlow
downTrend = emaFast < emaSlow
pullbackUpT() => emaFast > emaSlow and close < emaFast
pullbackDnT() => emaFast < emaSlow and close > emaFast
entryUpT() => emaFast > emaSlow and close[1] < emaFast and close > emaFast
entryDnT() => emaFast < emaSlow and close[1] > emaFast and close < emaFast
entryUpTrend = entryUpT() ? 1 : 0
entryDnTrend = entryDnT() ? 1 : 0
atrValue = ta.atr(atrLength)

// Trailing Stop Logic (Improved)
var float trailStopLong = na
var float trailStopShort = na

if (strategy.position_size > 0)
    trailStopLong := math.max(close - (atrValue * atrMult), nz(trailStopLong[1], close))
    trailStopLong := strategy.position_avg_price > trailStopLong ? strategy.position_avg_price : trailStopLong
else
    trailStopLong := na

if (strategy.position_size < 0)
    trailStopShort := math.min(close + (atrValue * atrMult), nz(trailStopShort[1], close))
    trailStopShort := strategy.position_avg_price < trailStopShort ? strategy.position_avg_price : trailStopShort
else
    trailStopShort := na

// Plotting
col = emaFast > emaSlow ? color.lime : emaFast < emaSlow ? color.red : color.yellow
p1 = plot(emaSlow, "Slow MA (62)", linewidth=4, color=col)
p2 = plot(emaFast, "Fast MA (38)", linewidth=2, color=col)
fill(p1, p2, color=color.silver, transp=50)
barcolor((sae and pullbackUpT()) ? color.yellow : (sae and pullbackDnT()) ? color.yellow : na)
barcolor((sce and entryUpT()) ? color.aqua : (sce and entryDnT()) ? color.aqua : na)
plotshape(st and upTrend, title="Trend UP", style=shape.triangleup, location=location.bottom, color=color.lime)
plotshape(st and downTrend, title="Trend DOWN", style=shape.triangledown, location=location.top, color=color.red)
plotarrow((pa and entryUpTrend == 1) ? 1 : na, title="Up Entry Arrow", colorup=color.lime, maxheight=30, minheight=30)
plotarrow((pa and entryDnTrend == 1) ? -1 : na, title="Down Entry Arrow", colordown=color.red, maxheight=30, minheight=30)
plotchar(sl and entryUpTrend ? (low - ta.tr) : na, title="Buy Entry (Letter)", char='B', location=location.absolute, color=color.lime)
plotchar(sl and entryDnTrend ? (high + ta.tr) : na, title="Short Entry (Letter)", char='S', location=location.absolute, color=color.red)
plot(useTrailingStop and strategy.position_size > 0 ? trailStopLong : na, "Trailing Stop Long", color=color.green, style=plot.style_linebr)
plot(useTrailingStop and strategy.position_size < 0 ? trailStopShort : na, "Trailing Stop Short", color=color.red, style=plot.style_linebr)

// Function to calculate stop and limit prices
f_calcStops(_entryPrice, _isLong) =>
    _stopLoss = _isLong ? _entryPrice * (1.0 - stopLossPerc / 100.0) : _entryPrice * (1.0 + stopLossPerc / 100.0)
    _takeProfit = _isLong ? _entryPrice * (1.0 + takeProfitPerc / 100.0) : _entryPrice * (1.0 - takeProfitPerc / 100.0)
    [_stopLoss, _takeProfit]

// Entry and Exit Logic (Simplified using strategy.close)
if (entryUpT() and strategy.position_size == 0)
    strategy.entry("Long", strategy.long)

if (entryDnT() and strategy.position_size == 0)
    strategy.entry("Short", strategy.short)

// Exit conditions based on Stop-loss and Take-profit
[slPrice, tpPrice] = f_calcStops(strategy.position_avg_price, strategy.position_size > 0)

if (strategy.position_size > 0)
    strategy.exit("Exit Long", "Long", stop=slPrice, limit=tpPrice, trail_price = trailStopLong, trail_offset = atrValue * atrMult)

if (strategy.position_size < 0)
    strategy.exit("Exit Short", "Short", stop=slPrice, limit=tpPrice, trail_price = trailStopShort, trail_offset = atrValue * atrMult)

// Close opposite position on new entry signal
if (entryUpT() and strategy.position_size < 0)
    strategy.close("Short", comment="Close Short on Long Signal")

if (entryDnT() and strategy.position_size > 0)
    strategy.close("Long", comment="Close Long on Short Signal")
Detail
https://www.fmz.com/strategy/477950
Last Modified
2025-01-10 15:19:40