
7.7 KiB
Name
双cci量化策略Dual-CCI-Quantitative-Strategy
Author
ChaoZhang
Strategy Description
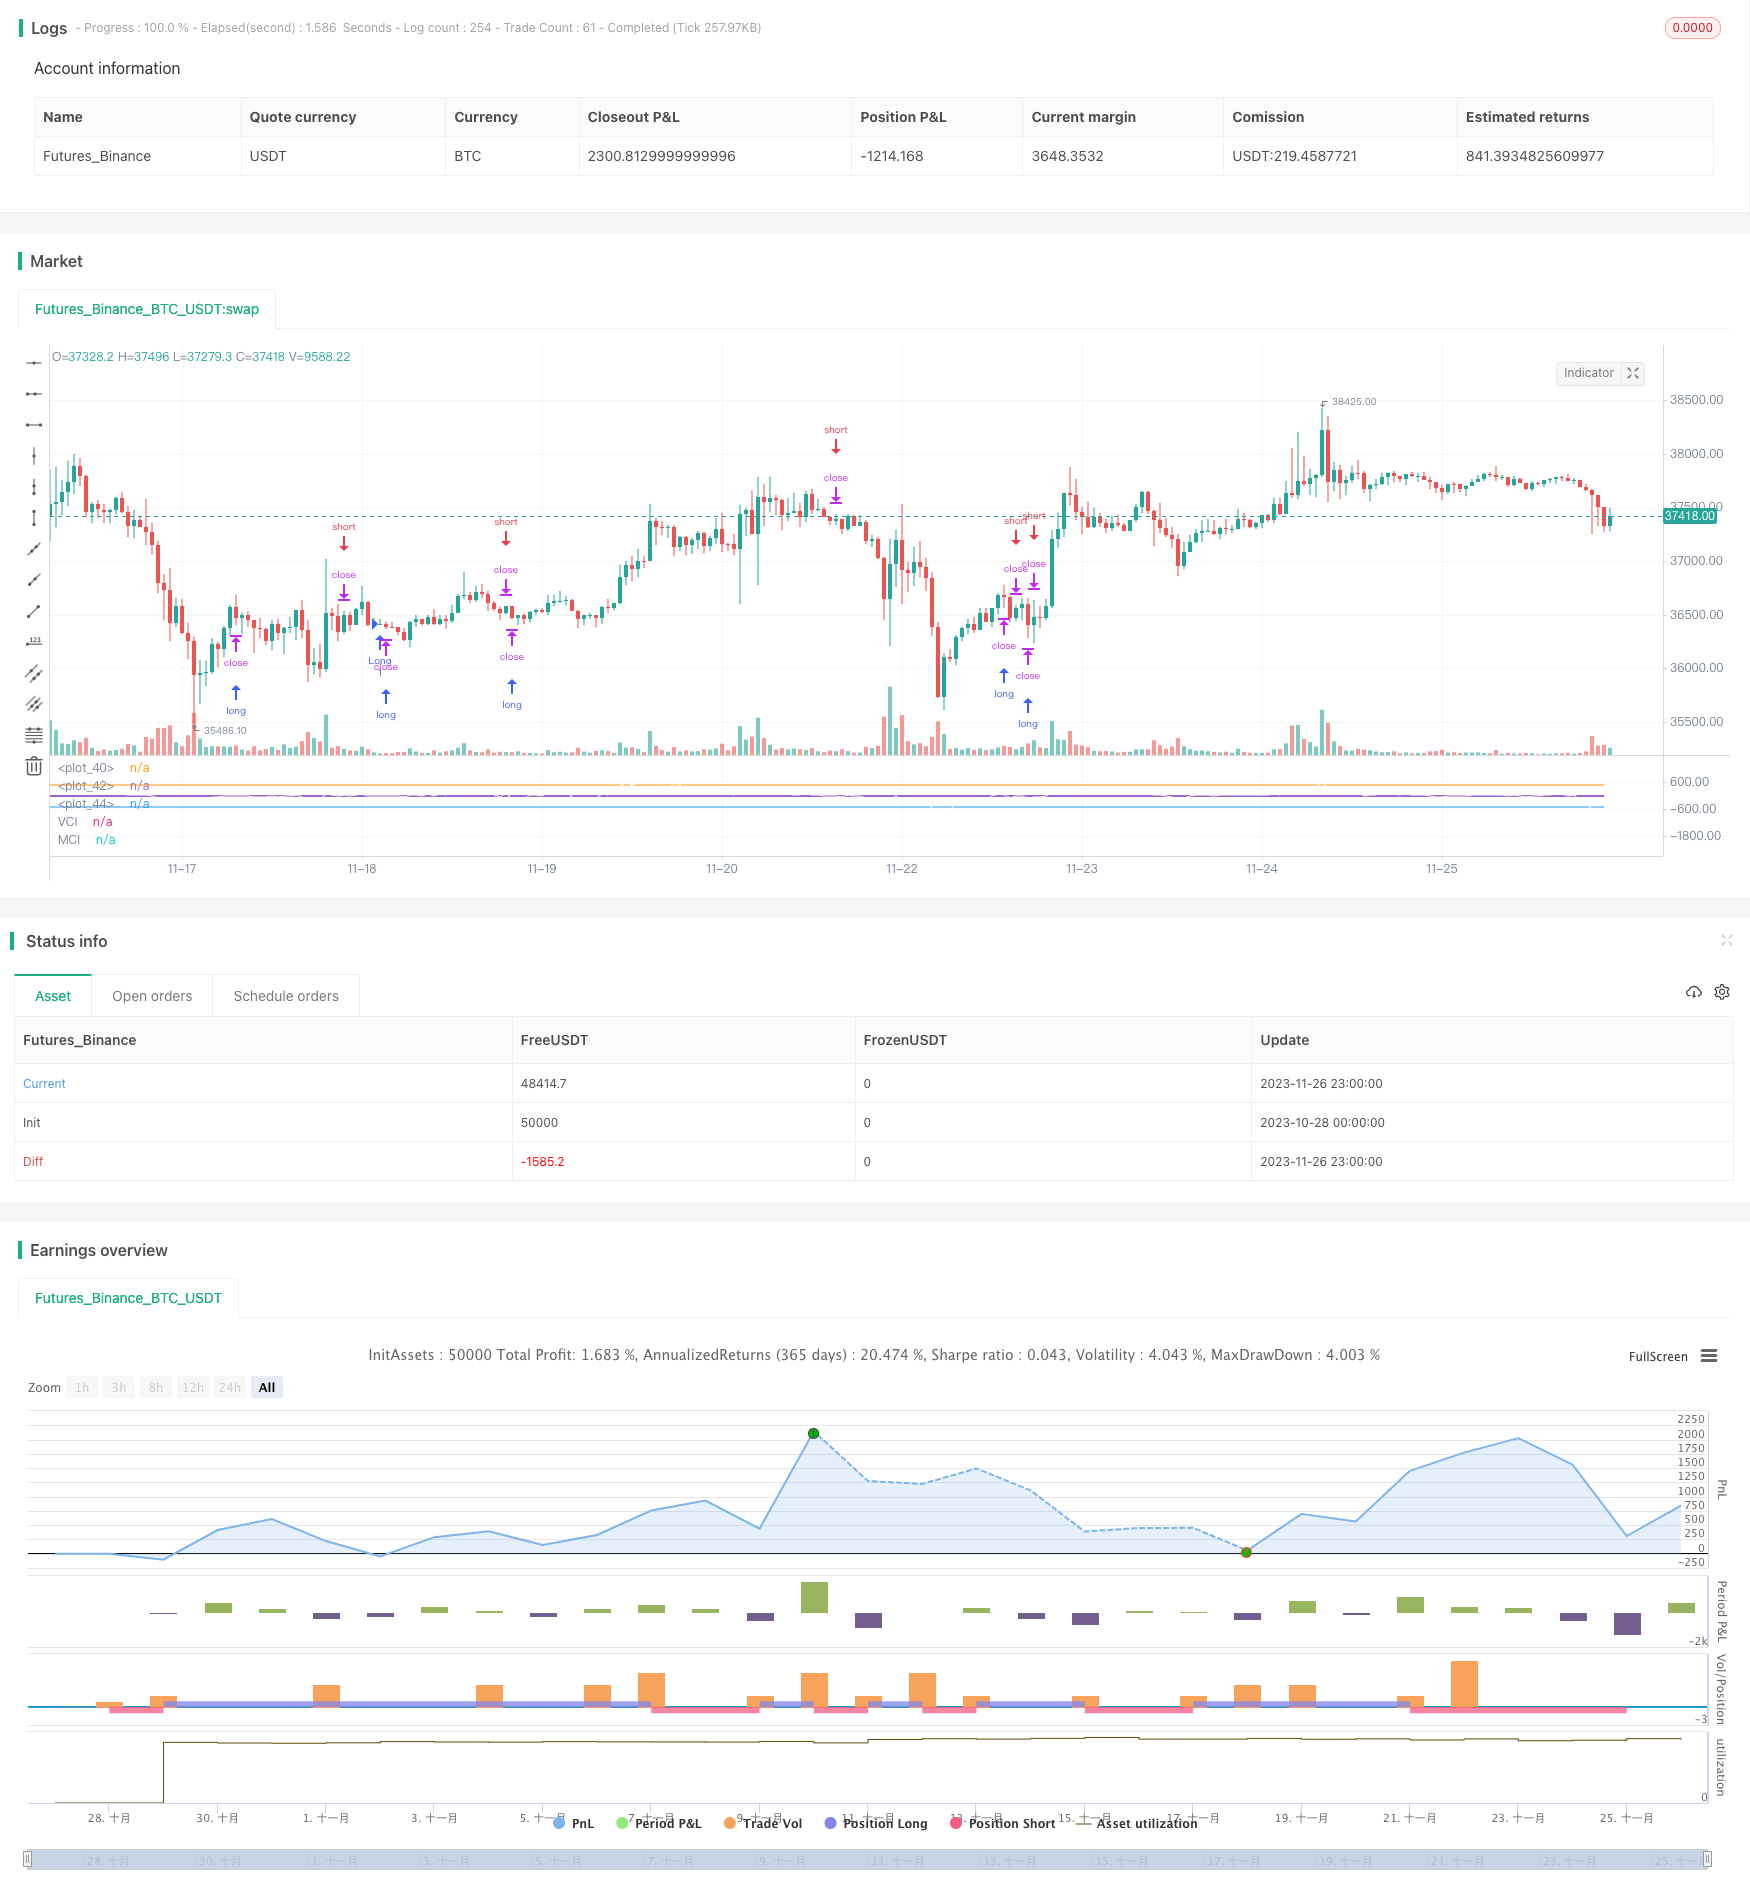 [trans]
概述
该策略通过结合经典技术指标CCI和自主研发的VCI、MCI双指数形成交易信号,属于典型的量化交易策略。其通过识别Volume和Price的变化趋势,判断当前行情主要交易方向和力度,形成交易信号。可以广泛应用于数字货币、外汇以及股票等金融工具。
策略原理
- 计算ohlc4均线,并结合cci指标判断价位;
- 计算obv指标衡量资金流向;
- 计算VCI指数,即通过obv指标的方差测量资金流量分布;
- 计算MCI指数,即通过价格的方差测量价格分布;
- VCI与MCI指数进行比较,判断市场买卖态势;
- VCI > MCI,买方意愿强;
- VCI < MCI, 卖方意愿强;
- 根据VCI和MCI的比较形成做多做空信号;
优势分析
- 该策略综合考虑了价格、交易量以及资金流向多个维度,判断市场买卖态势,信号较为准确;
- VCI和MCI通过动态标准差计算,能够适应市场的实时变化;
- 策略参数经过大量回测优化,具有较强的稳定性;
风险分析
- 价格和交易量指标计算滞后,不能提前捕捉突发事件;
- 单一策略无法完全覆盖复杂多变的市场情况;
- 需要与其他辅助指标结合使用,不能单独判断市场;
优化方向
- 结合深度学习等预测模型,提高信号判断的准确性;
- 增加止损等风险控制模块,提高策略的稳定性;
- 可尝试不同参数组合,测试在特定市场中的适用性;
总结
该策略通过双cci指数的比较形成交易信号,考虑了价格和交易量等多个因素,对市场买卖力度进行评估,是一种典型且实用的量化交易策略。但仍需与其他辅助工具配合使用,才能发挥策略最大效用。值得进一步优化提高适用场景,减少风险。
||
Overview
This strategy combines the classic technical indicator CCI and self-developed VCI and MCI dual indices to form trading signals, which is a typical quantitative trading strategy. By identifying the trend and momentum of Volume and Price changes, it determines the main direction of the current market and forms trading signals. It can be widely used for financial instruments such as digital currencies, foreign exchange and stocks.
Strategy Principle
- Calculate ohlc4 moving average and combine with cci indicator to judge price level;
- Calculate obv indicator to measure capital flow;
- Calculate VCI index, which measures the distribution of capital flow through the variance of obv indicator;
- Calculate MCI index, which measures the distribution of prices through the variance of prices;
- Compare VCI and MCI indices to judge market sentiment;
- VCI > MCI, strong buying interest;
- VCI < MCI, strong selling interest;
- Form long and short signals based on the comparison of VCI and MCI;
Advantage Analysis
- The strategy takes into account multiple dimensions such as price, trading volume and capital flow to judge market sentiment, with relatively accurate signals;
- VCI and MCI are calculated by dynamic standard deviation, which can adapt to real-time market changes;
- The strategy parameters have been optimized through extensive backtesting and have strong stability;
Risk Analysis
- The calculation of price and trading volume indicators lags and cannot capture sudden events in advance;
- A single strategy cannot fully cover complex and volatile market conditions;
- It needs to be combined with other auxiliary indicators and cannot solely judge the market;
Optimization Directions
- Incorporate predictive models such as deep learning to improve signal judgment accuracy;
- Add risk control modules such as stop loss to enhance strategy stability;
- Try different parameter combinations to test applicability in specific markets;
Conclusion
This strategy forms trading signals by comparing dual CCI indices, taking into account factors such as price and trading volume to assess market sentiment. It is a typical and practical quantitative trading strategy. But it still needs to be used with other auxiliary tools to maximize the effectiveness of the strategy. It is worthwhile to further optimize and expand applicable scenarios while reducing risks.
[/trans]
Strategy Arguments
| Argument | Default | Description |
|---|---|---|
| v_input_1 | false | Mode Discrepency |
| v_input_2 | 0.015 | Interval |
| v_input_3 | 20 | Standard (Average) Length |
| v_input_4 | 20 | Lookback length |
| v_input_5_ohlc4 | 0 | v_input_5: ohlc4 |
| v_input_6_close | 0 | srcP: close |
| v_input_7 | 9 | From Month |
| v_input_8 | 13 | From Day |
| v_input_9 | 2018 | From Year |
| v_input_10 | true | To Month |
| v_input_11 | true | To Day |
| v_input_12 | 9999 | To Year |
| v_input_13 | false | Strategy Direction |
Source (PineScript)
/*backtest
start: 2023-10-28 00:00:00
end: 2023-11-27 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("MCI and VCI - Modified CCI Formulas")
test = cci(ohlc4, 13)
test1 = cci(ohlc4, 20)

obv(src) => cum(change(src) > 0 ? volume : change(src) < 0 ? -volume : 0*volume)
mDisc = input(0, title="Mode Discrepency")
mDiv = input(0.015, title="Interval")
mean(_src, _length)=>
    _return = sum(_src, _length) / _length

median(_src, _length)=>
    _return = _src
    for _i = 0 to _length
        _return := _return == 0 ? _src : (_return + _src[_i]) / 2
    _return


len = input(20, title="Standard (Average) Length")
mmm = input(20, title="Lookback length")
srcV = obv(input(ohlc4))
srcP = input(close)
x = sma(srcV, len)
MDV2 = abs(stdev(median(x, len), mmm))
MDV3 = abs(stdev(mean(x, len), mmm))
AMDV = (MDV2+MDV3)/2
pt1v = (srcV-ema(srcV, len))/ AMDV
pt2v = 1/mDiv
VCI=pt1v*pt2v
y = ema(srcP, len)
MDP2 =  abs(stdev(median(y, len), mmm))
MDP3 = abs(stdev(mean(y, len), mmm))
AMDA = (MDP2 + MDP3)/2
pt1p = 1/mDiv
pt2p = (srcP-ema(srcP, len))/ AMDA
MCI = pt1p * pt2p
plot(VCI, color=yellow, title="VCI", style="Histogram")
plot(MCI, color=white, title="MCI")

plot(500, style=line)

plot(0, style=line, linewidth=2)

plot(-500, style=line)
long = crossover(MCI, 0) and VCI > MCI[2]
short = crossunder(MCI, 0) and VCI < MCI[2]
//Time Control
//Set date and time
FromMonth = input(defval = 9, title = "From Month", minval = 1, maxval = 12)
FromDay   = input(defval = 13, title = "From Day", minval = 1, maxval = 31)
FromYear  = input(defval = 2018, title = "From Year", minval = 2017)
ToMonth   = input(defval = 1, title = "To Month", minval = 1, maxval = 12)
ToDay     = input(defval = 1, title = "To Day", minval = 1, maxval = 31)
ToYear    = input(defval = 9999, title = "To Year", minval = 2017)

// === FUNCTION EXAMPLE ===
start     = timestamp(FromYear, FromMonth, FromDay, 00, 00)  // backtest start window
finish    = timestamp(ToYear, ToMonth, ToDay, 23, 59)        // backtest finish window
window()  => time >= start and time <= finish ? true : false // create function "within window of time"


direction = input(0, title = "Strategy Direction", minval=-1, maxval=1)
strategy.risk.allow_entry_in(direction == 0 ? strategy.direction.all : (direction < 0 ? strategy.direction.short : strategy.direction.long))
if (long)
    strategy.entry("Long", strategy.long, when=window(), limit=ohlc4, oca_name="BollingerBands",  comment="BBandLE")
else
    strategy.cancel(id="Long")

if (short)
    strategy.entry("Short", strategy.short, when=window(), limit=ohlc4, oca_name="BollingerBands", comment="BBandSE")
else
    strategy.cancel(id="Short")
Detail
https://www.fmz.com/strategy/433568
Last Modified
2023-11-28 15:47:04