
5.9 KiB
Name
双均线交叉开仓策略-Dual-Moving-Average-Crossover-Entry-Strategy
Author
ChaoZhang
Strategy Description
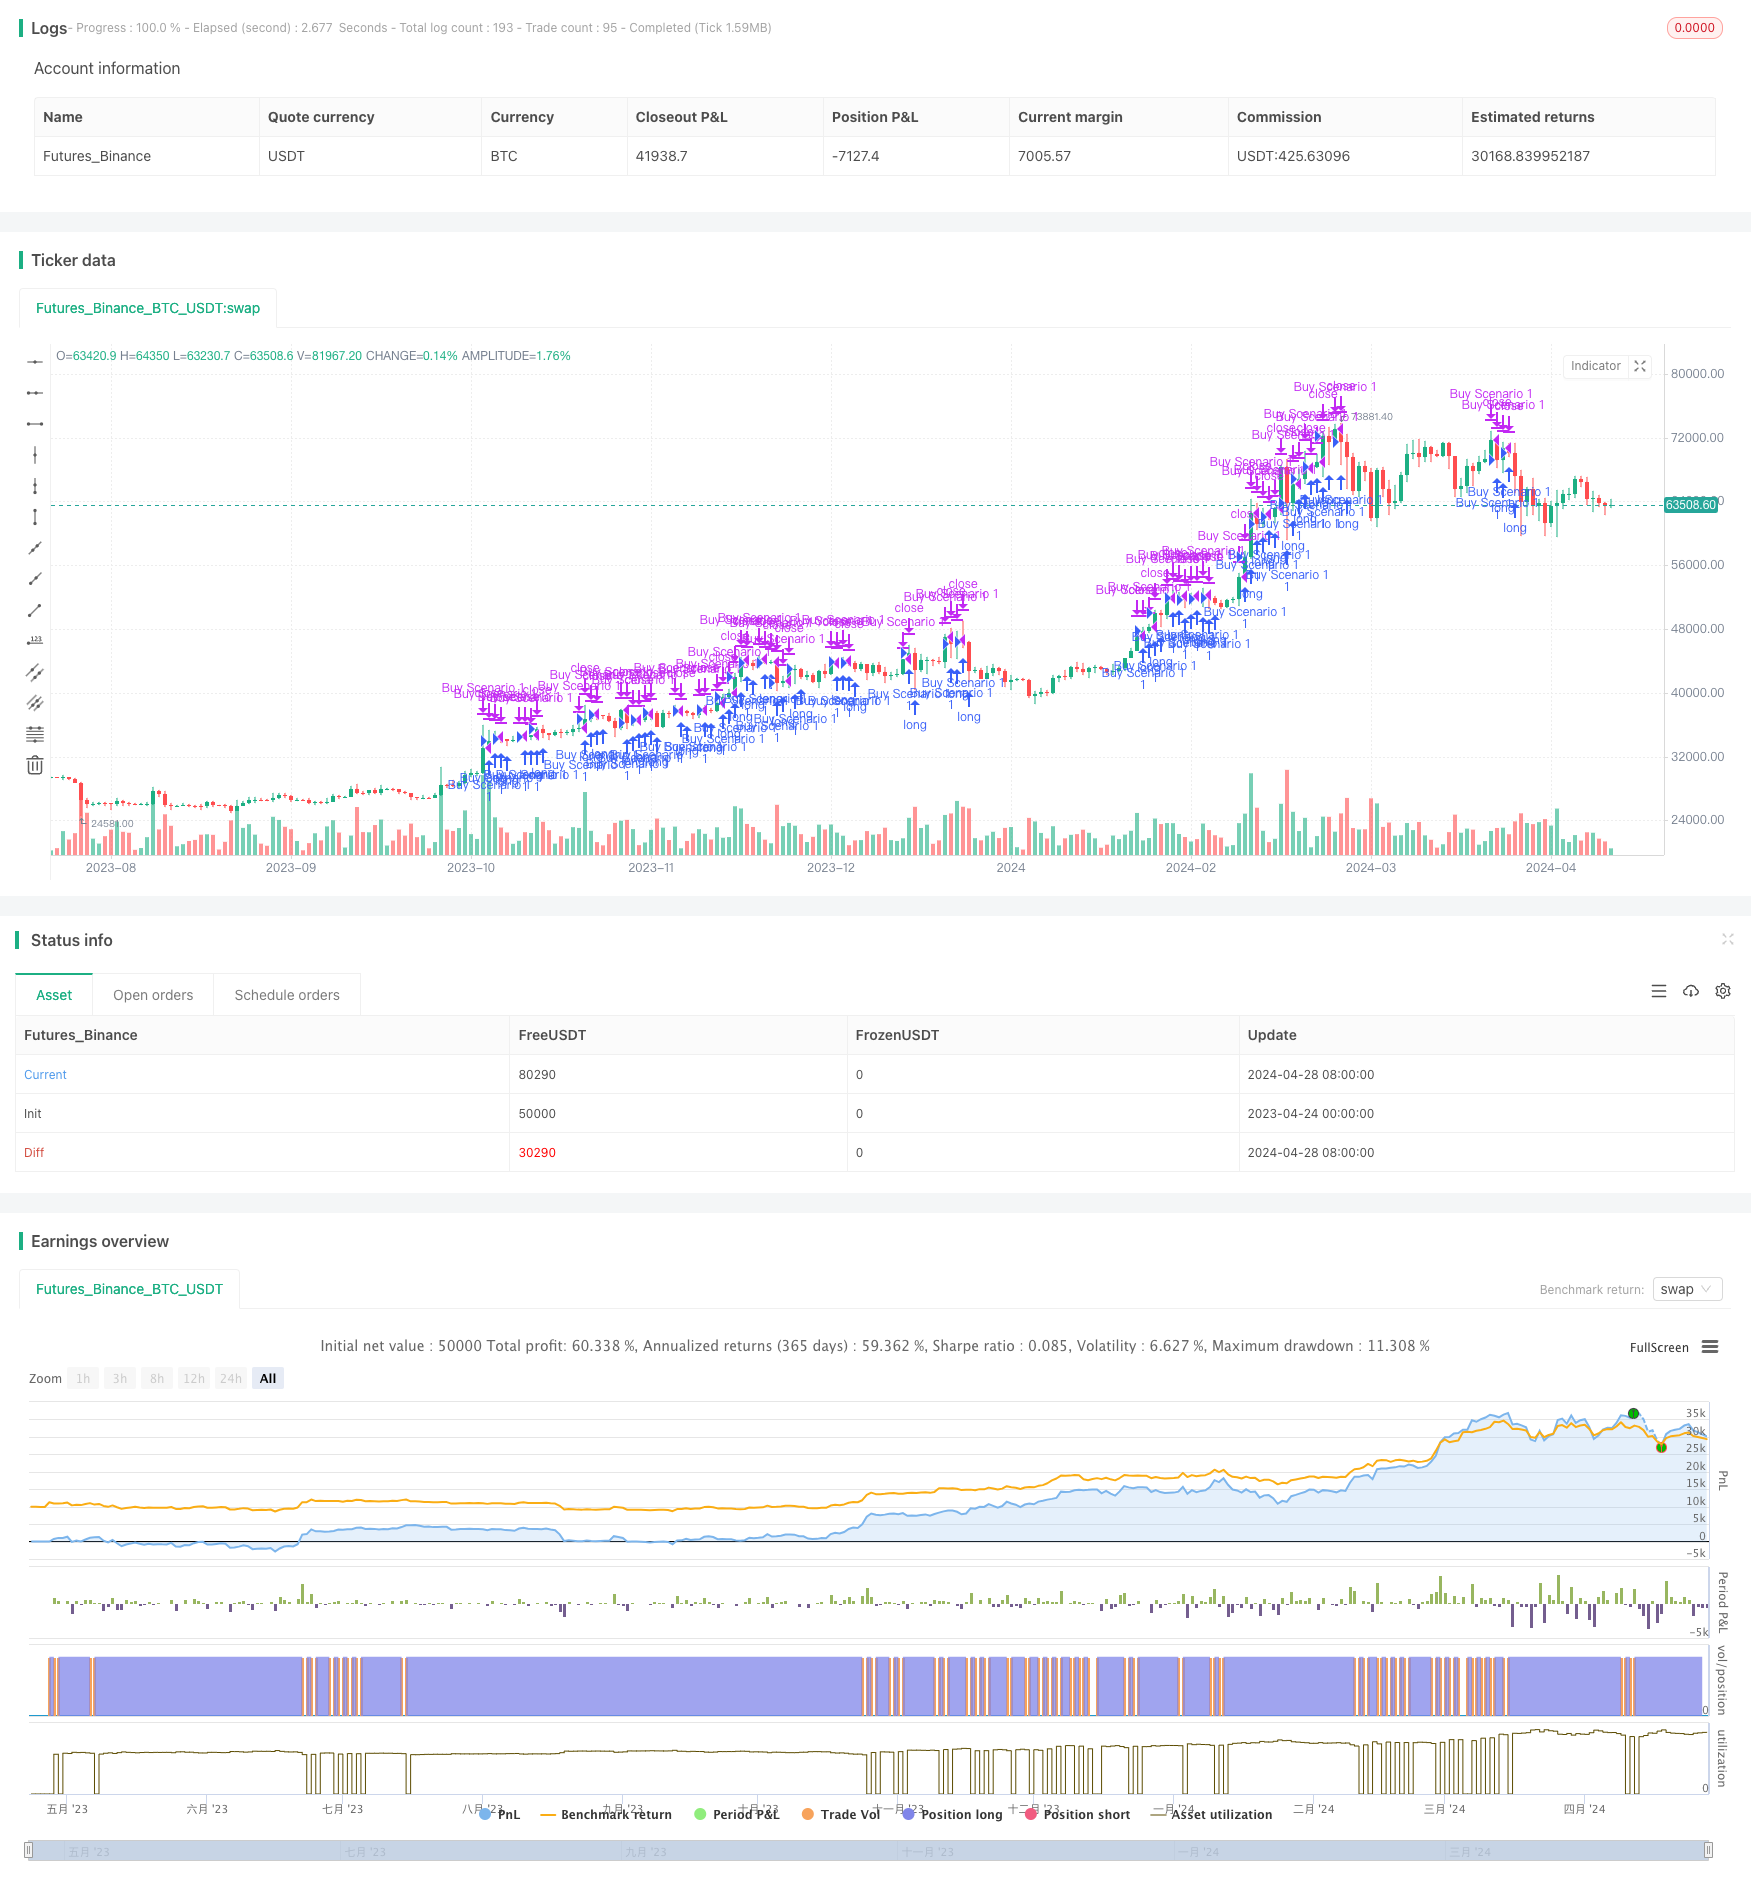
[trans]
概述
这是一个基于5日移动平均线(MA5)的双均线交叉开仓策略。该策略的主要思路是:在MA5上方或下方一定距离处开仓,当收盘价高于开仓价或回到开仓价时平仓。该策略旨在捕捉短期趋势,同时控制风险。
策略原理
该策略使用5日简单移动平均线(SMA)作为主要指标。当新蜡烛图开盘价高于MA5时,执行买入场景1;当新蜡烛图开盘价低于MA5且距离MA5超过0.002点时,执行买入场景2。对于卖出条件,当收盘价高于开仓均价或等于开仓均价时,执行卖出场景1;当收盘价低于开仓均价0.1%时,执行卖出场景2。
优势分析
- 该策略基于短期趋势,能够快速捕捉市场变化。
- 通过设置距离MA5的阈值,可以过滤掉一些噪声信号。
- 通过设置止损条件,可以有效控制风险。
- 策略逻辑清晰,易于理解和实现。
风险分析
- 该策略依赖于单一指标,可能面临指标失效的风险。
- 短期趋势策略可能面临频繁交易,增加交易成本的风险。
- 固定的止损比例可能无法适应不同的市场环境。
优化方向
- 可以考虑引入其他指标,如RSI、MACD等,以提高信号的可靠性。
- 可以优化止损和止盈条件,如使用移动止损或动态止损比例。
- 可以针对不同的市场环境,设置不同的参数,提高策略的适应性。
总结
该双均线交叉开仓策略是一个基于短期趋势的简单策略。通过MA5的上下穿越,以及距离阈值的设置,可以捕捉短期趋势机会。同时,固定比例止损可以控制风险。但该策略也存在一些局限性,如依赖单一指标、频繁交易等。未来可以考虑引入更多指标,优化止损止盈条件,提高策略的稳健性和适应性。
||
Overview
This is a dual moving average crossover entry strategy based on the 5-day moving average (MA5). The main idea of this strategy is to enter positions at a certain distance above or below the MA5, and close positions when the closing price is higher than the entry price or returns to the entry price. This strategy aims to capture short-term trends while controlling risks.
Strategy Principle
This strategy uses the 5-day simple moving average (SMA) as the main indicator. When the opening price of a new candle is above the MA5, it executes buy scenario 1; when the opening price of a new candle is below the MA5 and the distance from the MA5 exceeds 0.002 points, it executes buy scenario 2. For sell conditions, when the closing price is higher than or equal to the average entry price, it executes sell scenario 1; when the closing price is lower than 0.1% of the average entry price, it executes sell scenario 2.
Advantage Analysis
- This strategy is based on short-term trends and can quickly capture market changes.
- By setting a threshold for the distance from the MA5, some noise signals can be filtered out.
- By setting stop-loss conditions, risks can be effectively controlled.
- The strategy logic is clear and easy to understand and implement.
Risk Analysis
- This strategy relies on a single indicator and may face the risk of indicator failure.
- Short-term trend strategies may face frequent trading and increase the risk of transaction costs.
- Fixed stop-loss percentages may not be able to adapt to different market environments.
Optimization Direction
- Other indicators such as RSI and MACD can be considered to improve the reliability of signals.
- Stop-loss and take-profit conditions can be optimized, such as using trailing stops or dynamic stop-loss percentages.
- For different market environments, different parameters can be set to improve the adaptability of the strategy.
Summary
This dual moving average crossover entry strategy is a simple strategy based on short-term trends. By crossing above and below the MA5, and setting distance thresholds, short-term trend opportunities can be captured. At the same time, fixed percentage stop-losses can control risks. However, this strategy also has some limitations, such as relying on a single indicator and frequent trading. In the future, more indicators can be introduced, and stop-loss and take-profit conditions can be optimized to improve the robustness and adaptability of the strategy. [/trans]
Source (PineScript)
/*backtest
start: 2023-04-24 00:00:00
end: 2024-04-29 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("YBS Strategy 1.1", overlay=true)

// Moving Average Settings
ma5 = ta.sma(close, 5)

// Scenario 1: Buy when a new candle opens above the MA5
buy_condition_scenario1 = open > ma5

// Scenario 2: Buy when a new candle opens below the MA5 and is at a significant distance from the MA5
distance_from_ma5 = open - ma5
buy_condition_scenario2 = open < ma5 and distance_from_ma5 > 0.002 // Define distance in points here

// Sell: Sell at the close of the candle if it's positive above the entry price, or if the price returns to the entry price
sell_condition_scenario1 = close > strategy.position_avg_price or close == strategy.position_avg_price
sell_condition_scenario2 = close <= strategy.position_avg_price * 0.999 // Close if price drops more than 0.1% from entry price

// Execute buy and sell orders
if (buy_condition_scenario1 and not (strategy.opentrades > 0))
    strategy.entry("Buy Scenario 1", strategy.long)

if (buy_condition_scenario2 and not (strategy.opentrades > 0))
    strategy.entry("Buy Scenario 2", strategy.long)

if (sell_condition_scenario1)
    strategy.close("Buy Scenario 1")

if (sell_condition_scenario2)
    strategy.close("Buy Scenario 2")
Detail
https://www.fmz.com/strategy/449970
Last Modified
2024-04-30 17:37:53