
8.1 KiB
Name
动量价格通道开仓与平仓策略Momentum-Price-Channel-Opening-and-Closing-Strategy
Author
ChaoZhang
Strategy Description
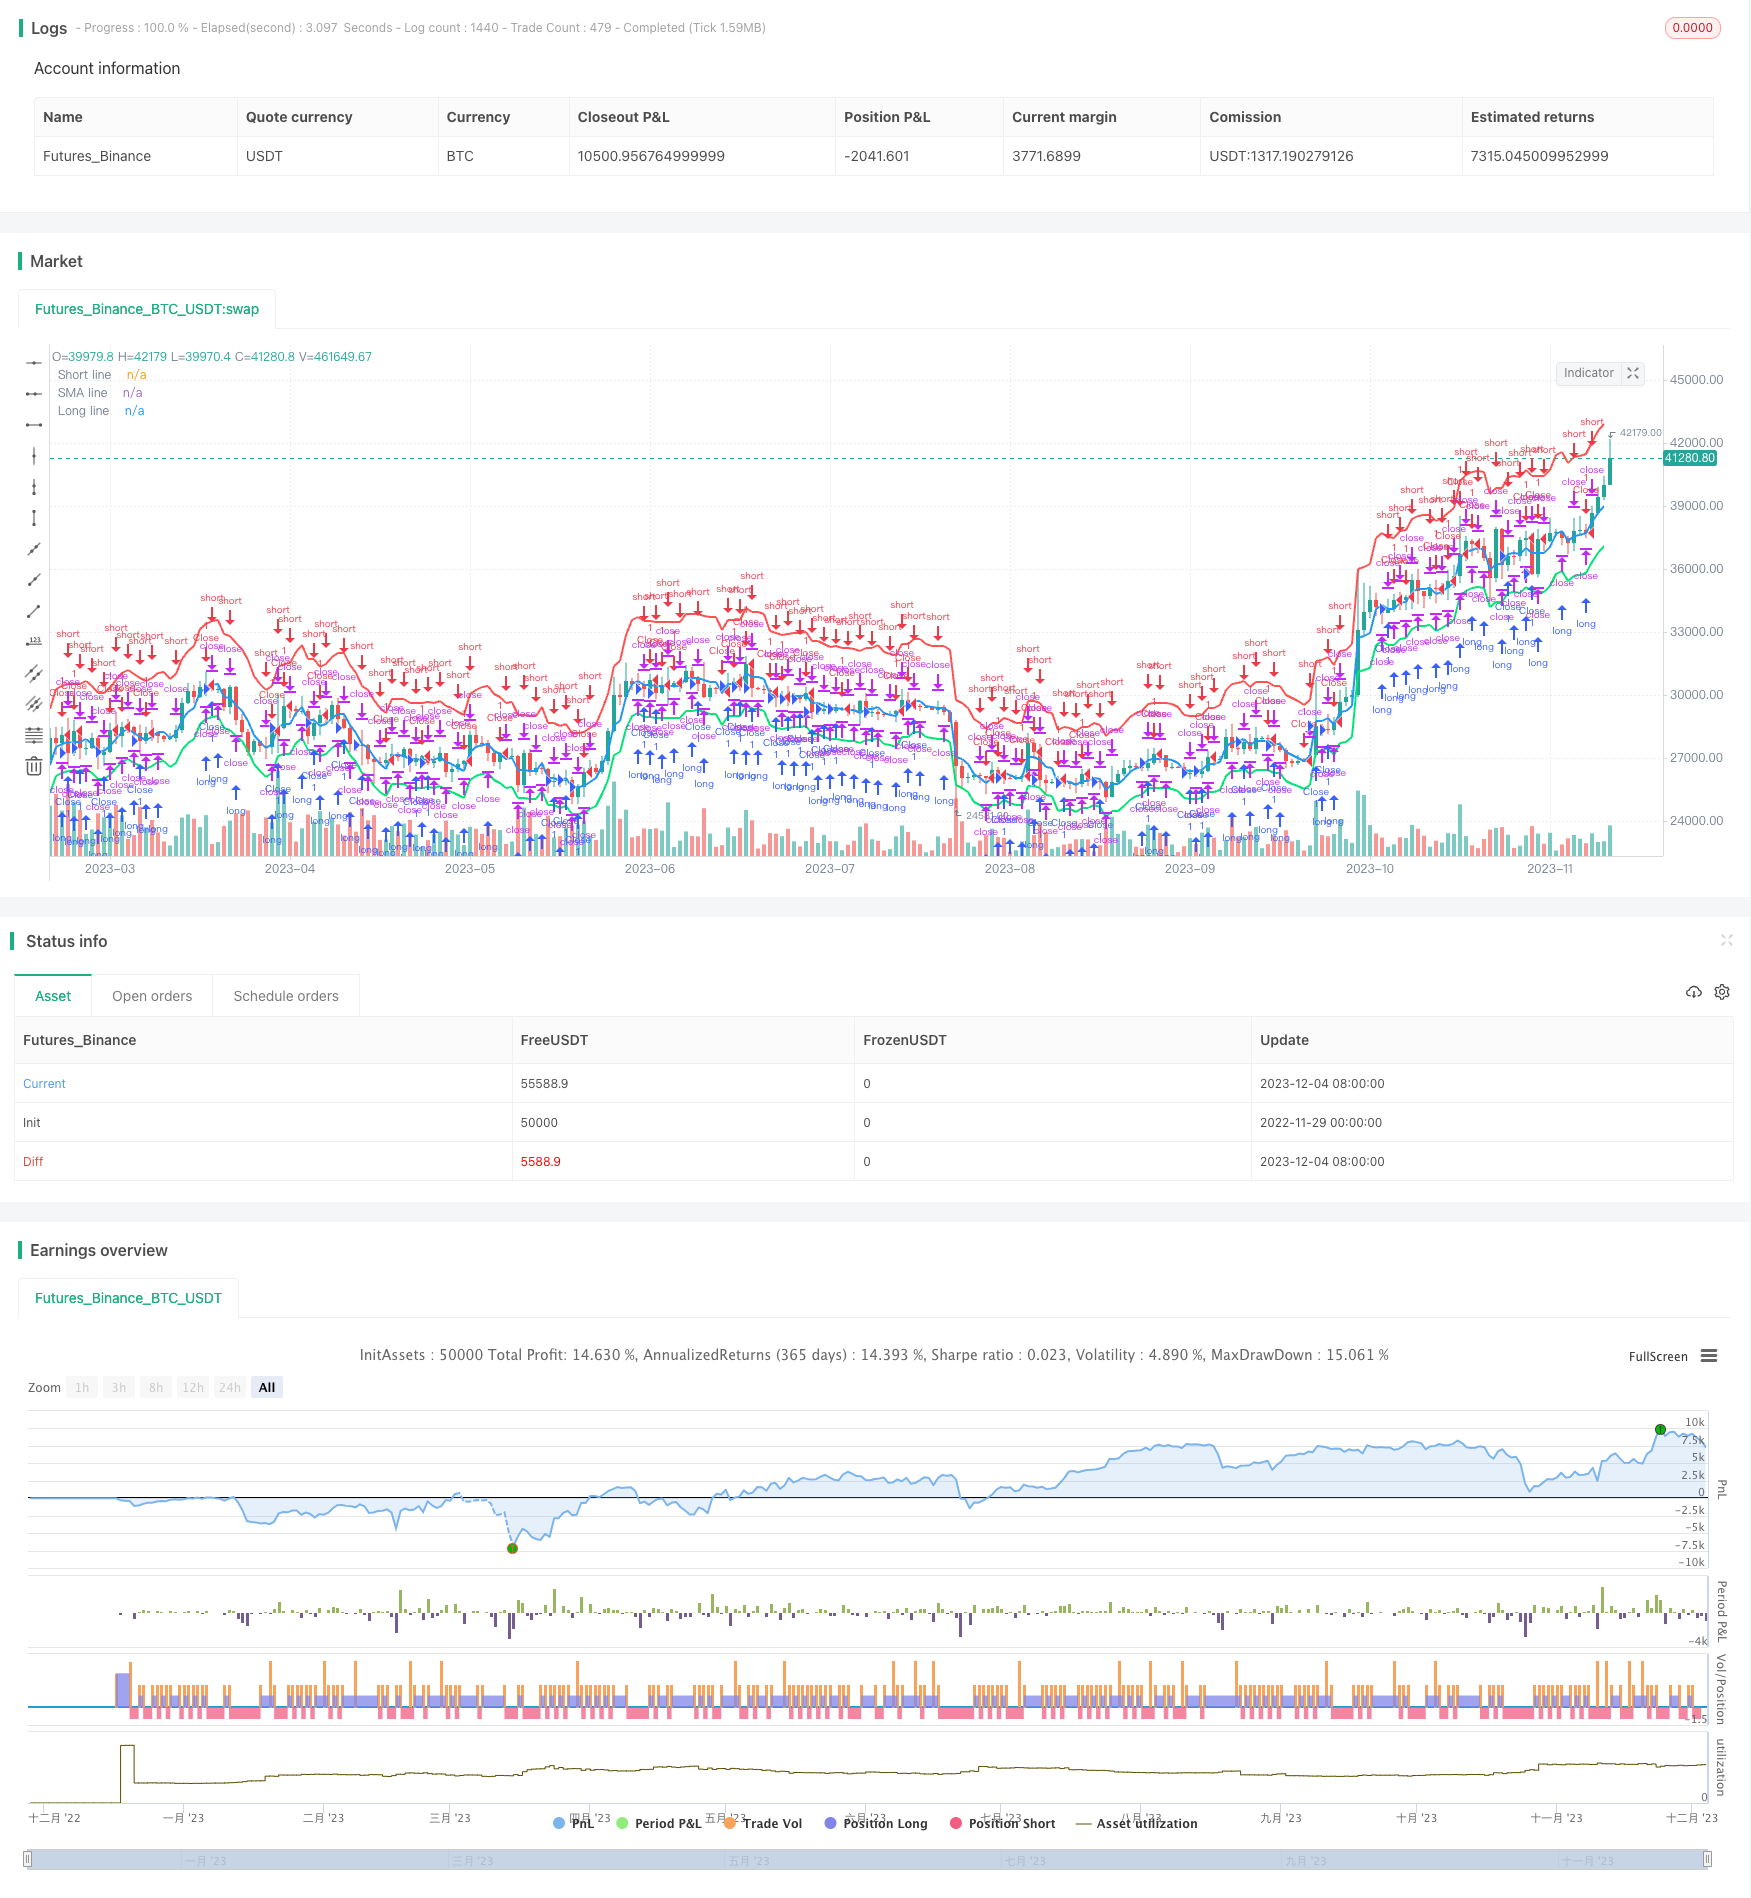
[trans]
概述
该策略基于价格通道指标,设置了动量参数,通过计算不同周期的最高价和最低价的均值,形成价格通道中线,以此为基准,设置长线和短线。当价格突破长线时,做多;当价格突破短线时,做空。平仓条件为价格回归通道中线。
策略原理
该策略使用价格通道指标计算不同周期内的最高价和最低价的均值,形成价格通道中线。以中线为基准,通过shift参数设置长线和短线。具体来说,长线计算公式为:中线+(中线×长线参数%);短线计算公式为:中线+(中线×短线参数%)。
当价格低于长线时,使用限价单开多单;当价格高于短线时,使用限价单开空单。多空单的止损方式为价格回归通道中线。
优势分析
该策略具有以下优势:
- 使用价格通道指标,可以有效捕捉价格趋势和关键支持阻力位。
- 采用突破记录方式开仓,可以减少假突破带来的亏损。
- 止损方式直接以价格通道中线为标准,避免追价止损带来的过度亏损。
风险分析
该策略也存在一些风险:
- 价格通道参数设置不当,可能错过积极行情或产生过多假突破。
- 突破开仓方式带来一定程度划渡成本。
- 价格快速回落期间,无法及时止损。
可以通过优化参数,设置止损单,或者结合其他指标判断来减轻上述风险。
优化方向
该策略可以从以下几个方面进行优化:
- 优化价格通道的参数,寻找最佳组合。
- 尝试不同的开仓方式,如K线形态、指标多空信号等。
- 增加止损单设置,防止价格快速回落带来的亏损。
- 结合交易量、波动率等指标,避免在 shares市场产生假突破。
总结
本策略基于价格通道指标设计思路清晰,使用突破开仓可以有效控制风险。但也存在参数优化空间较大,止损机制有待完善等问题。总体来说,该策略具有一定的实用价值,值得进一步测试与优化。
||
Overview
This strategy is based on the price channel indicator. By setting a momentum parameter, it calculates the mean value of the highest and lowest prices in different cycles to form the median line of the price channel, and sets long and short lines based on this. When the price breaks through the long line, it goes long; when the price breaks through the short line, it goes short. The closing condition is that the price regresses to the channel midline.
Strategy Principle
This strategy uses the price channel indicator to calculate the mean value of the highest and lowest prices in different cycles to form the channel midline. Based on the midline, long and short lines are set through the shift parameter. Specifically, the long line calculation formula is: midline + (midline × long line parameter%); the short line calculation formula is: midline + (midline × short line parameter%).
When the price is lower than the long line, open long positions with limit orders; when the price is higher than the short line, open short positions with limit orders. The stop loss method for long and short positions is the price regressing to the channel midline.
Advantage Analysis
The strategy has the following advantages:
- Using the price channel indicator can effectively capture price trends and key support/resistance levels.
- Opening positions on breakouts can reduce losses from false breakouts.
- The stop loss method directly takes the price channel midline as the standard to avoid excessive losses from chase stops.
Risk Analysis
The strategy also has some risks:
- Improper parameter settings of the price channel may miss active trends or generate too many false breakouts.
- Breakout opening methods incur a certain degree of slippage costs.
- Unable to stop loss in time during rapid price retracements.
The above risks can be mitigated by optimizing parameters, setting stop loss orders, or combining other indicators for judgment.
Optimization Directions
The strategy can be optimized in the following aspects:
- Optimize the parameters of the price channel to find the best combination.
- Try different opening methods such as candlestick patterns and indicator signals.
- Add stop loss order settings to prevent losses from rapid price drops.
- Combine trading volume, volatility and other indicators to avoid false breakouts in the stock market.
Conclusion
The design idea of this strategy based on the price channel indicator is clear. Using breakout to open positions can effectively control risks. But there are also large parameter optimization spaces and stop loss mechanisms that need to be improved. Overall, the strategy has a certain practical value and is worth further testing and optimization.
[/trans]
Strategy Arguments
| Argument | Default | Description |
|---|---|---|
| v_input_1 | true | Long |
| v_input_2 | true | Short |
| v_input_3 | 100 | Lot, % |
| v_input_4 | 3 | Length |
| v_input_5 | 10 | Short line (red) |
| v_input_6 | -5 | Long line (lime) |
| v_input_7 | 1900 | From Year |
| v_input_8 | 2100 | To Year |
| v_input_9 | true | From Month |
| v_input_10 | 12 | To Month |
| v_input_11 | true | From day |
| v_input_12 | 31 | To day |
Source (PineScript)
/*backtest
start: 2022-11-29 00:00:00
end: 2023-12-05 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Noro
//2018

//@version=3
strategy(title = "Noro's PCMA Strategy v1.0", shorttitle = "PCMA 1.0", overlay = true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 0)

//Settings
needlong = input(true, defval = true, title = "Long")
needshort = input(true, defval = true, title = "Short")
capital = input(100, defval = 100, minval = 1, maxval = 10000, title = "Lot, %")
per = input(3, title = "Length")
shortlevel = input(10.0, title = "Short line (red)")
longlevel = input(-5.0, title = "Long line (lime)")
fromyear = input(1900, defval = 1900, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To day")

//Price Channel
h = highest(high, per)
l = lowest(low, per)
c = (h + l) / 2
ll = c + ((c / 100) * longlevel)
sl = c + ((c / 100) * shortlevel)

//Lines
shortcolor = needshort ? red : na
longcolor = needlong ? lime : na
plot(sl, linewidth = 2, color = shortcolor, title = "Short line")
plot(c, linewidth = 2, color = blue, title = "SMA line")
plot(ll, linewidth = 2, color = longcolor, title = "Long line")

//Trading
size = strategy.position_size
lot = 0.0
lot := size == 0 ? strategy.equity / close * capital / 100 : lot[1]

if (not na(close[per])) and size == 0 and needlong
    strategy.entry("L", strategy.long, lot, limit = ll, when = (time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if (not na(close[per])) and size == 0 and needshort
    strategy.entry("S", strategy.short, lot, limit = sl, when = (time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if (not na(close[per])) and size > 0
    strategy.entry("Close", strategy.short, 0, limit = c, when = (time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if (not na(close[per])) and size < 0
    strategy.entry("Close", strategy.long, 0, limit = c, when = (time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if time > timestamp(toyear, tomonth, today, 23, 59)
    strategy.close_all()
Detail
https://www.fmz.com/strategy/434469
Last Modified
2023-12-06 16:44:32