
5.5 KiB
Name
动态趋势动量突破策略-Dynamic-Trend-Momentum-Breakout-Strategy
Author
ianzeng123
Strategy Description
[trans]
概述
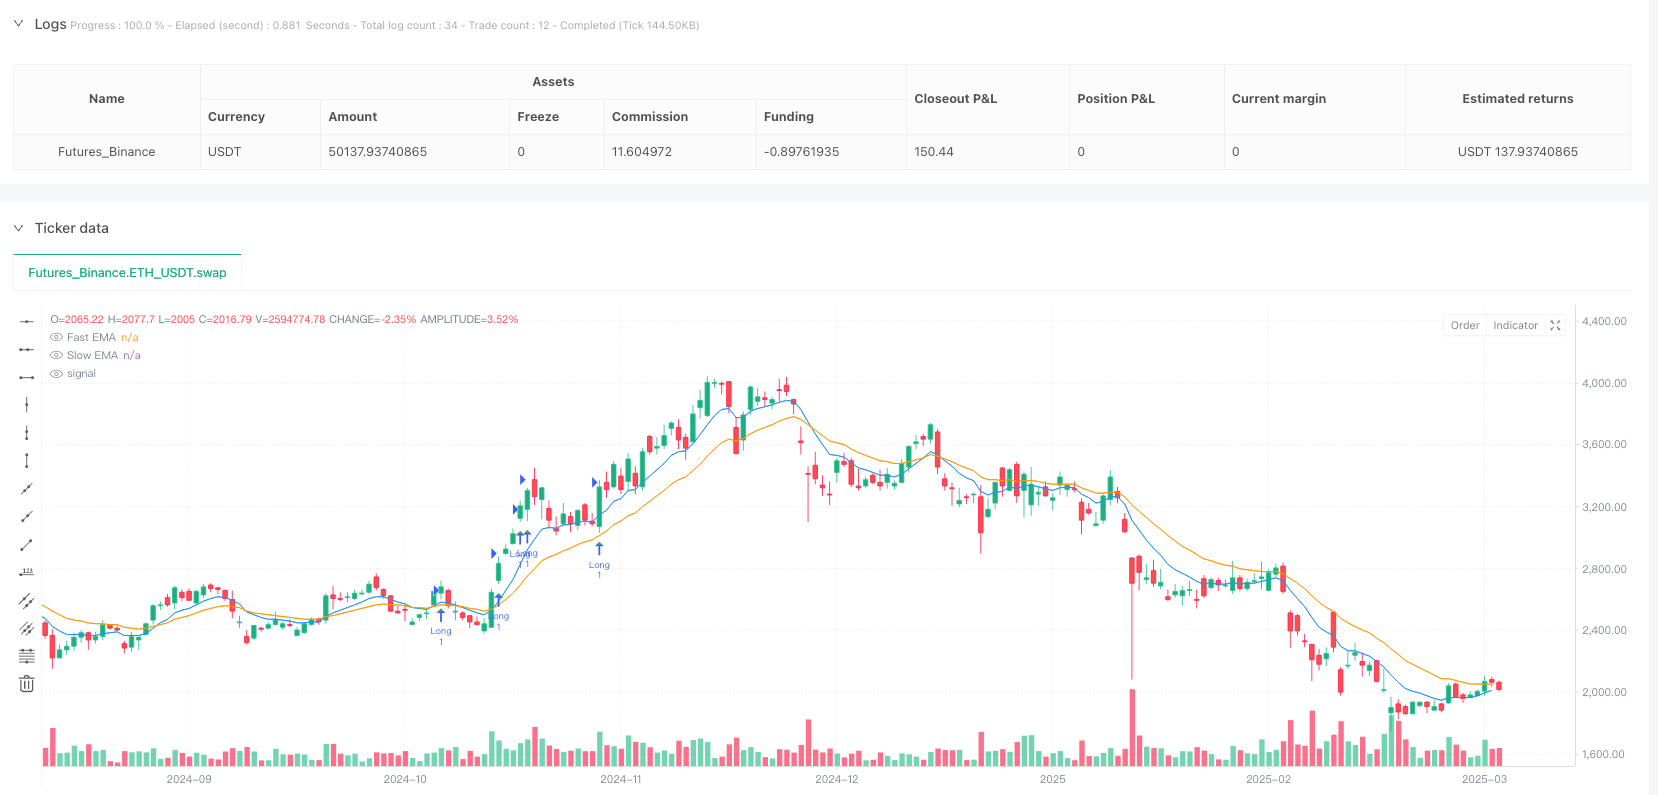
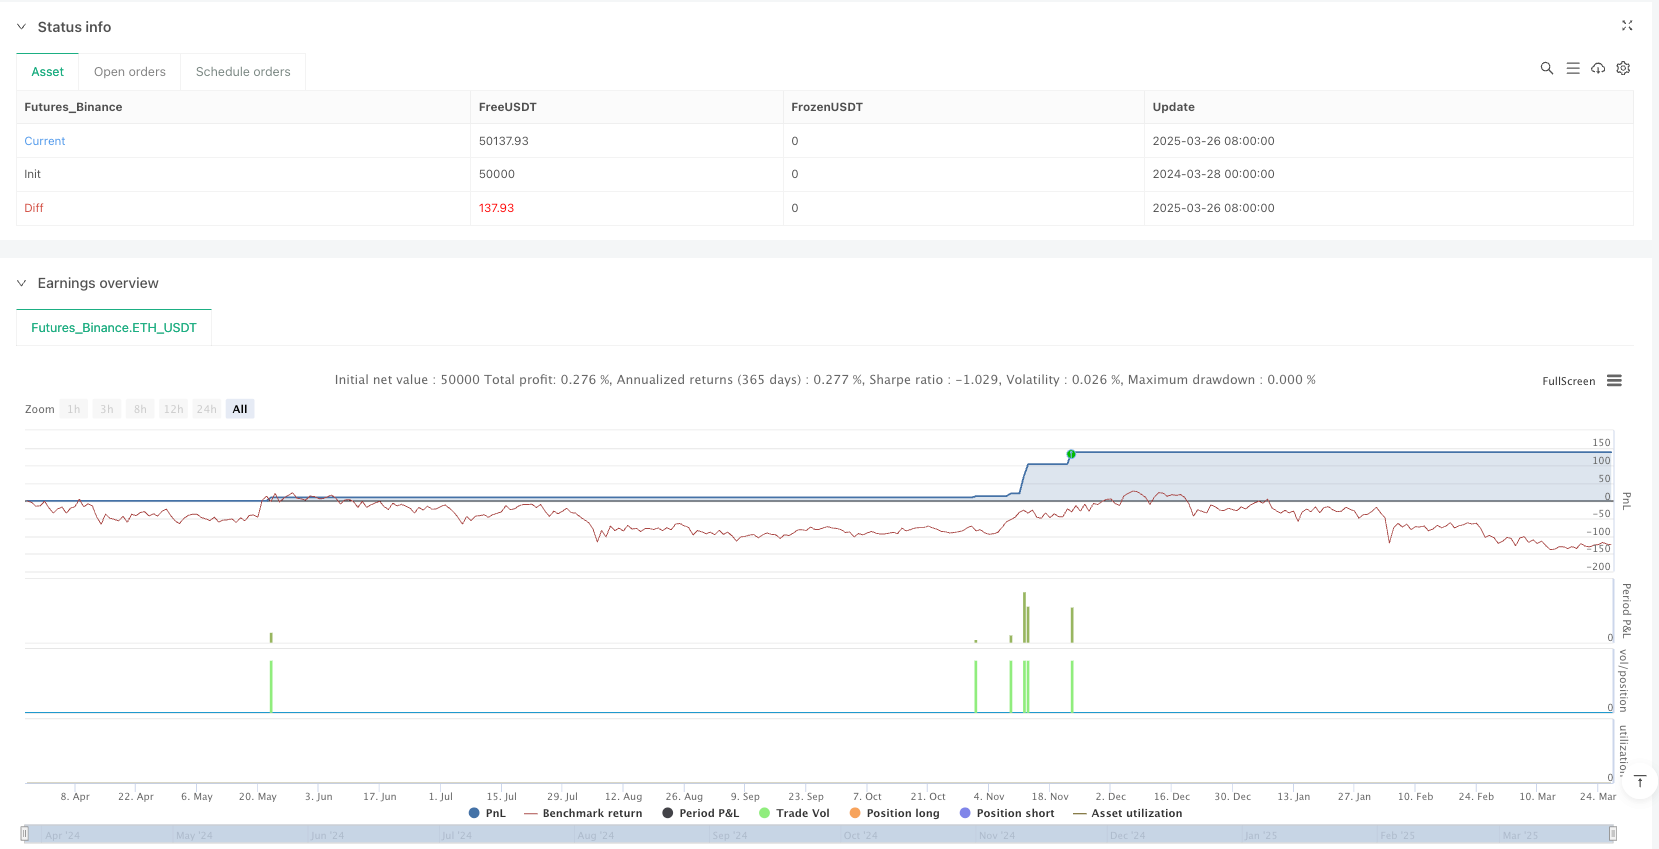
动态趋势动量突破策略是一种专业的量化交易方法,专门针对高动量股票设计。该策略通过结合指数移动平均线(EMA)、相对强弱指数(RSI)过滤、成交量确认和平均真实波动范围(ATR)为基础的追踪止损,旨在捕捉强劲的市场突破,同时避免虚假信号。
策略原理
该策略的核心原理基于多维度市场信号验证:
- 使用快速和慢速EMA判断整体趋势方向
- 利用RSI评估动量和避免负面背离
- 通过成交量突破确认交易信号
- 应用ATR动态管理止损和追踪止盈
策略优势
- 高精确度信号过滤:多重条件验证降低错误信号概率
- 动态风险管理:基于ATR的止损机制保护资金
- 趋势跟随:EMA组合确保仅在强势趋势中入场
- 动量捕捉:成交量和RSI过滤确保交易质量
策略风险
- 市场剧烈波动可能导致止损被触发
- 在震荡市场中可能产生更多无效信号
- 过度依赖技术指标可能错过重要基本面信息
策略优化方向
- 引入机器学习算法优化参数选择
- 增加跨时间框架验证机制
- 开发更复杂的多因子过滤算法
- 结合情绪指标和基本面数据
总结
动态趋势动量突破策略通过综合多种技术分析工具,构建了一个相对稳健的量化交易方法。其核心在于平衡信号捕捉能力和风险控制,为交易者提供了一个系统化的交易决策框架。
||
Overview
The Dynamic Trend Momentum Breakout Strategy is a professional quantitative trading method specifically designed for high-momentum stocks. By combining Exponential Moving Averages (EMA), Relative Strength Index (RSI) filtering, volume confirmation, and Average True Range (ATR)-based trailing stop-loss, the strategy aims to capture strong market breakouts while avoiding false signals.
Strategy Principles
The core principle of the strategy is based on multi-dimensional market signal verification:
- Use fast and slow EMAs to determine overall trend direction
- Utilize RSI to assess momentum and avoid negative divergences
- Confirm trading signals through volume breakouts
- Apply ATR for dynamic stop-loss and trailing profit management
Strategy Advantages
- High-precision signal filtering: Multiple condition verifications reduce error signal probability
- Dynamic risk management: ATR-based stop-loss mechanism protects capital
- Trend following: EMA combination ensures entry only in strong trends
- Momentum capture: Volume and RSI filtering ensure trade quality
Strategy Risks
- Severe market volatility may trigger stop-losses
- More invalid signals may occur in ranging markets
- Over-reliance on technical indicators might miss important fundamental information
Strategy Optimization Directions
- Introduce machine learning algorithms to optimize parameter selection
- Add cross-timeframe verification mechanisms
- Develop more complex multi-factor filtering algorithms
- Incorporate sentiment indicators and fundamental data
Summary
The Dynamic Trend Momentum Breakout Strategy builds a relatively robust quantitative trading method by integrating multiple technical analysis tools. Its core lies in balancing signal capture capability and risk control, providing traders with a systematic trading decision framework.[/trans]
Source (PineScript)
/*backtest
start: 2024-03-28 00:00:00
end: 2025-03-27 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"ETH_USDT"}]
*/

//@version=6
strategy("Enhanced First High Break Strategy v3", overlay=true, margin_long=100, margin_short=100)

// Input Parameters
emaFastLength = input.int(9, "Fast EMA Length")
emaSlowLength = input.int(20, "Slow EMA Length")
rsiLength = input.int(14, "RSI Length")
volumeAvgLength = input.int(20, "Volume Average Length")
atrLength = input.int(14, "ATR Length")

// Calculate Indicators
emaFast = ta.ema(close, emaFastLength)
emaSlow = ta.ema(close, emaSlowLength)
rsi = ta.rsi(close, rsiLength)
volAvg = ta.sma(volume, volumeAvgLength)
atr = ta.atr(atrLength)

// Pre-calculate lowest values (FIXED)
rsiLowCurrent = ta.lowest(rsi, 5)
rsiLowPrevious = ta.lowest(rsi[5], 5)
lowLowPrevious = ta.lowest(low[5], 5)

// Trend Conditions
bullishTrend = emaFast > emaSlow and emaFast > emaFast[1]
bearishDivergence = rsiLowCurrent > rsiLowPrevious and low < lowLowPrevious

// Entry Conditions
validBreakout = close > high[1] and close > emaFast
volumeConfirmation = volume > volAvg * 1.5
trendConfirmed = close > emaSlow and close[1] > emaSlow
rsiConfirmation = rsi > 50 and not bearishDivergence

// Final Entry Signal
entryCondition = validBreakout and volumeConfirmation and trendConfirmed

// Exit Conditions
stopLossPrice = low[1] - (atr * 0.50)
trailOffset = atr * 2

// Strategy Execution
if (entryCondition)
    strategy.entry("Long", strategy.long)
    strategy.exit("Exit", "Long", stop=stopLossPrice,trail_points=close > emaFast ? trailOffset : na,trail_offset=trailOffset)

// Plotting
plot(emaFast, "Fast EMA", color.new(color.blue, 0))
plot(emaSlow, "Slow EMA", color.new(color.orange, 0))
plotshape(entryCondition, style=shape.triangleup, color=color.green, location=location.belowbar)
Detail
https://www.fmz.com/strategy/488546
Last Modified
2025-03-28 17:41:01