
14 KiB
Name
动态流动性驱动市场结构自适应交易策略-Dynamic-Liquidity-Driven-Market-Structure-Adaptive-Trading-Strategy
Author
ianzeng123
Strategy Description
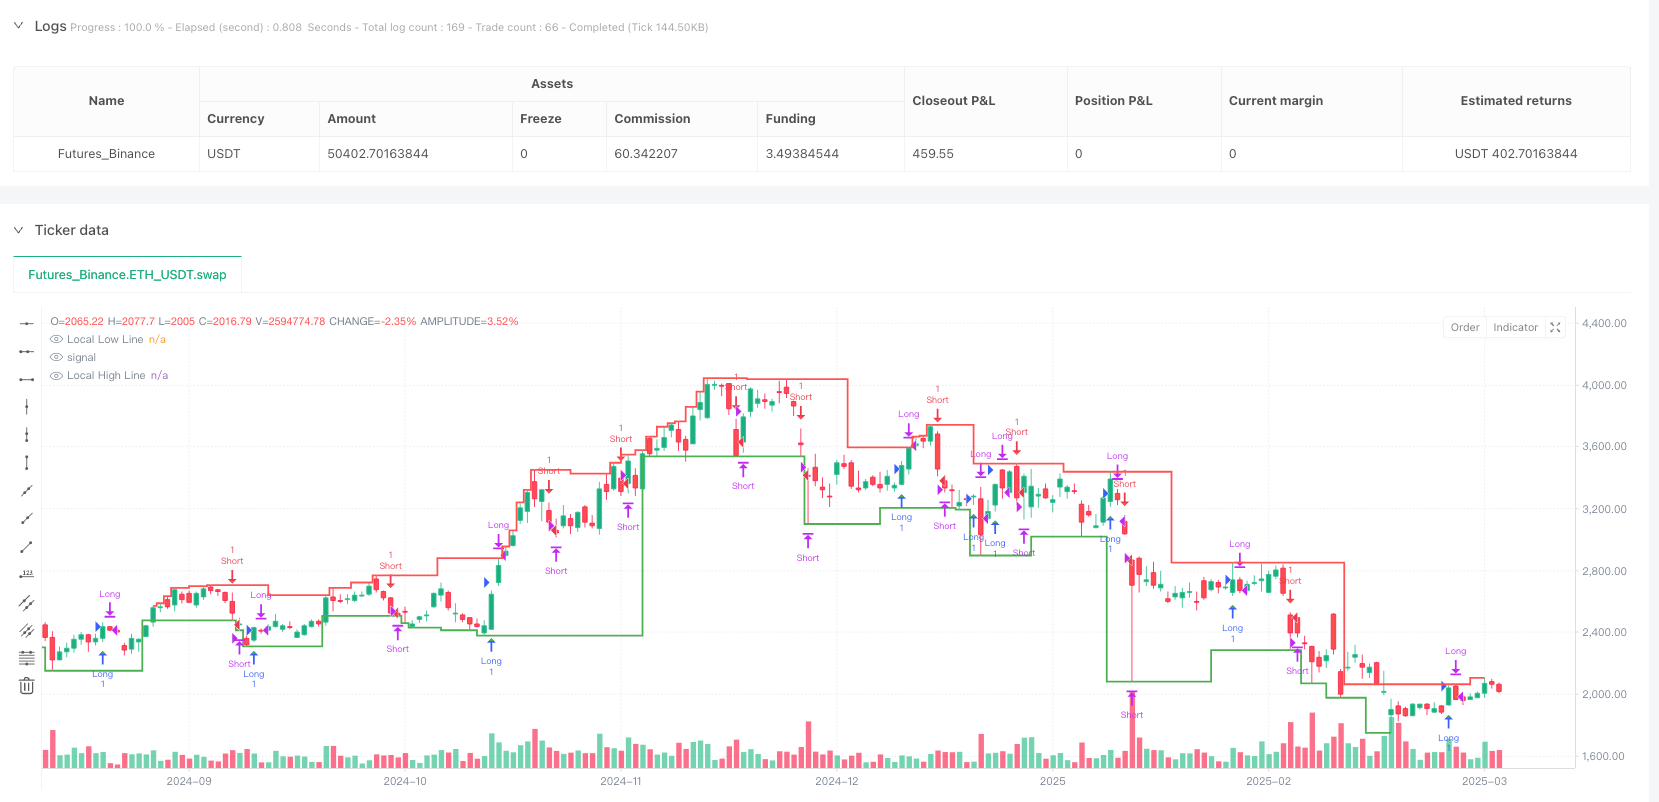
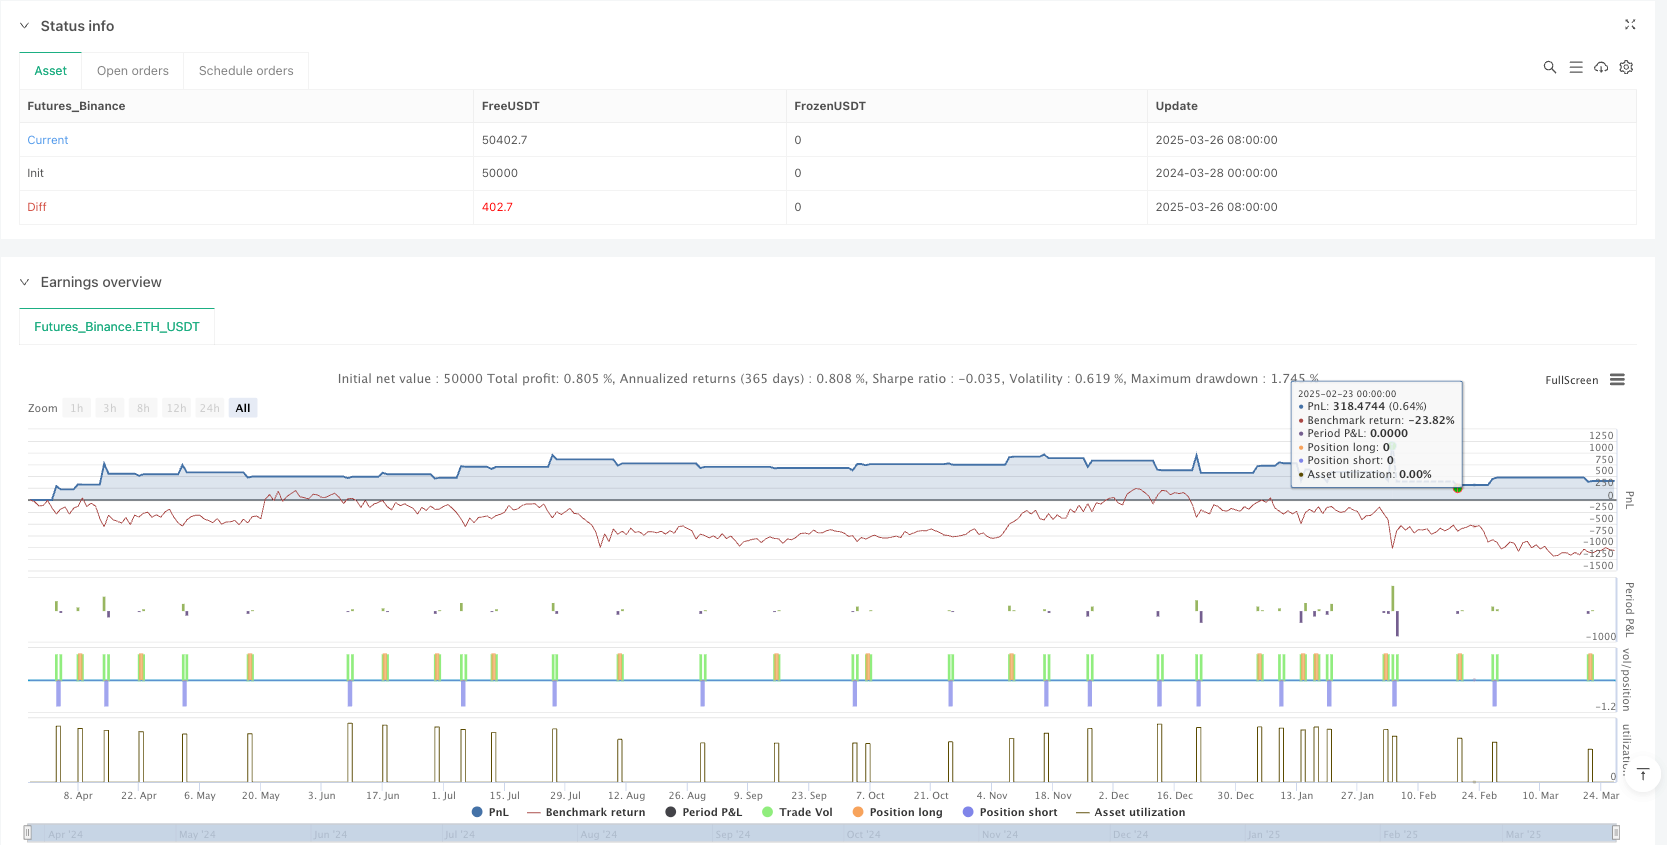
[trans]
概述
这是一种创新的交易策略,结合了流动性区域分析和内部市场结构动态,旨在识别高概率入场点。该策略通过追踪价格与关键市场水平的互动,并利用内部市场转换触发交易,为交易者提供了一种灵活且精准的市场进入方法。
策略原理
策略的核心逻辑基于两个关键组件:流动性区域识别和内部市场转换。流动性区域通过分析局部高点和低点来动态确定,而内部市场转换则基于价格突破先前的bullish或bearish水平来判断市场方向变化。
策略具有以下核心特征:
- 内部市场转换逻辑:不依赖传统蜡烛图形态,而是基于价格突破关键水平
- 流动性区域追踪:动态识别关键流动性区域,防止在弱市条件下交易
- 模式灵活性:提供"Both"、"Bullish Only"和"Bearish Only"三种交易模式
- 风险管理:可自定义止损和止盈水平
- 时间范围控制:可精确控制交易时间段
策略优势
- 动态适应性:策略能够快速响应市场结构变化
- 精确入场:通过结合流动性区域和内部市场转换,提高入场精确度
- 风险可控:内置止损和止盈机制
- 灵活性强:可根据不同市场条件选择交易模式
- 多维度分析:同时考虑价格行为、流动性和市场结构
策略风险
- 市场剧烈波动可能导致止损被触发
- 在震荡市场中,频繁的信号可能增加交易成本
- 参数设置不当可能影响策略表现
- 回测结果可能与实盘存在差异
策略优化方向
- 引入机器学习算法进行参数自适应优化
- 增加更多过滤条件,如交易量、波动率指标
- 开发多时间框架验证机制
- 优化止损和止盈算法,考虑市场波动率动态调整
总结
这是一种融合流动性分析和市场结构动态的创新交易策略。通过灵活的内部市场转换逻辑和精确的流动性区域追踪,为交易者提供了一个强大的交易工具。策略的关键在于其适应性和多维度分析能力,能够在不同市场条件下保持较高的执行效率。 ||
Overview
This is an innovative trading strategy that combines liquidity zone analysis with dynamic internal market structure, aiming to identify high-probability entry points. By tracking price interactions with key market levels and utilizing internal market shifts to trigger trades, the strategy provides traders with a flexible and precise market entry approach.
Strategy Principles
The core logic is based on two key components: liquidity zone identification and internal market shifts. Liquidity zones are dynamically determined by analyzing local highs and lows, while internal market shifts are judged by price breakouts of previous bullish or bearish levels.
The strategy features the following core characteristics:
- Internal Market Shift Logic: Relies on price breakouts of key levels rather than traditional candlestick patterns
- Liquidity Zone Tracking: Dynamically identifies key liquidity zones to prevent trading in weak market conditions
- Mode Flexibility: Offers three trading modes - "Both", "Bullish Only", and "Bearish Only"
- Risk Management: Customizable stop-loss and take-profit levels
- Time Range Control: Precise control of trading time periods
Strategy Advantages
- Dynamic Adaptability: Quickly responds to market structure changes
- Precise Entry: Enhances entry accuracy by combining liquidity zones and internal market shifts
- Controllable Risk: Built-in stop-loss and take-profit mechanisms
- High Flexibility: Can choose trading modes based on different market conditions
- Multi-Dimensional Analysis: Simultaneously considers price behavior, liquidity, and market structure
Strategy Risks
- Extreme market volatility may trigger stop-losses
- Frequent signals in range-bound markets may increase trading costs
- Improper parameter settings may affect strategy performance
- Potential discrepancies between backtesting and live trading results
Strategy Optimization Directions
- Introduce machine learning algorithms for parameter adaptive optimization
- Add more filtering conditions, such as trading volume and volatility indicators
- Develop multi-timeframe verification mechanisms
- Optimize stop-loss and take-profit algorithms with dynamic market volatility adjustments
Summary
This is an innovative trading strategy that integrates liquidity analysis and market structure dynamics. By providing flexible internal market shift logic and precise liquidity zone tracking, it offers traders a powerful trading tool. The strategy's key strength lies in its adaptability and multi-dimensional analysis capabilities, maintaining high execution efficiency across different market conditions. [/trans]
Source (PineScript)
/*backtest
start: 2024-03-28 00:00:00
end: 2025-03-27 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"ETH_USDT"}]
*/

//@version=6
strategy("Liquidity + Internal Market Shift Strategy", overlay=true)

// ======== Mode Selection ========
mode = input.string("Both", title="Mode", options=["Both", "Bullish Only", "Bearish Only"])

// ======== Stop-Loss and Take-Profit Input (in pips) ========
enableTakeProfit = input.bool(true, title="Enable Custom Take Profit")  // Option to enable/disable take profit
stopLossPips = input.int(10, title="Stop Loss (in pips)", minval=1)  // Stop loss in pips
takeProfitPips = input.int(20, title="Take Profit (in pips)", minval=1)  // Take profit in pips

// ======== Internal Shift Logic ========

// Fixed number of consecutive candles to track (set to 1)
consecutiveBullishCount = 1
consecutiveBearishCount = 1

// Function to check for bullish and bearish candles
isBullish = close > open
isBearish = close < open

// Variables to track consecutive candles and mark lowest/highest
var int bullishCount = 0
var int bearishCount = 0
var float lowestBullishPrice = na
var float highestBearishPrice = na
var float previousBullishPrice = na // For the previous bullish lowest price
var float previousBearishPrice = na // For the previous bearish highest price

// Variables to track last internal shift type (1 = Bullish, -1 = Bearish, 0 = None)
var int lastInternalShift = 0

// Counting consecutive bullish and bearish candles
if isBullish
    bullishCount := bullishCount + 1
    bearishCount := 0
    if bullishCount == 1 or low < lowestBullishPrice
        lowestBullishPrice := low
else if isBearish
    bearishCount := bearishCount + 1
    bullishCount := 0
    if bearishCount == 1 or high > highestBearishPrice
        highestBearishPrice := high
else
    bullishCount := 0
    bearishCount := 0
    lowestBullishPrice := na
    highestBearishPrice := na

// Internal shift conditions
internalShiftBearish = close < previousBullishPrice and close < lowestBullishPrice
internalShiftBullish = close > previousBearishPrice and close > highestBearishPrice

// Condition to alternate internal shifts
allowInternalShiftBearish = internalShiftBearish and lastInternalShift != -1
allowInternalShiftBullish = internalShiftBullish and lastInternalShift != 1

// Tracking shifts
if bullishCount >= consecutiveBullishCount
    previousBullishPrice := lowestBullishPrice

if bearishCount >= consecutiveBearishCount
    previousBearishPrice := highestBearishPrice

// ======== Liquidity Seal-Off Points Logic ========
upperLiquidityLookback = input.int(10, title="Lookback Period for Upper Liquidity Line")
lowerLiquidityLookback = input.int(10, title="Lookback Period for Lower Liquidity Line")

isLocalHigh = high == ta.highest(high, upperLiquidityLookback)
isLocalLow = low == ta.lowest(low, lowerLiquidityLookback)

var bool touchedLowerLiquidityLine = false
var bool touchedUpperLiquidityLine = false

if (low <= ta.lowest(low, lowerLiquidityLookback))
    touchedLowerLiquidityLine := true

if (high >= ta.highest(high, upperLiquidityLookback))
    touchedUpperLiquidityLine := true

var bool lockedBullish = false
var bool lockedBearish = false
var int barSinceLiquidityTouch = na

// ======== Combined Signals ========
bullishSignal = allowInternalShiftBullish and touchedLowerLiquidityLine and not lockedBullish
bearishSignal = allowInternalShiftBearish and touchedUpperLiquidityLine and not lockedBearish

if bullishSignal
    lockedBullish := true
    touchedLowerLiquidityLine := false
    barSinceLiquidityTouch := 0

if bearishSignal
    lockedBearish := true
    touchedUpperLiquidityLine := false
    barSinceLiquidityTouch := 0

if not na(barSinceLiquidityTouch)
    barSinceLiquidityTouch := barSinceLiquidityTouch + 1

if barSinceLiquidityTouch >= 3
    lockedBullish := false
    lockedBearish := false

if touchedLowerLiquidityLine
    lockedBullish := false

if touchedUpperLiquidityLine
    lockedBearish := false

// ======== Plot Combined Signals ========
plotshape(bullishSignal, style=shape.triangleup, location=location.belowbar, color=color.green, size=size.tiny, title="Bullish Signal")
plotshape(bearishSignal, style=shape.triangledown, location=location.abovebar, color=color.red, size=size.tiny, title="Bearish Signal")

plot(isLocalHigh ? high : na, color=color.red, linewidth=2, style=plot.style_stepline, title="Local High Line")
plot(isLocalLow ? low : na, color=color.green, linewidth=2, style=plot.style_stepline, title="Local Low Line")

// ======== Track Entry and Opposing Signals ========
var float entryPrice = na
var int entryTime = na
var string positionSide = ""

// ======== Strategy Execution (Mode Logic) ========
if (mode == "Both")
    // Short Entry Logic (Bearish Signal)
    if (bearishSignal and na(entryPrice))
        strategy.entry("Short", strategy.short)
        entryPrice := close
        entryTime := time
        positionSide := "short"

    // Long Entry Logic (Bullish Signal)
    if (bullishSignal and na(entryPrice))
        strategy.entry("Long", strategy.long)
        entryPrice := close
        entryTime := time
        positionSide := "long"

    // Exit Logic: Close on Opposing Signal (after the current signal is triggered)
    if (positionSide == "short" and bullishSignal )
        strategy.close("Short")
        entryPrice := na
        positionSide := ""

    if (positionSide == "long" and bearishSignal)
        strategy.close("Long")
        entryPrice := na
        positionSide := ""

    // Stop-Loss and Take-Profit Logic (in pips)
    stopLossPriceLong = entryPrice - stopLossPips * syminfo.mintick
    takeProfitPriceLong = entryPrice + takeProfitPips * syminfo.mintick
    stopLossPriceShort = entryPrice + stopLossPips * syminfo.mintick
    takeProfitPriceShort = entryPrice - takeProfitPips * syminfo.mintick

    // Long Stop-Loss and Take-Profit Conditions
    if (positionSide == "long" and close <= stopLossPriceLong)
        strategy.close("Long", comment="Stop Loss Triggered")
        entryPrice := na
        positionSide := ""

    if (positionSide == "long" and enableTakeProfit and close >= takeProfitPriceLong)
        strategy.close("Long", comment="Take Profit Triggered")
        entryPrice := na
        positionSide := ""

    // Short Stop-Loss and Take-Profit Conditions
    if (positionSide == "short" and close >= stopLossPriceShort)
        strategy.close("Short", comment="Stop Loss Triggered")
        entryPrice := na
        positionSide := ""

    if (positionSide == "short" and enableTakeProfit and close <= takeProfitPriceShort)
        strategy.close("Short", comment="Take Profit Triggered")
        entryPrice := na
        positionSide := ""

if (mode == "Bullish Only")
    if (bullishSignal and na(entryPrice))
        strategy.entry("Long", strategy.long)
        entryPrice := close
        entryTime := time
        positionSide := "long"

    if (positionSide == "long" and bearishSignal)
        strategy.close("Long")
        entryPrice := na
        positionSide := ""

    // Stop-Loss and Take-Profit Logic (in pips)
    stopLossPriceLong = entryPrice - stopLossPips * syminfo.mintick
    takeProfitPriceLong = entryPrice + takeProfitPips * syminfo.mintick

    if (positionSide == "long" and close <= stopLossPriceLong)
        strategy.close("Long", comment="Stop Loss Triggered")
        entryPrice := na
        positionSide := ""

    if (positionSide == "long" and enableTakeProfit and close >= takeProfitPriceLong)
        strategy.close("Long", comment="Take Profit Triggered")
        entryPrice := na
        positionSide := ""

if (mode == "Bearish Only")
    if (bearishSignal and na(entryPrice))
        strategy.entry("Short", strategy.short)
        entryPrice := close
        entryTime := time
        positionSide := "short"

    if (positionSide == "short" and bullishSignal)
        strategy.close("Short")
        entryPrice := na
        positionSide := ""

    // Stop-Loss and Take-Profit Logic (in pips)
    stopLossPriceShort = entryPrice + stopLossPips * syminfo.mintick
    takeProfitPriceShort = entryPrice - takeProfitPips * syminfo.mintick

    if (positionSide == "short" and close >= stopLossPriceShort)
        strategy.close("Short", comment="Stop Loss Triggered")
        entryPrice := na
        positionSide := ""

    if (positionSide == "short" and enableTakeProfit and close <= takeProfitPriceShort)
        strategy.close("Short", comment="Take Profit Triggered")
        entryPrice := na
        positionSide := ""
Detail
https://www.fmz.com/strategy/488536
Last Modified
2025-03-28 17:13:02