
7.9 KiB
Name
动态均线交叉趋势跟踪策略结合ATR风险管理系统-Dynamic-Moving-Average-Crossover-Trend-Following-Strategy-with-ATR-Risk-Management-System
Author
ChaoZhang
Strategy Description
[trans]
概述
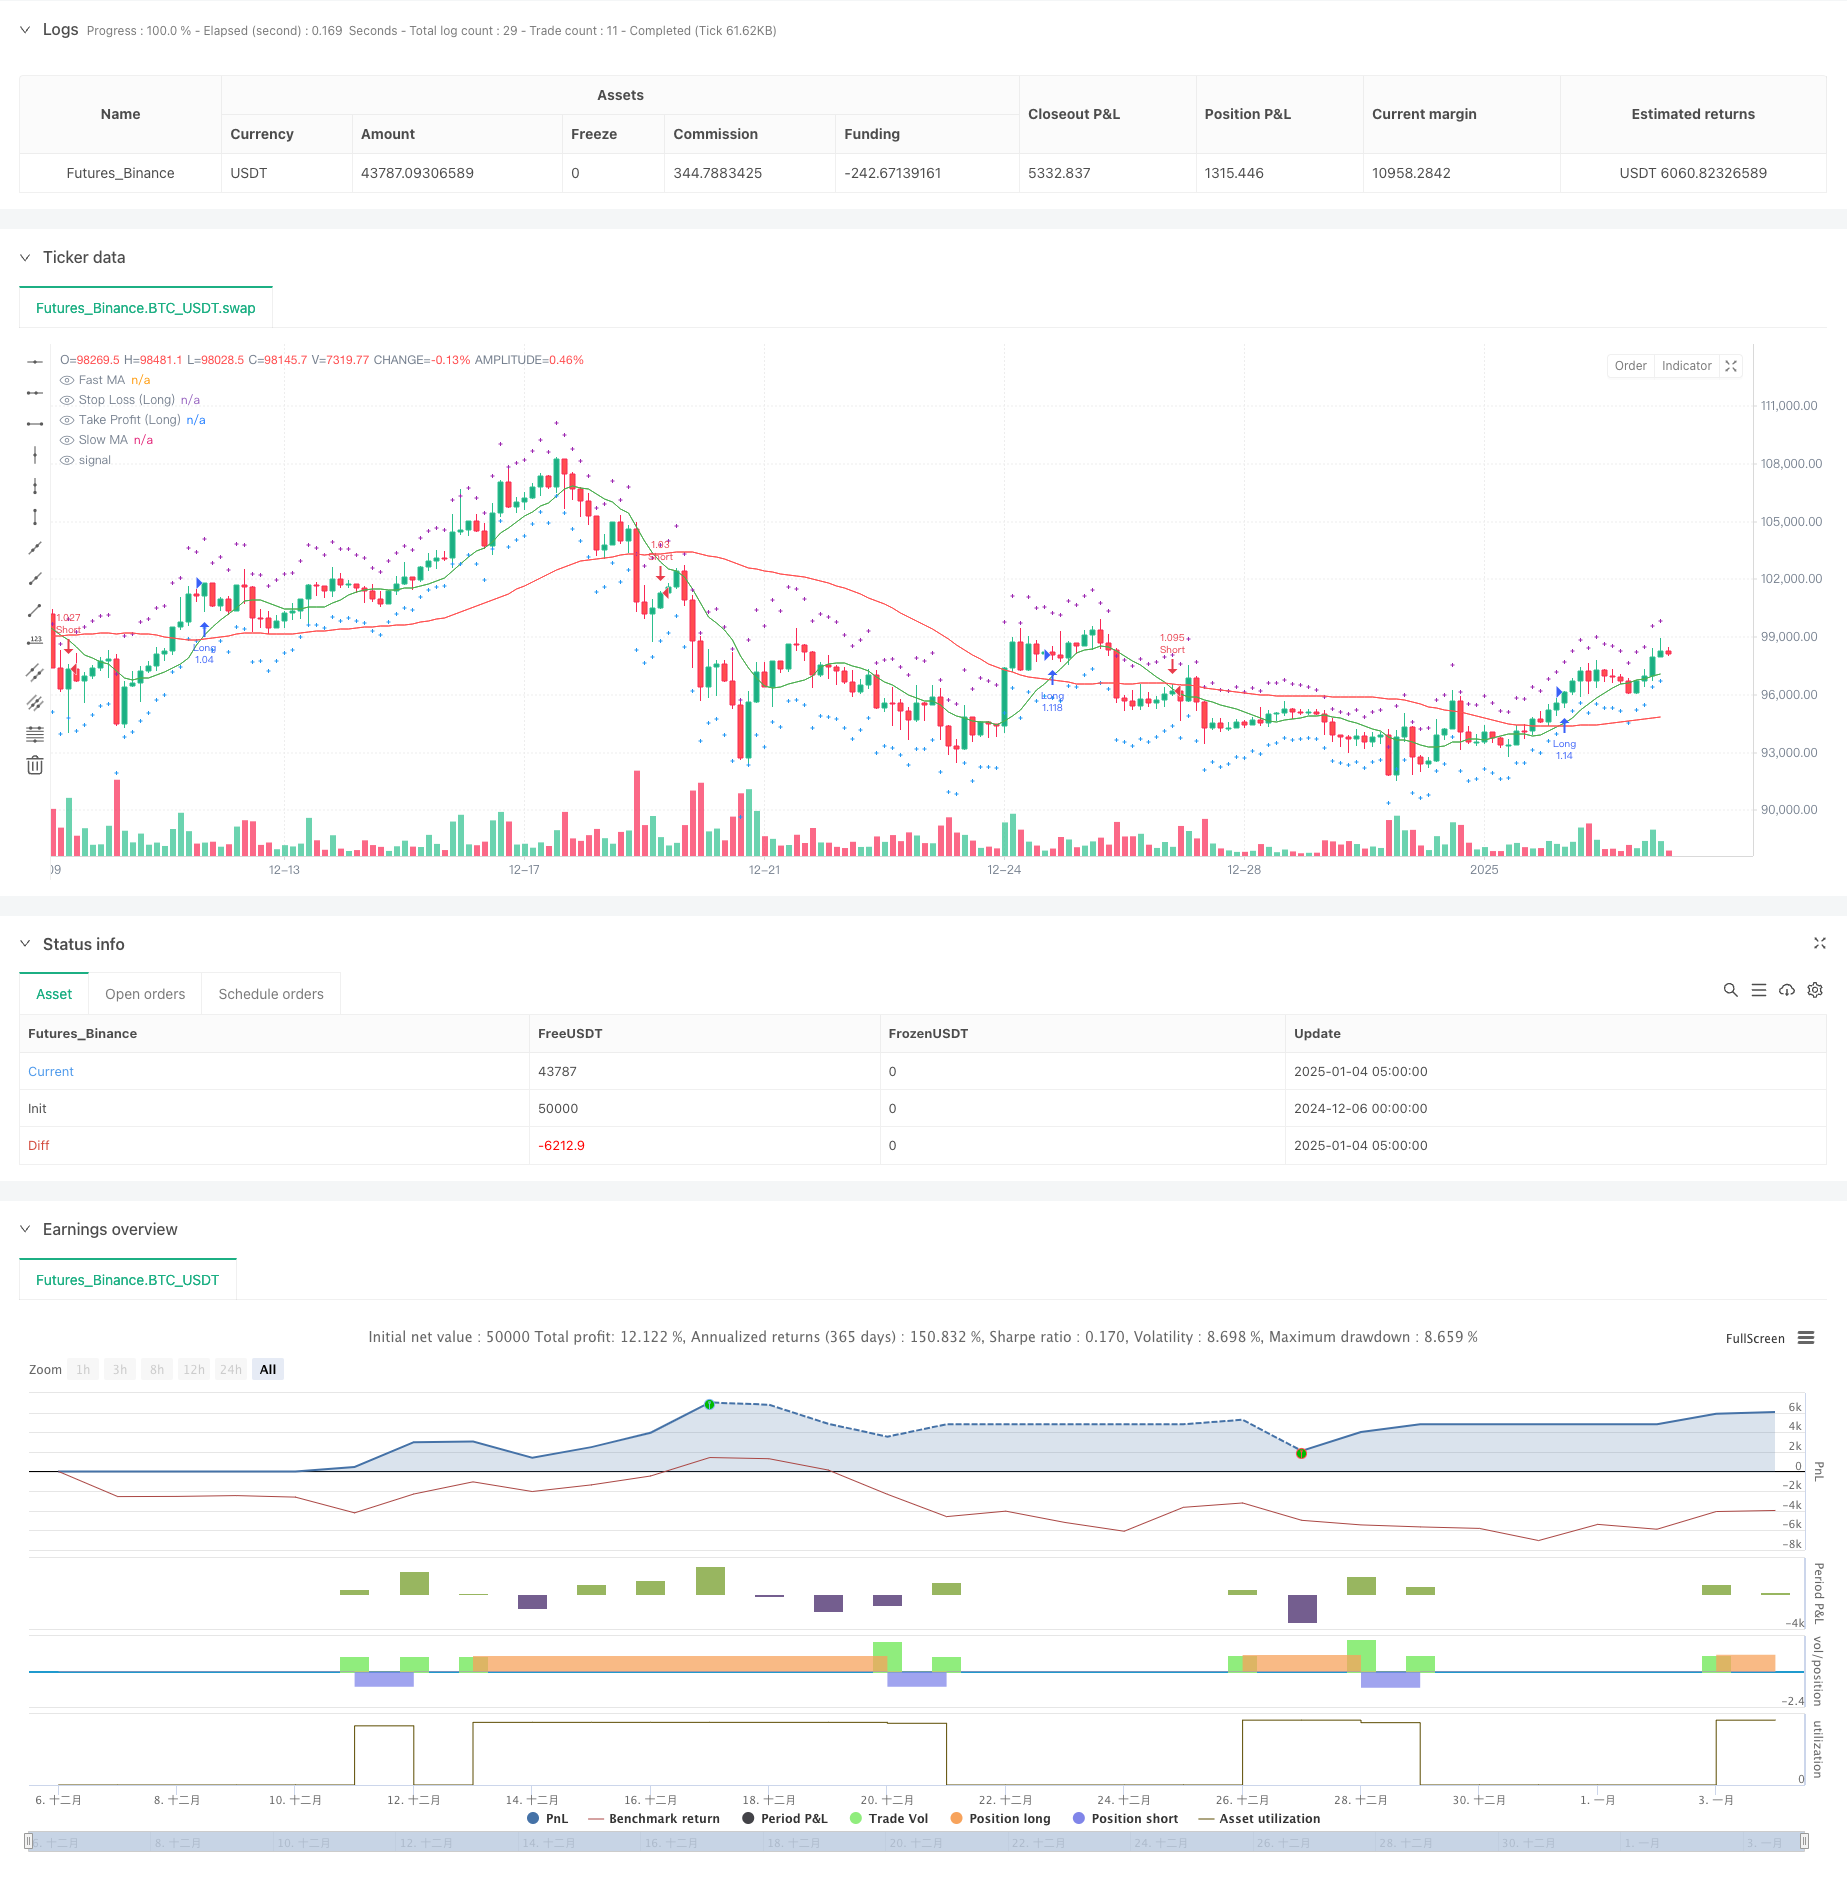
该策略是一个结合了均线交叉信号和ATR风险管理的趋势跟踪交易系统。策略通过快速与慢速移动平均线的交叉来捕捉市场趋势,同时利用ATR指标动态调整止损和获利水平,实现对交易风险的精确控制。该策略还包含了资金管理模块,可以根据账户权益和预设的风险参数自动调整仓位大小。
策略原理
策略的核心逻辑基于以下几个关键组件:
- 趋势识别系统 - 使用10周期和50周期的简单移动平均线(SMA)交叉来确定趋势方向。当快速均线上穿慢速均线时产生做多信号,下穿时产生做空信号。
- 风险管理系统 - 采用14周期ATR指标乘以1.5倍系数来设置动态止损和获利目标。这种方法可以根据市场波动性自动调整风险控制参数。
- 资金管理系统 - 通过设置风险容忍度(2%)和资金分配比例(100%)来控制每笔交易的资金使用量,确保资金使用的合理性。
策略优势
- 自适应性强 - 通过ATR动态调整止损和获利水平,使策略能够适应不同市场环境。
- 风险控制完善 - 结合了百分比风险控制和ATR动态止损,形成了双重风险防护机制。
- 操作规则明确 - 入场、出场条件清晰,便于执行和回测。
- 资金管理科学 - 通过比例分配机制,确保单笔交易风险可控。
策略风险
- 震荡市场风险 - 在横盘震荡市场中,均线交叉信号频繁,可能导致连续止损。
- 滑点风险 - 在市场快速波动时,实际成交价格可能与信号价格存在较大偏差。
- 资金效率风险 - 100%的资金分配比例可能导致资金使用效率不够灵活。
策略优化方向
- 增加趋势过滤器 - 可添加ADX等趋势强度指标,在强趋势时才执行交易。
- 优化均线参数 - 可通过历史数据测试,寻找最优的均线周期组合。
- 完善资金管理 - 建议增加动态持仓量调整机制,根据账户盈亏情况自动调整交易规模。
- 增加市场环境过滤 - 可添加波动率指标,在适合的市场环境下才进行交易。
总结
该策略通过均线交叉捕捉趋势,结合ATR动态风控,实现了一个完整的趋势跟踪交易系统。策略的优势在于其自适应性和风险控制能力,但在震荡市场中表现可能欠佳。通过添加趋势过滤器和优化资金管理系统,策略的整体表现还有提升空间。 ||
Overview
This strategy is a trend following trading system that combines moving average crossover signals with ATR-based risk management. It captures market trends through the crossover of fast and slow moving averages while using the ATR indicator to dynamically adjust stop-loss and take-profit levels, achieving precise control of trading risks. The strategy also includes a money management module that automatically adjusts position sizes based on account equity and preset risk parameters.
Strategy Principles
The core logic of the strategy is based on the following key components:
- Trend Identification System - Uses crossovers of 10-period and 50-period Simple Moving Averages (SMA) to determine trend direction. Long signals are generated when the fast MA crosses above the slow MA, and short signals when it crosses below.
- Risk Management System - Employs a 14-period ATR indicator multiplied by 1.5 to set dynamic stop-loss and take-profit targets. This method automatically adjusts risk control parameters based on market volatility.
- Money Management System - Controls the amount of capital used in each trade by setting risk tolerance (2%) and capital allocation (100%), ensuring rational use of funds.
Strategy Advantages
- Strong Adaptability - Dynamically adjusts stop-loss and take-profit levels through ATR, enabling the strategy to adapt to different market environments.
- Comprehensive Risk Control - Combines percentage-based risk control with dynamic ATR stops, forming a dual risk protection mechanism.
- Clear Operating Rules - Entry and exit conditions are clear, facilitating execution and backtesting.
- Scientific Money Management - Ensures controllable risk per trade through proportional allocation mechanism.
Strategy Risks
- Choppy Market Risk - In sideways markets, frequent MA crossovers may lead to consecutive losses.
- Slippage Risk - During rapid market movements, actual execution prices may significantly deviate from signal prices.
- Capital Efficiency Risk - 100% capital allocation may result in less flexible use of funds.
Strategy Optimization Directions
- Add Trend Filter - Can add trend strength indicators like ADX to execute trades only in strong trends.
- Optimize MA Parameters - Can test historical data to find optimal moving average period combinations.
- Improve Money Management - Recommend adding dynamic position sizing mechanism to automatically adjust trading size based on account performance.
- Add Market Environment Filter - Can add volatility indicators to trade only in suitable market conditions.
Summary
This strategy captures trends through MA crossovers and combines ATR dynamic risk control to create a complete trend following trading system. The strategy's strengths lie in its adaptability and risk control capabilities, though it may underperform in choppy markets. Through the addition of trend filters and optimization of the money management system, there is room for improvement in the strategy's overall performance.[/trans]
Source (PineScript)
/*backtest
start: 2024-12-06 00:00:00
end: 2025-01-04 08:00:00
period: 3h
basePeriod: 3h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © davisash666

//@version=5
strategy("Trend-Following Strategy", overlay=true)

// Inputs for strategy parameters
timeframe = input.timeframe("D", "Timeframe")
risk_tolerance = input.float(2.0, "Risk Tolerance (%)", step=0.1) / 100
capital_allocation = input.float(200, "Capital Allocation (%)", step=1) / 100

// Technical indicators (used to emulate machine learning)
ma_length_fast = input.int(10, "Fast MA Length")
ma_length_slow = input.int(50, "Slow MA Length")
atr_length = input.int(14, "ATR Length")
atr_multiplier = input.float(1.5, "ATR Multiplier")

// Calculations
fast_ma = ta.sma(close, ma_length_fast)
slow_ma = ta.sma(close, ma_length_slow)
atr = ta.atr(atr_length)

// Entry and exit conditions
long_condition = ta.crossover(fast_ma, slow_ma)
short_condition = ta.crossunder(fast_ma, slow_ma)

// Risk management
stop_loss_long = close - (atr * atr_multiplier)
stop_loss_short = close + (atr * atr_multiplier)
take_profit_long = close + (atr * atr_multiplier)
take_profit_short = close - (atr * atr_multiplier)

// Capital allocation
position_size = strategy.equity * capital_allocation

// Execute trades
if long_condition
    strategy.entry("Long", strategy.long, qty=position_size / close)
    strategy.exit("Take Profit/Stop Loss", "Long", stop=stop_loss_long, limit=take_profit_long)

if short_condition
    strategy.entry("Short", strategy.short, qty=position_size / close)
    strategy.exit("Take Profit/Stop Loss", "Short", stop=stop_loss_short, limit=take_profit_short)

// Plotting for visualization
plot(fast_ma, color=color.green, title="Fast MA")
plot(slow_ma, color=color.red, title="Slow MA")
plot(stop_loss_long, color=color.blue, title="Stop Loss (Long)", linewidth=1, style=plot.style_cross)
plot(take_profit_long, color=color.purple, title="Take Profit (Long)", linewidth=1, style=plot.style_cross)
Detail
https://www.fmz.com/strategy/477598
Last Modified
2025-01-06 16:27:18