
8.3 KiB
Name
三重EMA平滑动量与资金流量综合交易策略-Triple-EMA-Smoothed-Momentum-and-Money-Flow-Integrated-Trading-Strategy
Author
ianzeng123
Strategy Description
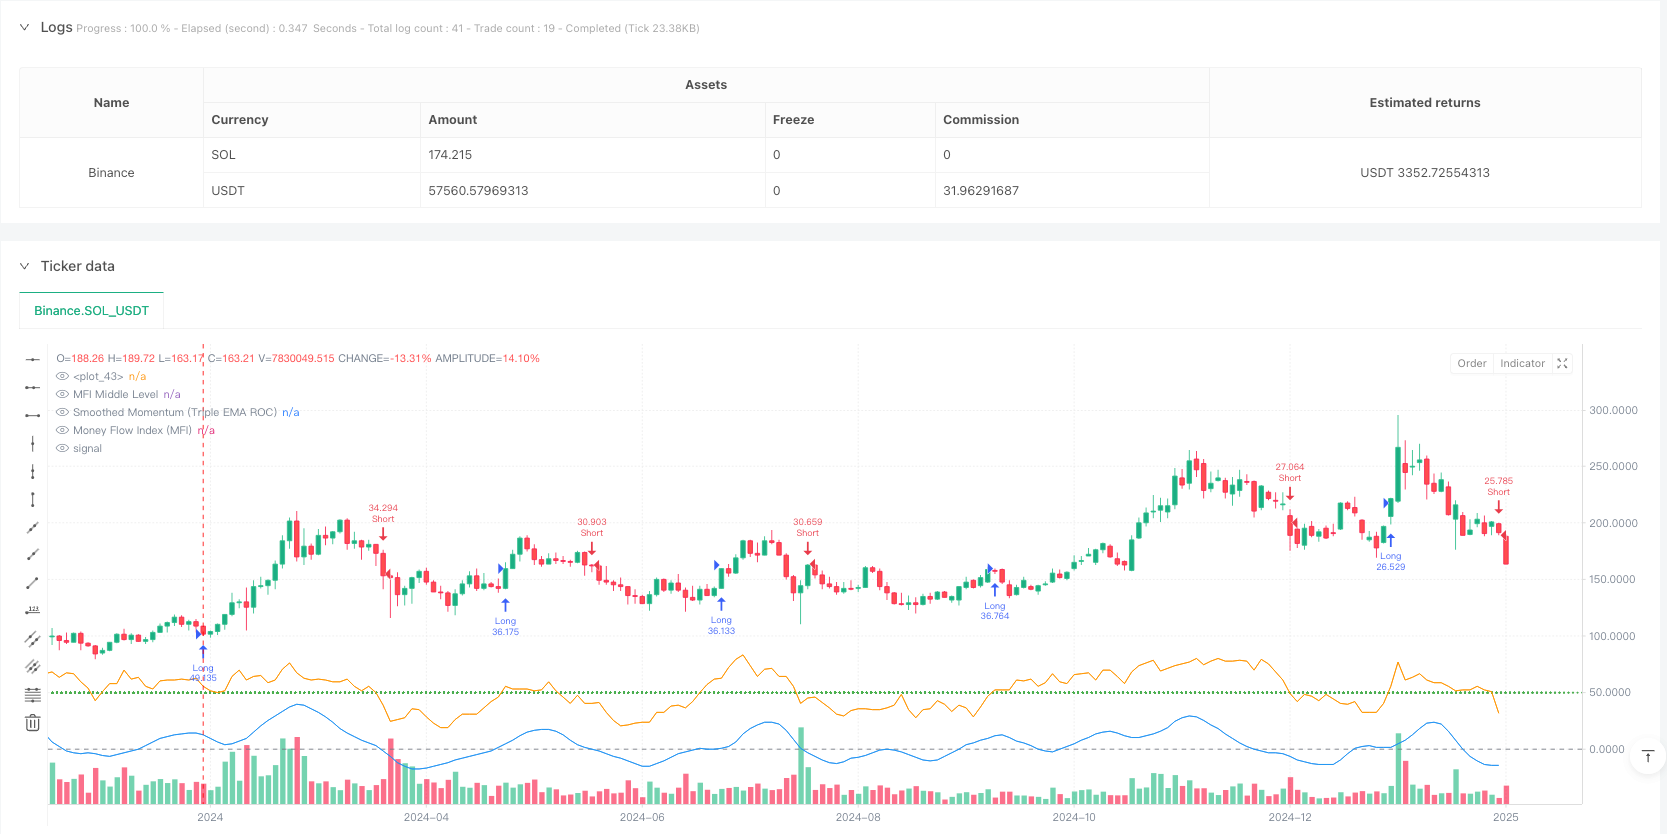
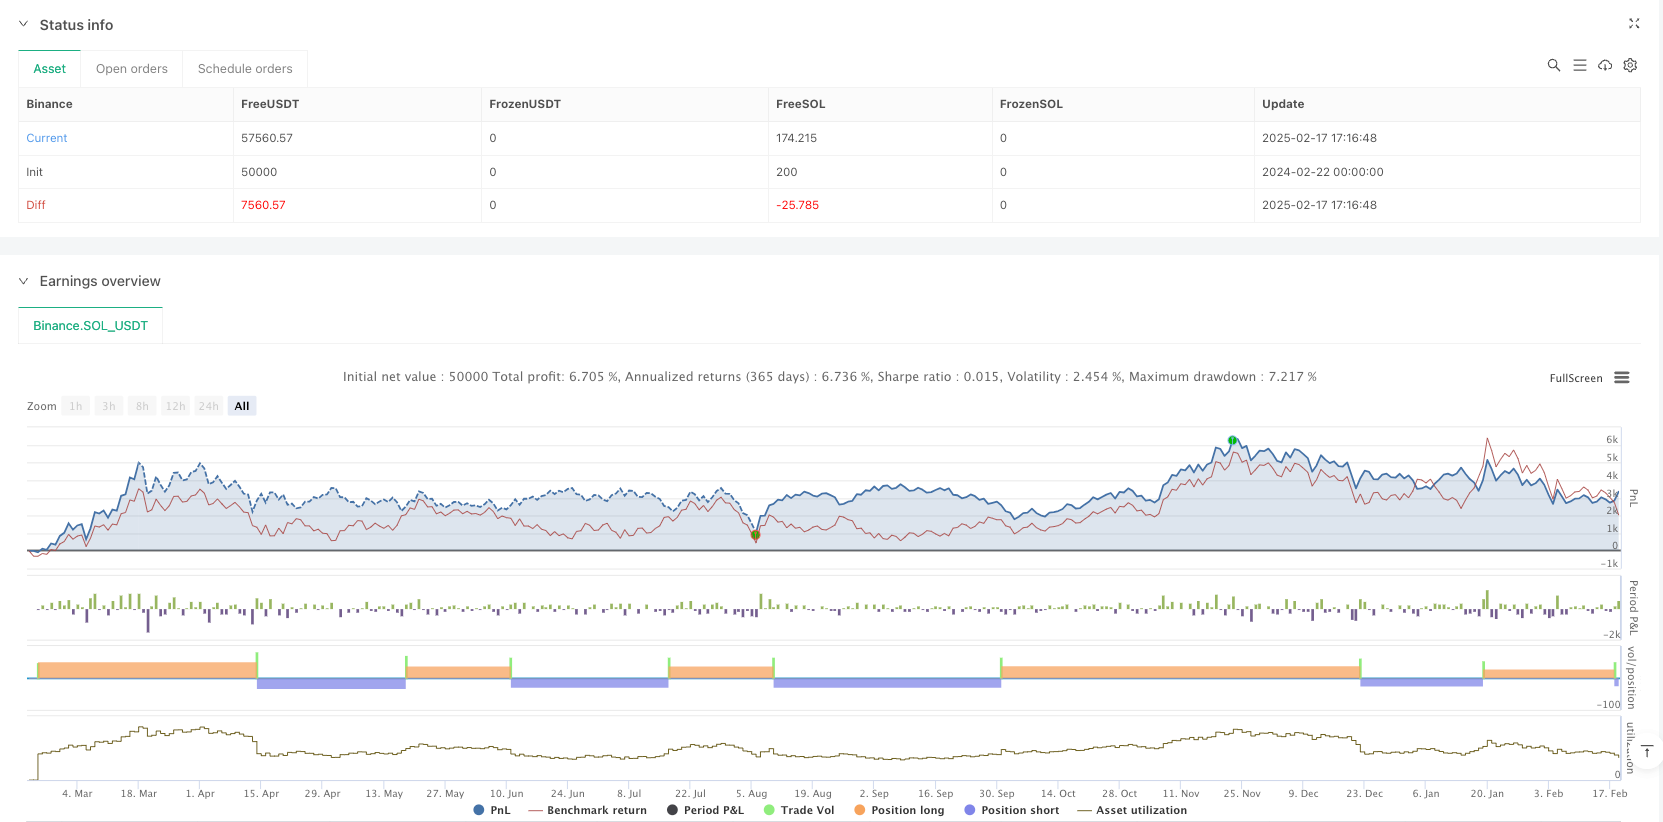
[trans]
概述
该策略是一个结合动量指标和资金流量指标的综合交易系统,通过三重指数移动平均线(EMA)对动量指标进行平滑处理,有效降低了市场噪音。策略使用变化率(ROC)计算原始动量,并结合货币流量指标(MFI)来确认交易信号,可以适用于各种时间周期的交易。
策略原理
策略的核心原理基于两个主要技术指标:动量指标和资金流量指标(MFI)。首先使用ROC计算原始动量,然后通过三重EMA平滑处理获得更稳定的动量信号线。交易信号的产生需要同时满足动量和MFI的条件:当平滑后的动量为正且MFI高于中位水平时产生做多信号;当平滑后的动量为负且MFI低于中位水平时产生做空信号。策略还设计了基于动量和MFI拐点的退出机制,有助于及时止损和锁定利润。
策略优势
- 信号平滑性强: 通过三重EMA处理显著减少了虚假信号,提高了交易的可靠性
- 双重确认机制: 结合动量和资金流量两个维度,降低了单一指标的局限性
- 适应性广: 可以应用于不同的时间周期,具有较强的普适性
- 风险控制完善: 设有明确的入场和出场条件,包含止损机制
- 参数可调整性强: 提供多个可调参数,便于根据不同市场情况进行优化
策略风险
- 趋势转折风险: 在剧烈波动市场中可能出现信号滞后
- 参数敏感性: 不同参数设置可能导致策略表现差异较大
- 市场环境依赖: 在横盘市场中可能产生频繁的虚假信号
- 资金管理风险: 需要合理设置仓位规模以控制风险
- 技术指标局限: 基于技术指标的策略在基本面变化时可能失效
策略优化方向
- 引入波动率过滤器: 增加ATR指标来过滤低波动期的信号
- 优化退出机制: 增加移动止损和利润目标
- 增加时间过滤: 避开重要经济数据发布时段
- 加入成交量确认: 结合成交量分析提高信号可靠性
- 开发自适应参数: 根据市场状态动态调整参数
总结
这是一个设计合理、逻辑清晰的综合交易策略。通过动量和资金流量指标的结合,以及三重EMA平滑处理,有效平衡了信号的及时性和可靠性。策略具有较强的实用性和可扩展性,适合进一步优化和实盘应用。建议交易者在实际应用中注意风险控制,合理设置参数,并根据具体市场情况进行优化调整。 ||
Overview
This strategy is an integrated trading system that combines momentum indicators and money flow indicators, using triple exponential moving averages (EMA) to smooth the momentum indicator, effectively reducing market noise. The strategy uses Rate of Change (ROC) to calculate raw momentum and combines it with the Money Flow Index (MFI) to confirm trading signals, applicable to various timeframes.
Strategy Principles
The core principles are based on two main technical indicators: momentum and Money Flow Index (MFI). First, ROC calculates raw momentum, which is then smoothed through triple EMA processing to obtain a more stable momentum signal line. Trading signals require simultaneous satisfaction of momentum and MFI conditions: long signals are generated when smoothed momentum is positive and MFI is above the middle level; short signals are generated when smoothed momentum is negative and MFI is below the middle level. The strategy also incorporates exit mechanisms based on momentum and MFI turning points, helping to implement timely stop-losses and lock in profits.
Strategy Advantages
- Strong Signal Smoothing: Triple EMA processing significantly reduces false signals, improving trading reliability
- Dual Confirmation Mechanism: Combines momentum and money flow dimensions, reducing limitations of single indicators
- Wide Adaptability: Applicable to different timeframes with strong universality
- Comprehensive Risk Control: Clear entry and exit conditions, including stop-loss mechanisms
- Strong Parameter Adjustability: Provides multiple adjustable parameters for optimization across different market conditions
Strategy Risks
- Trend Reversal Risk: Potential signal lag in volatile markets
- Parameter Sensitivity: Different parameter settings may lead to significant performance variations
- Market Environment Dependency: May generate frequent false signals in sideways markets
- Money Management Risk: Requires proper position sizing for risk control
- Technical Indicator Limitations: Strategy based on technical indicators may fail during fundamental changes
Strategy Optimization Directions
- Introduce Volatility Filter: Add ATR indicator to filter signals during low volatility periods
- Optimize Exit Mechanism: Add trailing stops and profit targets
- Add Time Filters: Avoid important economic data release periods
- Incorporate Volume Confirmation: Combine volume analysis to improve signal reliability
- Develop Adaptive Parameters: Dynamically adjust parameters based on market conditions
Summary
This is a well-designed trading strategy with clear logic. Through the combination of momentum and money flow indicators, along with triple EMA smoothing, it effectively balances signal timeliness and reliability. The strategy demonstrates strong practicality and scalability, suitable for further optimization and live trading application. Traders are advised to pay attention to risk control, set parameters reasonably, and optimize according to specific market conditions when implementing the strategy.[/trans]
Source (PineScript)
/*backtest
start: 2024-02-22 00:00:00
end: 2025-02-19 08:00:00
period: 2d
basePeriod: 2d
exchanges: [{"eid":"Binance","currency":"SOL_USDT"}]
*/

//@version=5
strategy("Momentum & Money Flow Strategy with Triple EMA Smoothing", overlay=true, initial_capital=100000, default_qty_type=strategy.percent_of_equity, default_qty_value=10)

// Input parameters
momentumPeriod  = input.int(7, title="Momentum Period", minval=1)
smoothingPeriod = input.int(3, title="Momentum Smoothing Period", minval=1)
mfiPeriod       = input.int(14, title="MFI Period", minval=1)
mfiMiddleLevel  = input.int(50, title="MFI Middle Level", minval=1, maxval=100)
mfiOverbought   = input.int(80, title="MFI Overbought Level", minval=1, maxval=100)
mfiOversold     = input.int(20, title="MFI Oversold Level", minval=1, maxval=100)

// Calculate raw momentum oscillator using rate-of-change (ROC)
rawMomentum = ta.roc(close, momentumPeriod)
// Apply triple EMA smoothing for a much smoother momentum line
smoothedMomentum = ta.ema(ta.ema(ta.ema(rawMomentum, smoothingPeriod), smoothingPeriod), smoothingPeriod)

// Calculate Money Flow Index (MFI) using the typical price (hlc3)
typicalPrice = hlc3
mfiValue     = ta.mfi(typicalPrice, mfiPeriod)

// Define conditions for filtering signals based on smoothed momentum and MFI
longCondition  = (smoothedMomentum > 0) and (mfiValue > mfiMiddleLevel)
shortCondition = (smoothedMomentum < 0) and (mfiValue < mfiMiddleLevel)

// Define exit conditions for capturing turning points
exitLongCondition  = (smoothedMomentum < 0) and (mfiValue < mfiOversold)
exitShortCondition = (smoothedMomentum > 0) and (mfiValue > mfiOverbought)

// Execute entries based on defined conditions
if (longCondition and strategy.position_size <= 0)
    strategy.entry("Long", strategy.long)
if (shortCondition and strategy.position_size >= 0)
    strategy.entry("Short", strategy.short)

// Exit positions based on turning point conditions
if (strategy.position_size > 0 and exitLongCondition)
    strategy.close("Long")
if (strategy.position_size < 0 and exitShortCondition)
    strategy.close("Short")

// Plot the triple EMA smoothed momentum oscillator and MFI for visual reference
plot(smoothedMomentum, title="Smoothed Momentum (Triple EMA ROC)", color=color.blue)
hline(0, color=color.gray)
plot(mfiValue, title="Money Flow Index (MFI)", color=color.orange)
hline(mfiMiddleLevel, color=color.green, linestyle=hline.style_dotted, title="MFI Middle Level")
Detail
https://www.fmz.com/strategy/483094
Last Modified
2025-02-21 13:25:57