
8.6 KiB
Name
三重均线趋势追踪多指标组合量化交易策略-Triple-EMA-Trend-Following-Multi-Indicator-Quantitative-Trading-Strategy
Author
ChaoZhang
Strategy Description
[trans]
概述
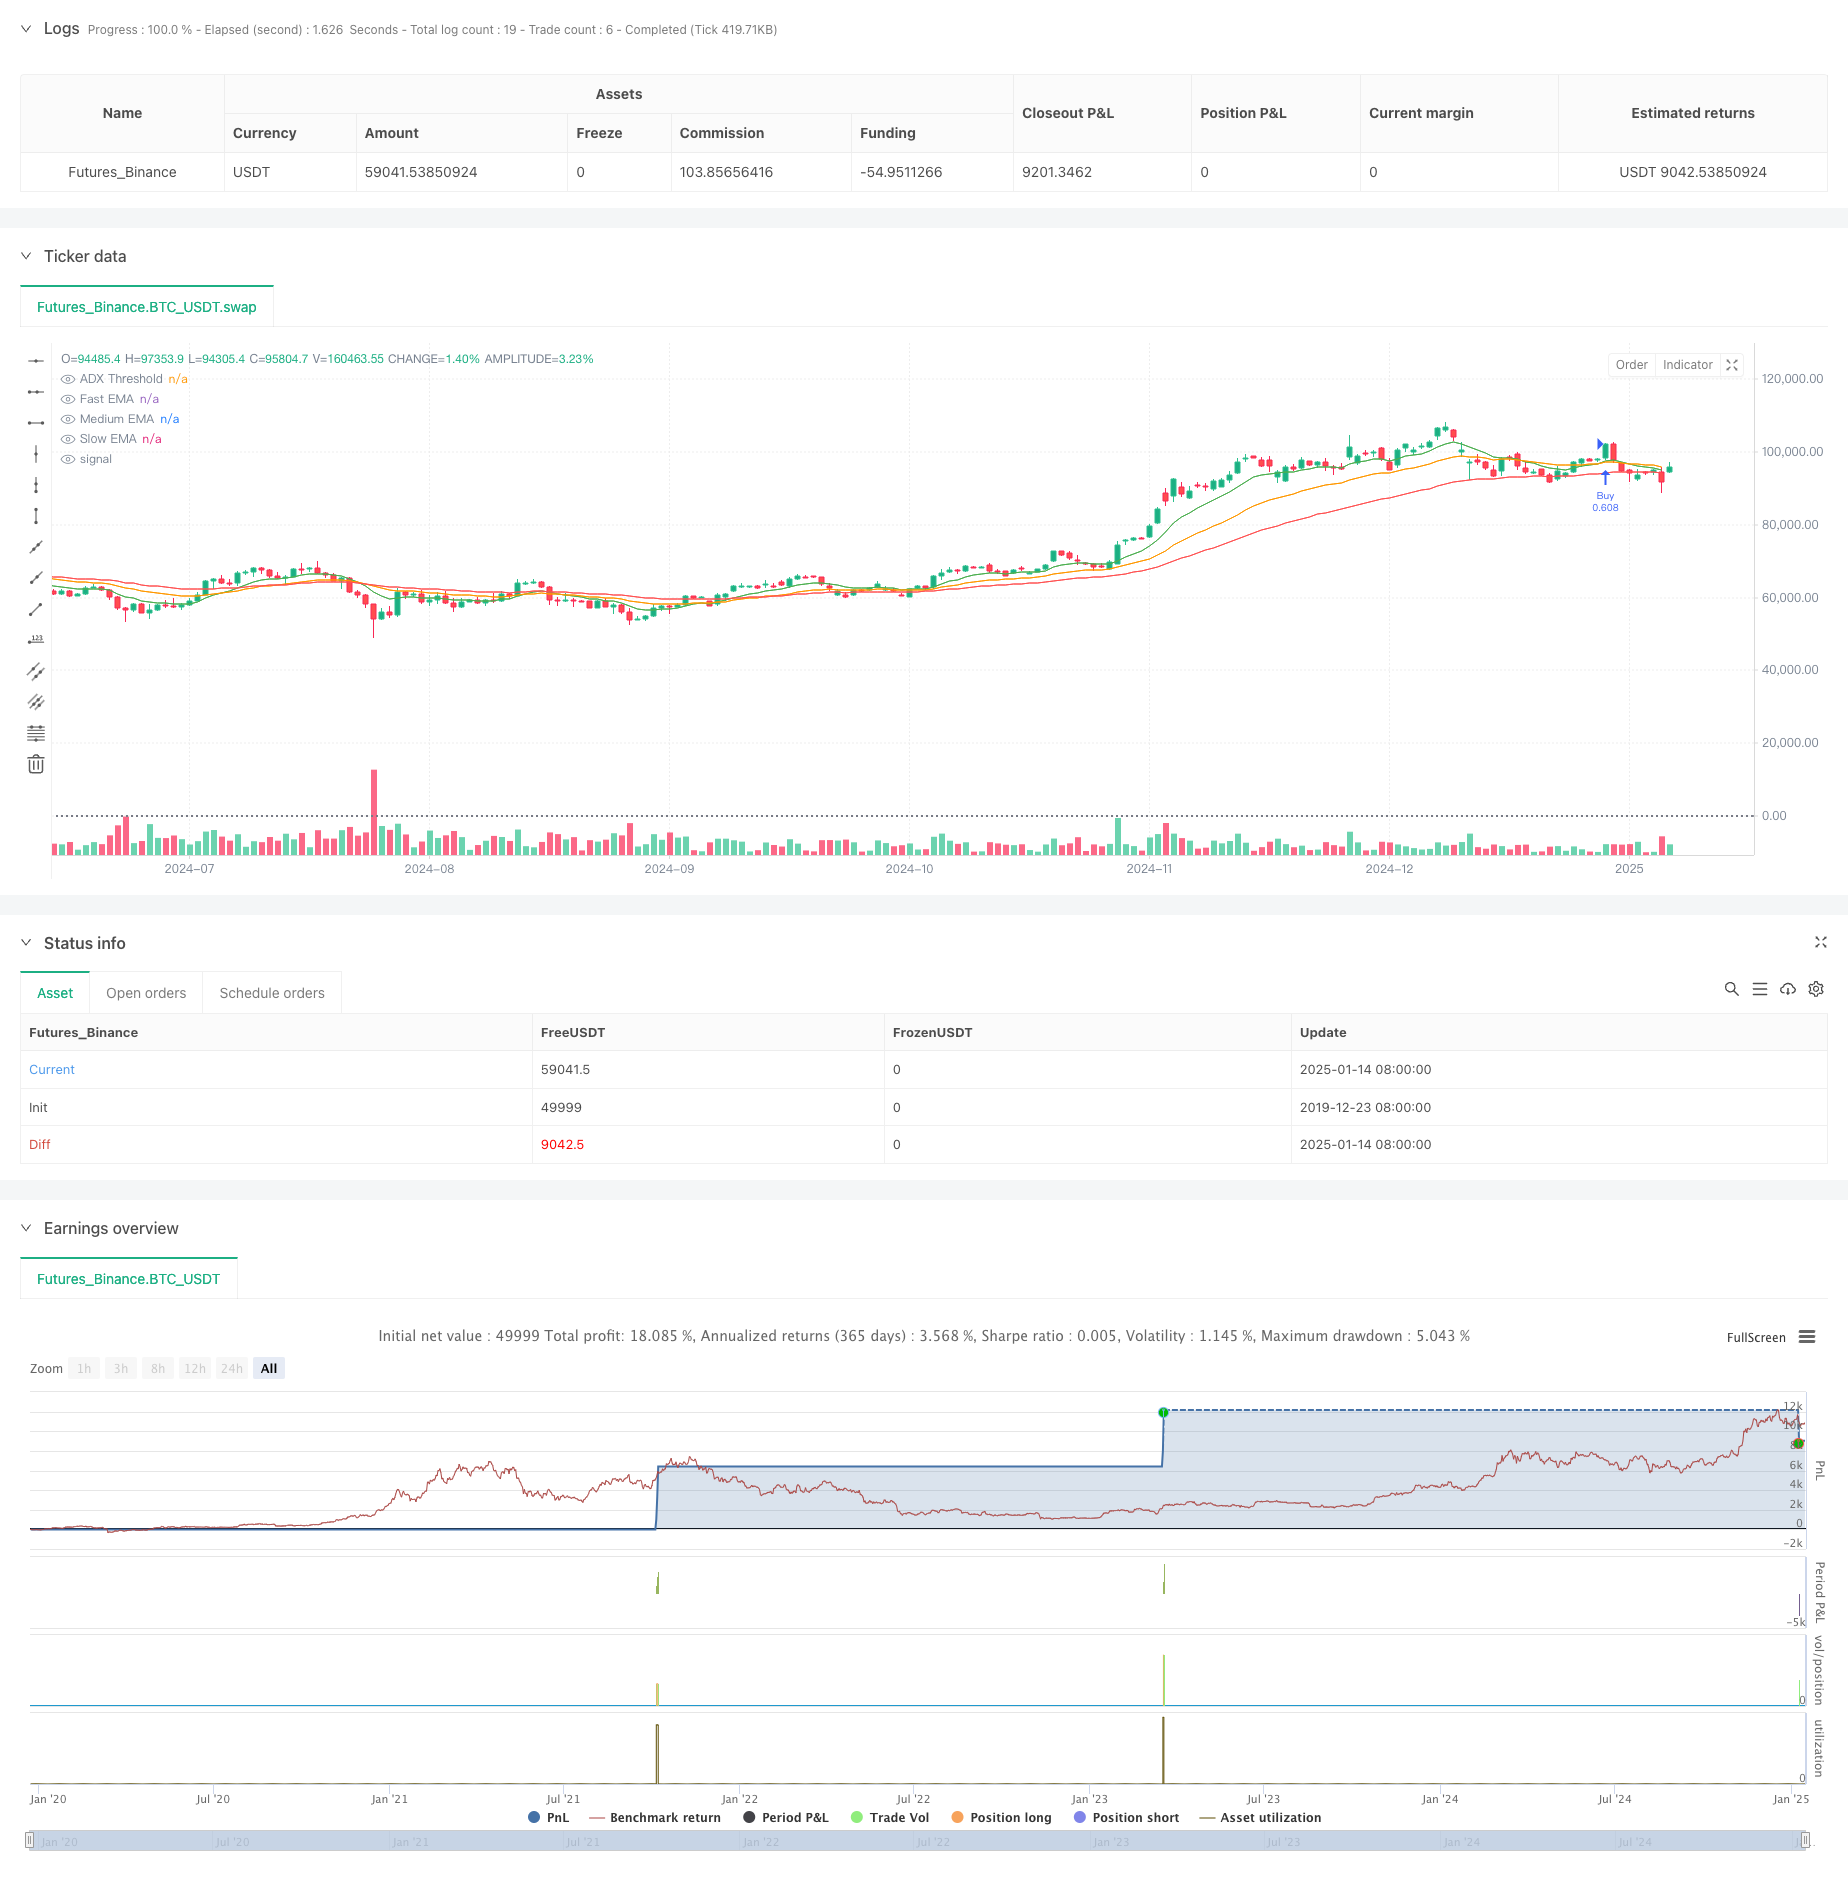
该策略是一个基于多重技术指标的趋势跟踪系统,结合了移动平均线(EMA)、动向指标(DMI)、去趋势价格震荡指标(DPO)、相对强弱指数(RSI)和平均真实波幅(ATR)等多个技术指标,通过多重信号确认来识别强劲趋势并进行交易。策略设计的核心思想是在确认趋势方向、动量和波动性等多个市场特征后才进行交易,以提高交易的成功率。
策略原理
策略采用三重指数移动平均线(EMA)作为核心趋势判断系统,结合其他技术指标进行多重信号确认:
- 快速EMA(10日)用于捕捉短期价格动量
- 中期EMA(25日)作为中期趋势过滤器
- 慢速EMA(50日)定义整体趋势方向
- DMI(14日)用于确认趋势的方向强度
- DPO用于确认价格偏离趋势的程度
- RSI(14日)用于衡量动量和超买超卖状态
- ATR(14日)用于设置止损和获利目标
交易信号触发条件:
- 做多条件:快线上穿中线且均在慢线之上,ADX>25,RSI>50,DPO>0
- 做空条件:快线下穿中线且均在慢线之下,ADX>25,RSI<50,DPO<0
策略优势
- 多重信号确认提高了交易的可靠性,降低了虚假信号的风险
- 结合趋势跟踪和动量特征,能够有效捕捉强劲趋势
- 通过ATR动态调整止损和获利目标,适应市场波动性变化
- 系统化的风险管理机制,每笔交易风险控制在账户的2%以内
- 策略逻辑清晰,各个组件功能明确,便于调试和优化
策略风险
- 在震荡市场中可能产生频繁的假突破信号
- 多重指标确认可能导致入场信号滞后
- 固定的ADX阈值可能在不同市场环境下表现不一致
- 在快速反转行情中可能面临较大回撤
- 参数优化可能导致过度拟合历史数据
风险控制措施:
- 使用ATR动态止损来适应市场波动
- 实施固定比例风险管理
- 多重指标交叉确认减少假信号
策略优化方向
- 引入自适应参数机制,根据市场环境动态调整指标参数
- 增加市场环境识别模块,在不同市场条件下使用不同的交易规则
- 优化出场机制,考虑加入趋势反转信号和部分止盈
- 引入交易量分析,提高信号可靠性
- 开发回撤控制机制,在连续亏损时降低仓位或暂停交易
总结
该策略通过多重技术指标的组合应用,构建了一个完整的趋势跟踪交易系统。策略的主要特点是信号确认严格、风险控制合理,适合在日线级别上跟踪中长期趋势。虽然存在一定的滞后性,但通过严格的风险控制和多重信号确认,策略整体表现稳健。建议在实盘应用时注意市场环境的选择,并根据具体品种特性进行参数优化。
||
Overview
This strategy is a trend following system based on multiple technical indicators, combining Moving Averages (EMA), Directional Movement Index (DMI), Detrended Price Oscillator (DPO), Relative Strength Index (RSI), and Average True Range (ATR). The core concept is to execute trades only after confirming multiple market characteristics including trend direction, momentum, and volatility to improve trading success rate.
Strategy Principles
The strategy employs a Triple Exponential Moving Average (EMA) system as its core trend identification mechanism, combined with other technical indicators for multiple signal confirmation:
- Fast EMA (10-day) captures short-term price momentum
- Medium EMA (25-day) serves as a medium-term trend filter
- Slow EMA (50-day) defines the overall trend direction
- DMI (14-day) confirms trend directional strength
- DPO confirms price deviation from trend
- RSI (14-day) measures momentum and overbought/oversold conditions
- ATR (14-day) sets stop-loss and profit targets
Trade Signal Conditions:
- Long: Fast EMA crosses above Medium EMA with both above Slow EMA, ADX>25, RSI>50, DPO>0
- Short: Fast EMA crosses below Medium EMA with both below Slow EMA, ADX>25, RSI<50, DPO<0
Strategy Advantages
- Multiple signal confirmation improves reliability and reduces false signals
- Combines trend following and momentum characteristics for effective trend capture
- Dynamic adjustment of stops and targets through ATR adapts to market volatility
- Systematic risk management limits each trade risk to 2% of account
- Clear strategy logic with well-defined component functions facilitates debugging and optimization
Strategy Risks
- May generate frequent false breakout signals in ranging markets
- Multiple indicator confirmation can lead to delayed entries
- Fixed ADX threshold may perform inconsistently across different market conditions
- Potentially significant drawdowns during quick market reversals
- Parameter optimization risks overfitting to historical data
Risk Control Measures:
- Dynamic ATR-based stops adapt to market volatility
- Fixed proportion risk management
- Multiple indicator cross-confirmation reduces false signals
Strategy Optimization Directions
- Introduce adaptive parameter mechanisms to dynamically adjust indicator parameters based on market conditions
- Add market environment recognition module to apply different trading rules in different market conditions
- Optimize exit mechanism by incorporating trend reversal signals and partial profit-taking
- Incorporate volume analysis to improve signal reliability
- Develop drawdown control mechanism to reduce position size or pause trading during consecutive losses
Summary
This strategy constructs a complete trend following trading system through the combination of multiple technical indicators. Its main features are strict signal confirmation and reasonable risk control, suitable for tracking medium to long-term trends on daily timeframes. While there is some lag in signals, the strategy demonstrates robust overall performance through strict risk control and multiple signal confirmation. When applying to live trading, careful consideration should be given to market environment selection and parameter optimization for specific instruments. [/trans]
Source (PineScript)
/*backtest
start: 2019-12-23 08:00:00
end: 2025-01-15 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT","balance":49999}]
*/

//@version=5
strategy("Daily Strategy with Triple EMA, DMI, DPO, RSI, and ATR", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

// Input parameters
fastEmaLength = input.int(10, title="Fast EMA Length")
mediumEmaLength = input.int(25, title="Medium EMA Length")
slowEmaLength = input.int(50, title="Slow EMA Length")
dmiLength = input.int(14, title="DMI Length")
adxSmoothing = input.int(14, title="ADX Smoothing")
dpoLength = input.int(14, title="DPO Length")
rsiLength = input.int(14, title="RSI Length")
atrLength = input.int(14, title="ATR Length")
riskPercentage = input.float(2.0, title="Risk Percentage", step=0.1)
atrMultiplier = input.float(1.5, title="ATR Multiplier for Stop Loss", step=0.1)
tpMultiplier = input.float(2.0, title="ATR Multiplier for Take Profit", step=0.1)

// Calculate EMAs
fastEma = ta.ema(close, fastEmaLength)
mediumEma = ta.ema(close, mediumEmaLength)
slowEma = ta.ema(close, slowEmaLength)

// Calculate other indicators
[adx, diPlus, diMinus] = ta.dmi(dmiLength, adxSmoothing)
dpo = close - ta.sma(close, dpoLength)
rsi = ta.rsi(close, rsiLength)
atr = ta.atr(atrLength)

// Trading logic
longCondition = ta.crossover(fastEma, mediumEma) and fastEma > slowEma and mediumEma > slowEma and adx > 25 and rsi > 50 and dpo > 0
shortCondition = ta.crossunder(fastEma, mediumEma) and fastEma < slowEma and mediumEma < slowEma and adx > 25 and rsi < 50 and dpo < 0

// Risk management
riskAmount = (strategy.equity * riskPercentage) / 100
stopLoss = atr * atrMultiplier
takeProfit = atr * tpMultiplier

// Entry and exit logic
if (longCondition)
    strategy.entry("Buy", strategy.long)
    strategy.exit("Exit Long", "Buy", stop=close - stopLoss, limit=close + takeProfit)

if (shortCondition)
    strategy.entry("Sell", strategy.short)
    strategy.exit("Exit Short", "Sell", stop=close + stopLoss, limit=close - takeProfit)

// Plot indicators
plot(fastEma, color=color.green, title="Fast EMA")
plot(mediumEma, color=color.orange, title="Medium EMA")
plot(slowEma, color=color.red, title="Slow EMA")
hline(25, "ADX Threshold", color=color.gray, linestyle=hline.style_dotted)
Detail
https://www.fmz.com/strategy/478706
Last Modified
2025-01-17 14:57:26