235 lines
12 KiB
Markdown
235 lines
12 KiB
Markdown

|
|
||
|
|
> Name
|
||
|
|
|
||
|
|
开盘收盘均线交叉结合ADX动态指标的量化交易策略-Opening-and-Closing-Moving-Average-Crossover-Strategy-with-ADX-Dynamic-Indicator
|
||
|
|
|
||
|
|
> Author
|
||
|
|
|
||
|
|
ChaoZhang
|
||
|
|
|
||
|
|
> Strategy Description
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
[trans]
|
||
|
|
#### 概述
|
||
|
|
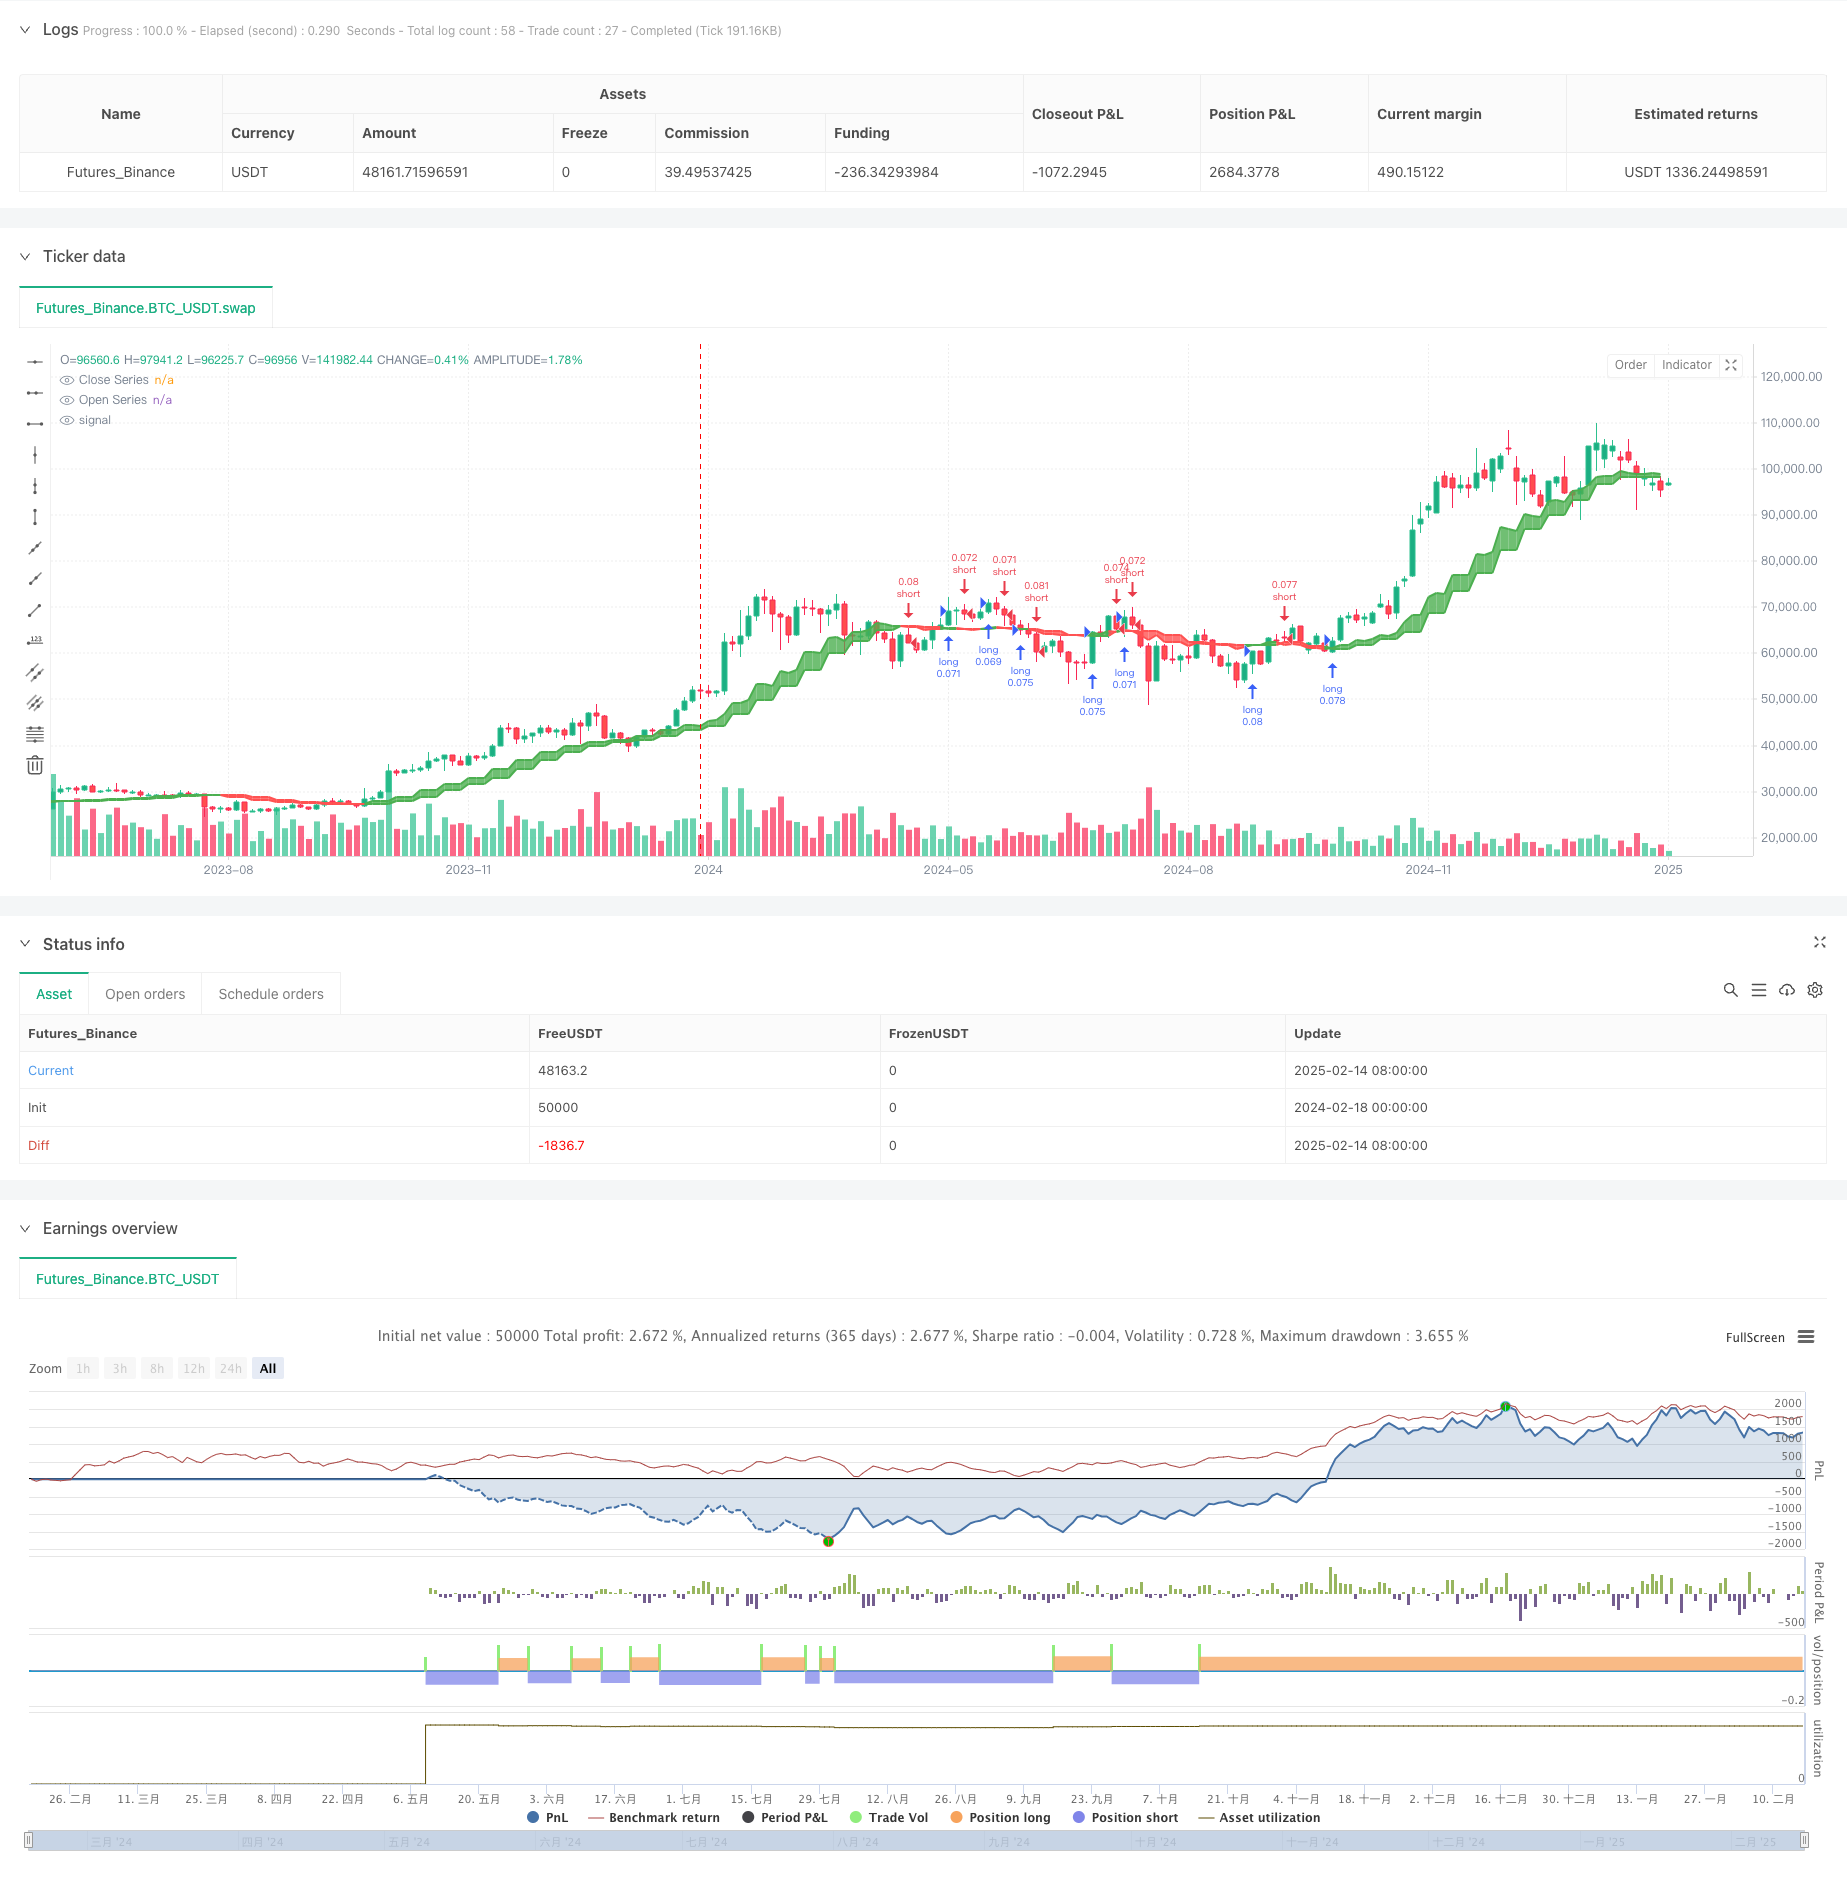
这是一个基于开盘价和收盘价移动均线交叉,并结合平均趋向指标(ADX)作为过滤器的量化交易策略。该策略采用多种移动均线类型,包括SMMA、EMA、DEMA等,通过识别均线交叉点来捕捉市场趋势变化,同时使用ADX指标来确认趋势强度,提高交易的可靠性。
|
||
|
|
|
||
|
|
#### 策略原理
|
||
|
|
策略的核心逻辑是通过计算开盘价和收盘价的移动均线,当收盘价均线向上穿越开盘价均线且ADX值大于设定阈值时,产生做多信号;当收盘价均线向下穿越开盘价均线且ADX值大于设定阈值时,产生做空信号。策略支持多种移动均线计算方法,包括简单移动均线(SMA)、指数移动均线(EMA)、双重指数移动均线(DEMA)等,可根据不同市场特征选择最适合的均线类型。
|
||
|
|
|
||
|
|
#### 策略优势
|
||
|
|
1. 灵活性强:支持多种移动均线类型,可以根据不同市场环境选择最优的均线计算方法
|
||
|
|
2. 趋势确认:通过ADX指标过滤,能有效降低震荡市场下的虚假信号
|
||
|
|
3. 风险控制完善:包含止损和止盈功能,可以有效控制每笔交易的风险
|
||
|
|
4. 可定制性高:提供多个参数接口,包括均线周期、ADX阈值、交易方向等,便于策略优化
|
||
|
|
5. 支持多时间周期:可以在不同的时间周期上运行,适应不同的交易风格
|
||
|
|
|
||
|
|
#### 策略风险
|
||
|
|
1. 均线滞后性:移动均线本质上是滞后指标,在快速波动的市场中可能产生滞后信号
|
||
|
|
2. 假突破风险:市场震荡时可能出现均线假突破,虽然有ADX过滤但仍需注意
|
||
|
|
3. 参数敏感性:策略效果对参数设置较为敏感,不同市场环境下需要适当调整
|
||
|
|
4. 市场适应性:在趋势明显的市场表现较好,但在震荡市场中可能频繁交易
|
||
|
|
5. 计算复杂性:多种均线类型的计算可能增加系统负担,需要注意运行效率
|
||
|
|
|
||
|
|
#### 策略优化方向
|
||
|
|
1. 引入成交量指标:可以结合成交量变化来确认趋势的有效性
|
||
|
|
2. 优化ADX参数:根据不同市场周期动态调整ADX阈值
|
||
|
|
3. 增加趋势确认指标:可以考虑添加其他趋势指标来提高信号可靠性
|
||
|
|
4. 完善止损机制:引入追踪止损或波动率自适应止损
|
||
|
|
5. 优化交易时机:考虑市场波动率和流动性因素,选择最佳交易时间
|
||
|
|
|
||
|
|
#### 总结
|
||
|
|
这是一个将经典的均线交叉策略与ADX指标相结合的量化交易系统。通过多种均线类型的支持和ADX趋势确认,能够较好地把握市场趋势,同时具备完善的风险控制机制。策略的可定制性强,可以根据不同市场环境进行优化调整。虽然存在一些固有的风险,但通过合理的参数设置和持续优化,该策略具有良好的实用价值。 ||
|
||
|
|
|
||
|
|
#### Overview
|
||
|
|
This is a quantitative trading strategy based on the crossover of opening and closing price moving averages, combined with the Average Directional Index (ADX) as a filter. The strategy employs various types of moving averages, including SMMA, EMA, DEMA, etc., to capture market trend changes by identifying crossover points while using the ADX indicator to confirm trend strength and improve trading reliability.
|
||
|
|
|
||
|
|
#### Strategy Principle
|
||
|
|
The core logic of the strategy is to calculate moving averages of opening and closing prices. A long signal is generated when the closing price MA crosses above the opening price MA and the ADX value exceeds the set threshold. Conversely, a short signal is generated when the closing price MA crosses below the opening price MA and the ADX value exceeds the threshold. The strategy supports multiple moving average calculation methods, including Simple Moving Average (SMA), Exponential Moving Average (EMA), Double Exponential Moving Average (DEMA), etc., allowing selection of the most suitable MA type for different market characteristics.
|
||
|
|
|
||
|
|
#### Strategy Advantages
|
||
|
|
1. High Flexibility: Supports various moving average types, allowing selection of optimal MA calculation methods for different market environments
|
||
|
|
2. Trend Confirmation: ADX filtering effectively reduces false signals in oscillating markets
|
||
|
|
3. Comprehensive Risk Control: Includes stop-loss and take-profit functions for effective risk control per trade
|
||
|
|
4. High Customizability: Provides multiple parameter interfaces, including MA period, ADX threshold, trading direction, etc., facilitating strategy optimization
|
||
|
|
5. Multi-timeframe Support: Can operate on different timeframes, adapting to various trading styles
|
||
|
|
|
||
|
|
#### Strategy Risks
|
||
|
|
1. MA Lag: Moving averages are inherently lagging indicators, potentially generating delayed signals in rapidly fluctuating markets
|
||
|
|
2. False Breakout Risk: False MA breakouts may occur during market oscillation, despite ADX filtering
|
||
|
|
3. Parameter Sensitivity: Strategy performance is sensitive to parameter settings, requiring appropriate adjustments in different market environments
|
||
|
|
4. Market Adaptability: Performs well in trending markets but may trade frequently in oscillating markets
|
||
|
|
5. Computational Complexity: Multiple MA type calculations may increase system load, requiring attention to operational efficiency
|
||
|
|
|
||
|
|
#### Strategy Optimization Directions
|
||
|
|
1. Incorporate Volume Indicators: Combine volume changes to confirm trend validity
|
||
|
|
2. Optimize ADX Parameters: Dynamically adjust ADX thresholds based on different market cycles
|
||
|
|
3. Add Trend Confirmation Indicators: Consider adding other trend indicators to improve signal reliability
|
||
|
|
4. Enhance Stop-Loss Mechanism: Introduce trailing stops or volatility-adaptive stop-losses
|
||
|
|
5. Optimize Trading Timing: Consider market volatility and liquidity factors to select optimal trading times
|
||
|
|
|
||
|
|
#### Summary
|
||
|
|
This is a quantitative trading system that combines classic moving average crossover strategy with the ADX indicator. Through support for multiple MA types and ADX trend confirmation, it effectively captures market trends while maintaining comprehensive risk control mechanisms. The strategy's high customizability allows optimization for different market environments. While inherent risks exist, through proper parameter settings and continuous optimization, this strategy demonstrates good practical value.[/trans]
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
> Source (PineScript)
|
||
|
|
|
||
|
|
``` pinescript
|
||
|
|
/*backtest
|
||
|
|
start: 2024-02-18 00:00:00
|
||
|
|
end: 2025-02-16 08:00:00
|
||
|
|
period: 3d
|
||
|
|
basePeriod: 3d
|
||
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
||
|
|
*/
|
||
|
|
|
||
|
|
// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
|
||
|
|
// © algostudio
|
||
|
|
|
||
|
|
//@version=6
|
||
|
|
strategy("Open Close Cross Strategy R5.1", shorttitle="OCC Strategy R5.1", overlay=true,
|
||
|
|
pyramiding=0, default_qty_type=strategy.percent_of_equity, default_qty_value=10, calc_on_every_tick=false)
|
||
|
|
|
||
|
|
// === INPUTS ===
|
||
|
|
useRes = input.bool(true, title="Use Alternate Resolution?")
|
||
|
|
intRes = input.int(3, title="Multiplier for Alternate Resolution", minval=1)
|
||
|
|
stratRes = timeframe.ismonthly ? str.tostring(timeframe.multiplier * intRes) + "M" :
|
||
|
|
timeframe.isweekly ? str.tostring(timeframe.multiplier * intRes) + "W" :
|
||
|
|
timeframe.isdaily ? str.tostring(timeframe.multiplier * intRes) + "D" :
|
||
|
|
timeframe.isintraday ? str.tostring(timeframe.multiplier * intRes) : "60"
|
||
|
|
|
||
|
|
basisType = input.string("SMMA", title="MA Type:", options=["SMA", "EMA", "DEMA", "TEMA", "WMA", "VWMA", "SMMA", "HullMA", "LSMA", "ALMA", "SSMA", "TMA"])
|
||
|
|
basisLen = input.int(8, title="MA Period", minval=1)
|
||
|
|
offsetSigma = input.int(6, title="Offset for LSMA / Sigma for ALMA", minval=0)
|
||
|
|
offsetALMA = input.float(0.85, title="Offset for ALMA", minval=0, step=0.01)
|
||
|
|
scolor = input.bool(false, title="Show Colored Bars to Indicate Trend?")
|
||
|
|
delayOffset = input.int(0, title="Delay Open/Close MA (Forces Non-Repainting)", minval=0, step=1)
|
||
|
|
tradeType = input.string("BOTH", title="What trades should be taken:", options=["LONG", "SHORT", "BOTH", "NONE"])
|
||
|
|
|
||
|
|
// === BASE FUNCTIONS ===
|
||
|
|
variant(type, src, len, offSig, offALMA) =>
|
||
|
|
if type == "EMA"
|
||
|
|
ta.ema(src, len)
|
||
|
|
else if type == "DEMA"
|
||
|
|
ta.ema(ta.ema(src, len), len) * 2 - ta.ema(ta.ema(ta.ema(src, len), len), len)
|
||
|
|
else if type == "TEMA"
|
||
|
|
3 * (ta.ema(src, len) - ta.ema(ta.ema(src, len), len)) + ta.ema(ta.ema(ta.ema(src, len), len), len)
|
||
|
|
else if type == "WMA"
|
||
|
|
ta.wma(src, len)
|
||
|
|
else if type == "VWMA"
|
||
|
|
ta.vwma(src, len)
|
||
|
|
else if type == "SMMA"
|
||
|
|
ta.sma(src, len)
|
||
|
|
else if type == "HullMA"
|
||
|
|
ta.wma(2 * ta.wma(src, len / 2) - ta.wma(src, len), math.round(math.sqrt(len)))
|
||
|
|
else if type == "LSMA"
|
||
|
|
ta.linreg(src, len, offSig)
|
||
|
|
else if type == "ALMA"
|
||
|
|
ta.alma(src, len, offALMA, offSig)
|
||
|
|
else if type == "TMA"
|
||
|
|
ta.sma(ta.sma(src, len), len)
|
||
|
|
else
|
||
|
|
ta.sma(src, len)
|
||
|
|
|
||
|
|
// Security wrapper
|
||
|
|
reso(exp, use, res) => use ? request.security(syminfo.tickerid, res, exp, lookahead=barmerge.lookahead_on) : exp
|
||
|
|
|
||
|
|
// === SERIES SETUP ===
|
||
|
|
closeSeries = variant(basisType, close[delayOffset], basisLen, offsetSigma, offsetALMA)
|
||
|
|
openSeries = variant(basisType, open[delayOffset], basisLen, offsetSigma, offsetALMA)
|
||
|
|
|
||
|
|
// Alternate resolution series
|
||
|
|
closeSeriesAlt = reso(closeSeries, useRes, stratRes)
|
||
|
|
openSeriesAlt = reso(openSeries, useRes, stratRes)
|
||
|
|
|
||
|
|
// Trend Colors
|
||
|
|
trendColour = closeSeriesAlt > openSeriesAlt ? color.green : color.red
|
||
|
|
bcolour = closeSeries > openSeriesAlt ? color.lime : color.red
|
||
|
|
barcolor(scolor ? bcolour : na, title="Bar Colours")
|
||
|
|
|
||
|
|
closeP = plot(closeSeriesAlt, title="Close Series", color=trendColour, linewidth=2, style=plot.style_line)
|
||
|
|
openP = plot(openSeriesAlt, title="Open Series", color=trendColour, linewidth=2, style=plot.style_line)
|
||
|
|
fill(closeP, openP, color=trendColour)
|
||
|
|
// === ADX FILTER ===
|
||
|
|
// ADX Calculation
|
||
|
|
// Input parameters
|
||
|
|
adxLength = input.int(14, title="ADX Length", minval=1)
|
||
|
|
adxfilter = input.int(13, title="ADX filter", minval=1)
|
||
|
|
// Calculate +DM and -DM (Directional Movement)
|
||
|
|
plusDM = math.max(high - high[1], 0)
|
||
|
|
minusDM = math.max(low[1] - low, 0)
|
||
|
|
|
||
|
|
// Remove cases where both are positive
|
||
|
|
plusDM := plusDM > minusDM ? plusDM : 0
|
||
|
|
minusDM := minusDM > plusDM ? minusDM : 0
|
||
|
|
|
||
|
|
// Smooth the directional movement using RMA
|
||
|
|
smoothedPlusDM = ta.rma(plusDM, adxLength)
|
||
|
|
smoothedMinusDM = ta.rma(minusDM, adxLength)
|
||
|
|
|
||
|
|
// Calculate True Range and smooth it
|
||
|
|
tr = ta.atr(adxLength)
|
||
|
|
smoothedTR = ta.rma(tr, adxLength)
|
||
|
|
|
||
|
|
// Compute +DI and -DI
|
||
|
|
plusDI = (smoothedPlusDM / smoothedTR) * 100
|
||
|
|
minusDI = (smoothedMinusDM / smoothedTR) * 100
|
||
|
|
|
||
|
|
// Compute DX (Directional Index)
|
||
|
|
dx = math.abs(plusDI - minusDI) / (plusDI + minusDI) * 100
|
||
|
|
|
||
|
|
// Compute ADX by smoothing DX
|
||
|
|
adx = ta.rma(dx, adxLength)
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
// === UPDATED TRADE CONDITIONS ===
|
||
|
|
xlong = ta.crossover(closeSeriesAlt, openSeriesAlt) and adx > adxfilter
|
||
|
|
xshort = ta.crossunder(closeSeriesAlt, openSeriesAlt) and adx > adxfilter
|
||
|
|
longCond = xlong
|
||
|
|
shortCond = xshort
|
||
|
|
|
||
|
|
|
||
|
|
// === STRATEGY ===
|
||
|
|
slPoints = input.float(0, title="Initial Stop Loss Points", minval=0)
|
||
|
|
tpPoints = input.float(0, title="Initial Target Profit Points", minval=0)
|
||
|
|
ebar = input.int(10000, title="Number of Bars for Back Testing", minval=0)
|
||
|
|
|
||
|
|
tdays = (timenow - time) / 60000.0
|
||
|
|
|
||
|
|
tdays := timeframe.ismonthly ? tdays / 1440.0 / 5.0 / 4.3 / timeframe.multiplier :
|
||
|
|
timeframe.isweekly ? tdays / 1440.0 / 5.0 / timeframe.multiplier :
|
||
|
|
timeframe.isdaily ? tdays / 1440.0 / timeframe.multiplier :
|
||
|
|
tdays / timeframe.multiplier
|
||
|
|
|
||
|
|
TP = tpPoints > 0 ? tpPoints : na
|
||
|
|
SL = slPoints > 0 ? slPoints : na
|
||
|
|
|
||
|
|
if (ebar == 0 or tdays <= ebar)
|
||
|
|
if longCond and tradeType != "SHORT"
|
||
|
|
strategy.entry("long", strategy.long)
|
||
|
|
if shortCond and tradeType != "LONG"
|
||
|
|
strategy.entry("short", strategy.short)
|
||
|
|
if shortCond and tradeType == "LONG"
|
||
|
|
strategy.close("long")
|
||
|
|
if longCond and tradeType == "SHORT"
|
||
|
|
strategy.close("short")
|
||
|
|
strategy.exit("XL", from_entry="long", profit=TP, loss=SL)
|
||
|
|
strategy.exit("XS", from_entry="short", profit=TP, loss=SL)
|
||
|
|
|
||
|
|
// === END ===
|
||
|
|
|
||
|
|
|
||
|
|
```
|
||
|
|
|
||
|
|
> Detail
|
||
|
|
|
||
|
|
https://www.fmz.com/strategy/482420
|
||
|
|
|
||
|
|
> Last Modified
|
||
|
|
|
||
|
|
2025-02-18 13:35:54
|