190 lines
9.0 KiB
Markdown
190 lines
9.0 KiB
Markdown

|
|
||
|
|
> Name
|
||
|
|
|
||
|
|
多重平滑均线动态交叉趋势跟踪与多重确认量化交易策略-Multi-Smoothed-Moving-Average-Dynamic-Crossover-Trend-Following-Strategy-with-Multiple-Confirmations
|
||
|
|
|
||
|
|
> Author
|
||
|
|
|
||
|
|
ChaoZhang
|
||
|
|
|
||
|
|
> Strategy Description
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
[trans]
|
||
|
|
#### 概述
|
||
|
|
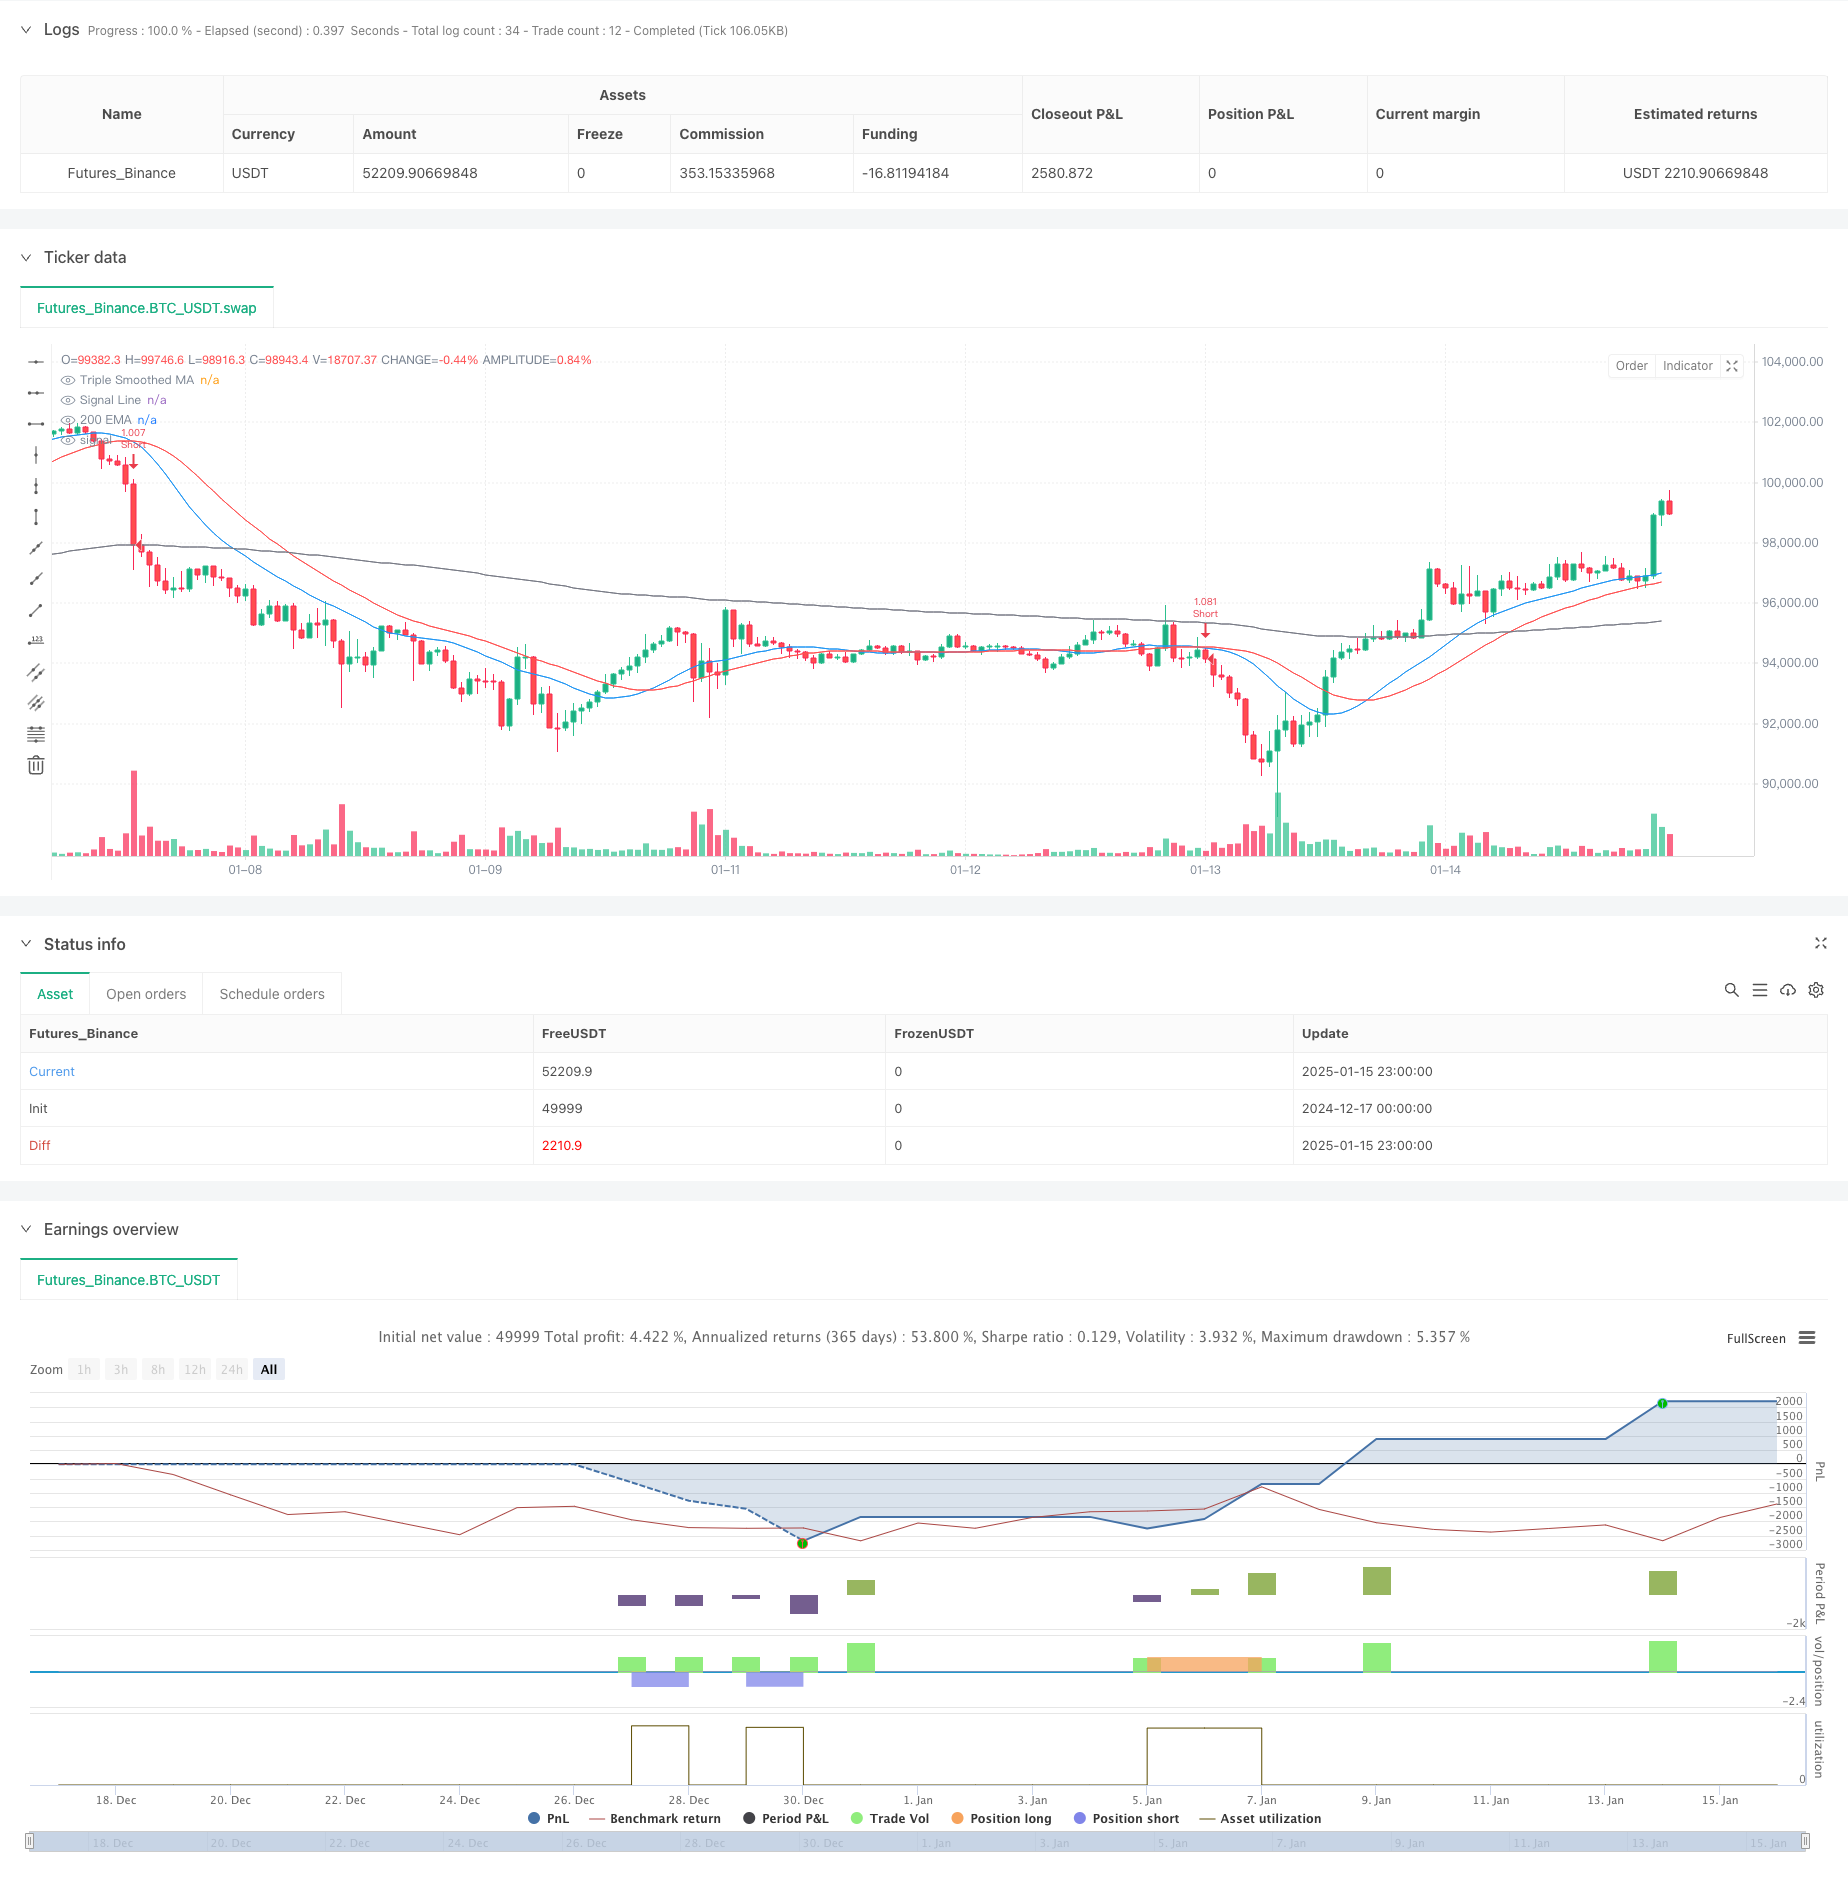
该策略是一个基于多重平滑移动平均线的趋势跟踪系统,通过三重平滑处理来过滤市场噪音,同时结合RSI动量指标、ATR波动率指标和200周期EMA趋势过滤器来确认交易信号。策略采用1小时时间周期,这个时间框架能够有效平衡交易频率和趋势可靠性,同时与机构交易行为相匹配。
|
||
|
|
|
||
|
|
#### 策略原理
|
||
|
|
策略的核心是通过对价格进行三次平滑处理来构建主要趋势线,并使用较短周期的信号线与之交叉产生交易信号。交易信号需要同时满足以下条件才会执行:
|
||
|
|
1. 价格位置与200EMA的关系确认主趋势方向
|
||
|
|
2. RSI指标位置确认动量
|
||
|
|
3. ATR指标确认足够的波动性
|
||
|
|
4. 信号线与三重平滑均线的交叉确认具体入场点
|
||
|
|
止损采用基于ATR的动态止损,止盈采用2倍ATR设置,确保良好的风险收益比。
|
||
|
|
|
||
|
|
#### 策略优势
|
||
|
|
1. 三重平滑处理显著降低了虚假信号,提高了趋势判断的可靠性
|
||
|
|
2. 多重确认机制确保交易方向与主要趋势保持一致
|
||
|
|
3. 动态的止损和止盈设置适应不同的市场波动环境
|
||
|
|
4. 策略在1小时周期上运行,能够有效避免更低时间周期的震荡
|
||
|
|
5. 无重绘特性保证了回测结果的可靠性
|
||
|
|
|
||
|
|
#### 策略风险
|
||
|
|
1. 在横盘市场可能产生连续的小幅亏损
|
||
|
|
2. 多重确认机制可能导致错过一些交易机会
|
||
|
|
3. 信号滞后性可能影响入场点位的优化程度
|
||
|
|
4. 需要足够的波动率才能产生有效信号
|
||
|
|
5. 在极端市场环境下动态止损可能不够及时
|
||
|
|
|
||
|
|
#### 策略优化方向
|
||
|
|
1. 可以增加成交量指标作为辅助确认
|
||
|
|
2. 考虑引入自适应的参数优化机制
|
||
|
|
3. 可以增加趋势强度的量化判断
|
||
|
|
4. 优化止损止盈的倍数设置
|
||
|
|
5. 考虑加入震荡指标以优化横盘市场表现
|
||
|
|
|
||
|
|
#### 总结
|
||
|
|
这是一个结构完整、逻辑严密的趋势跟踪策略。通过多重平滑处理和多重确认机制,有效地提高了交易信号的可靠性。动态的风险管理机制使其具有良好的适应性。虽然存在一定的滞后性,但通过参数优化和增加辅助指标,策略仍有较大的改进空间。 ||
|
||
|
|
|
||
|
|
#### Overview
|
||
|
|
This strategy is a trend-following system based on multiple smoothed moving averages, using triple smoothing to filter market noise while combining RSI momentum indicator, ATR volatility indicator, and 200-period EMA trend filter to confirm trading signals. The strategy operates on a 1-hour timeframe, which effectively balances trading frequency and trend reliability while aligning with institutional trading behavior.
|
||
|
|
|
||
|
|
#### Strategy Principles
|
||
|
|
The core of the strategy is to construct a main trend line through triple smoothing of prices and generate trading signals through crossovers with a shorter-period signal line. Trade signals must simultaneously meet the following conditions:
|
||
|
|
1. Price position relative to 200EMA confirms main trend direction
|
||
|
|
2. RSI indicator position confirms momentum
|
||
|
|
3. ATR indicator confirms sufficient volatility
|
||
|
|
4. Signal line crossover with triple-smoothed MA confirms specific entry points
|
||
|
|
Stop-loss uses ATR-based dynamic stops, while take-profit is set at 2x ATR to ensure favorable risk-reward ratios.
|
||
|
|
|
||
|
|
#### Strategy Advantages
|
||
|
|
1. Triple smoothing significantly reduces false signals and improves trend judgment reliability
|
||
|
|
2. Multiple confirmation mechanisms ensure trade direction aligns with major trends
|
||
|
|
3. Dynamic stop-loss and take-profit settings adapt to different market volatility environments
|
||
|
|
4. Strategy operation on 1-hour timeframe effectively avoids lower timeframe oscillations
|
||
|
|
5. Non-repainting feature guarantees backtest result reliability
|
||
|
|
|
||
|
|
#### Strategy Risks
|
||
|
|
1. May produce consecutive small losses in ranging markets
|
||
|
|
2. Multiple confirmation mechanisms might cause missed trading opportunities
|
||
|
|
3. Signal lag may affect entry point optimization
|
||
|
|
4. Requires sufficient volatility to generate effective signals
|
||
|
|
5. Dynamic stops may not be timely enough in extreme market conditions
|
||
|
|
|
||
|
|
#### Strategy Optimization Directions
|
||
|
|
1. Can add volume indicators as auxiliary confirmation
|
||
|
|
2. Consider introducing adaptive parameter optimization mechanisms
|
||
|
|
3. Can add quantitative trend strength assessment
|
||
|
|
4. Optimize stop-loss and take-profit multiplier settings
|
||
|
|
5. Consider adding oscillator indicators to improve ranging market performance
|
||
|
|
|
||
|
|
#### Summary
|
||
|
|
This is a trend-following strategy with complete structure and rigorous logic. Through multiple smoothing processing and multiple confirmation mechanisms, it effectively improves the reliability of trading signals. The dynamic risk management mechanism provides good adaptability. Although there is some lag, the strategy still has significant room for improvement through parameter optimization and additional auxiliary indicators.[/trans]
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
> Source (PineScript)
|
||
|
|
|
||
|
|
``` pinescript
|
||
|
|
/*backtest
|
||
|
|
start: 2024-12-17 00:00:00
|
||
|
|
end: 2025-01-16 00:00:00
|
||
|
|
period: 1h
|
||
|
|
basePeriod: 1h
|
||
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT","balance":49999}]
|
||
|
|
*/
|
||
|
|
|
||
|
|
//@version=6
|
||
|
|
strategy("Optimized Triple Smoothed MA Crossover Strategy", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=200)
|
||
|
|
|
||
|
|
// === Input Settings ===
|
||
|
|
slength = input.int(7, "Main Smoothing Length", group="Moving Average Settings")
|
||
|
|
siglen = input.int(12, "Signal Length", group="Moving Average Settings")
|
||
|
|
src = input.source(close, "Data Source", group="Moving Average Settings")
|
||
|
|
mat = input.string("EMA", "Triple Smoothed MA Type", ["EMA", "SMA", "RMA", "WMA"], group="Moving Average Settings")
|
||
|
|
mat1 = input.string("EMA", "Signal Type", ["EMA", "SMA", "RMA", "WMA"], group="Moving Average Settings")
|
||
|
|
|
||
|
|
// === Trend Confirmation (Higher Timeframe Filter) ===
|
||
|
|
useTrendFilter = input.bool(true, "Enable Trend Filter (200 EMA)", group="Trend Confirmation")
|
||
|
|
trendMA = ta.ema(close, 200)
|
||
|
|
|
||
|
|
// === Momentum Filter (RSI Confirmation) ===
|
||
|
|
useRSIFilter = input.bool(true, "Enable RSI Confirmation", group="Momentum Confirmation")
|
||
|
|
rsi = ta.rsi(close, 14)
|
||
|
|
rsiThreshold = input.int(50, "RSI Threshold", group="Momentum Confirmation")
|
||
|
|
|
||
|
|
// === Volatility Filter (ATR) ===
|
||
|
|
useATRFilter = input.bool(true, "Enable ATR Filter", group="Volatility Filtering")
|
||
|
|
atr = ta.atr(14)
|
||
|
|
atrMa = ta.sma(atr, 14)
|
||
|
|
|
||
|
|
// === Risk Management (ATR-Based Stop Loss) ===
|
||
|
|
useAdaptiveSL = input.bool(true, "Use ATR-Based Stop Loss", group="Risk Management")
|
||
|
|
atrMultiplier = input.float(1.5, "ATR Multiplier for SL", minval=0.5, maxval=5, group="Risk Management")
|
||
|
|
takeProfitMultiplier = input.float(2, "Take Profit Multiplier", group="Risk Management")
|
||
|
|
|
||
|
|
// === Moving Average Function ===
|
||
|
|
ma(source, length, MAtype) =>
|
||
|
|
switch MAtype
|
||
|
|
"SMA" => ta.sma(source, length)
|
||
|
|
"EMA" => ta.ema(source, length)
|
||
|
|
"RMA" => ta.rma(source, length)
|
||
|
|
"WMA" => ta.wma(source, length)
|
||
|
|
|
||
|
|
// === Triple Smoothed Calculation ===
|
||
|
|
tripleSmoothedMA = ma(ma(ma(src, slength, mat), slength, mat), slength, mat)
|
||
|
|
signalLine = ma(tripleSmoothedMA, siglen, mat1)
|
||
|
|
|
||
|
|
// === Crossovers (Entry Signals) ===
|
||
|
|
bullishCrossover = ta.crossunder(signalLine, tripleSmoothedMA)
|
||
|
|
bearishCrossover = ta.crossover(signalLine, tripleSmoothedMA)
|
||
|
|
|
||
|
|
// === Additional Confirmation Conditions ===
|
||
|
|
trendLongCondition = not useTrendFilter or (close > trendMA) // Only long if price is above 200 EMA
|
||
|
|
trendShortCondition = not useTrendFilter or (close < trendMA) // Only short if price is below 200 EMA
|
||
|
|
|
||
|
|
rsiLongCondition = not useRSIFilter or (rsi > rsiThreshold) // RSI above 50 for longs
|
||
|
|
rsiShortCondition = not useRSIFilter or (rsi < rsiThreshold) // RSI below 50 for shorts
|
||
|
|
|
||
|
|
atrCondition = not useATRFilter or (atr > atrMa) // ATR must be above its MA for volatility confirmation
|
||
|
|
|
||
|
|
// === Final Trade Entry Conditions ===
|
||
|
|
longCondition = bullishCrossover and trendLongCondition and rsiLongCondition and atrCondition
|
||
|
|
shortCondition = bearishCrossover and trendShortCondition and rsiShortCondition and atrCondition
|
||
|
|
|
||
|
|
// === ATR-Based Stop Loss & Take Profit ===
|
||
|
|
longSL = close - (atr * atrMultiplier)
|
||
|
|
longTP = close + (atr * takeProfitMultiplier)
|
||
|
|
|
||
|
|
shortSL = close + (atr * atrMultiplier)
|
||
|
|
shortTP = close - (atr * takeProfitMultiplier)
|
||
|
|
|
||
|
|
// === Strategy Execution ===
|
||
|
|
if longCondition
|
||
|
|
strategy.entry("Long", strategy.long)
|
||
|
|
strategy.exit("Long Exit", from_entry="Long", stop=longSL, limit=longTP)
|
||
|
|
|
||
|
|
if shortCondition
|
||
|
|
strategy.entry("Short", strategy.short)
|
||
|
|
strategy.exit("Short Exit", from_entry="Short", stop=shortSL, limit=shortTP)
|
||
|
|
|
||
|
|
// === Plots ===
|
||
|
|
plot(tripleSmoothedMA, title="Triple Smoothed MA", color=color.blue)
|
||
|
|
plot(signalLine, title="Signal Line", color=color.red)
|
||
|
|
plot(trendMA, title="200 EMA", color=color.gray)
|
||
|
|
|
||
|
|
// === Alerts ===
|
||
|
|
alertcondition(longCondition, title="Bullish Signal", message="Triple Smoothed MA Bullish Crossover Confirmed")
|
||
|
|
alertcondition(shortCondition, title="Bearish Signal", message="Triple Smoothed MA Bearish Crossover Confirmed")
|
||
|
|
|
||
|
|
```
|
||
|
|
|
||
|
|
> Detail
|
||
|
|
|
||
|
|
https://www.fmz.com/strategy/478720
|
||
|
|
|
||
|
|
> Last Modified
|
||
|
|
|
||
|
|
2025-01-17 15:53:16
|