162 lines
7.5 KiB
Markdown
162 lines
7.5 KiB
Markdown

|
|
|||
|
|
> Name
|
|||
|
|
|
|||
|
|
基于Nadaraya-Watson核估计和移动平均交叉的智能趋势跟踪策略系统-Intelligent-Trend-Following-Strategy-System-Based-on-Nadaraya-Watson-Kernel-Estimation-and-Moving-Average-Crossover
|
|||
|
|
|
|||
|
|
> Author
|
|||
|
|
|
|||
|
|
ianzeng123
|
|||
|
|
|
|||
|
|
> Strategy Description
|
|||
|
|
|
|||
|
|
|
|||
|
|
|
|||
|
|
|
|||
|
|
|
|||
|
|
|
|||
|
|
[trans]
|
|||
|
|
#### 概述
|
|||
|
|
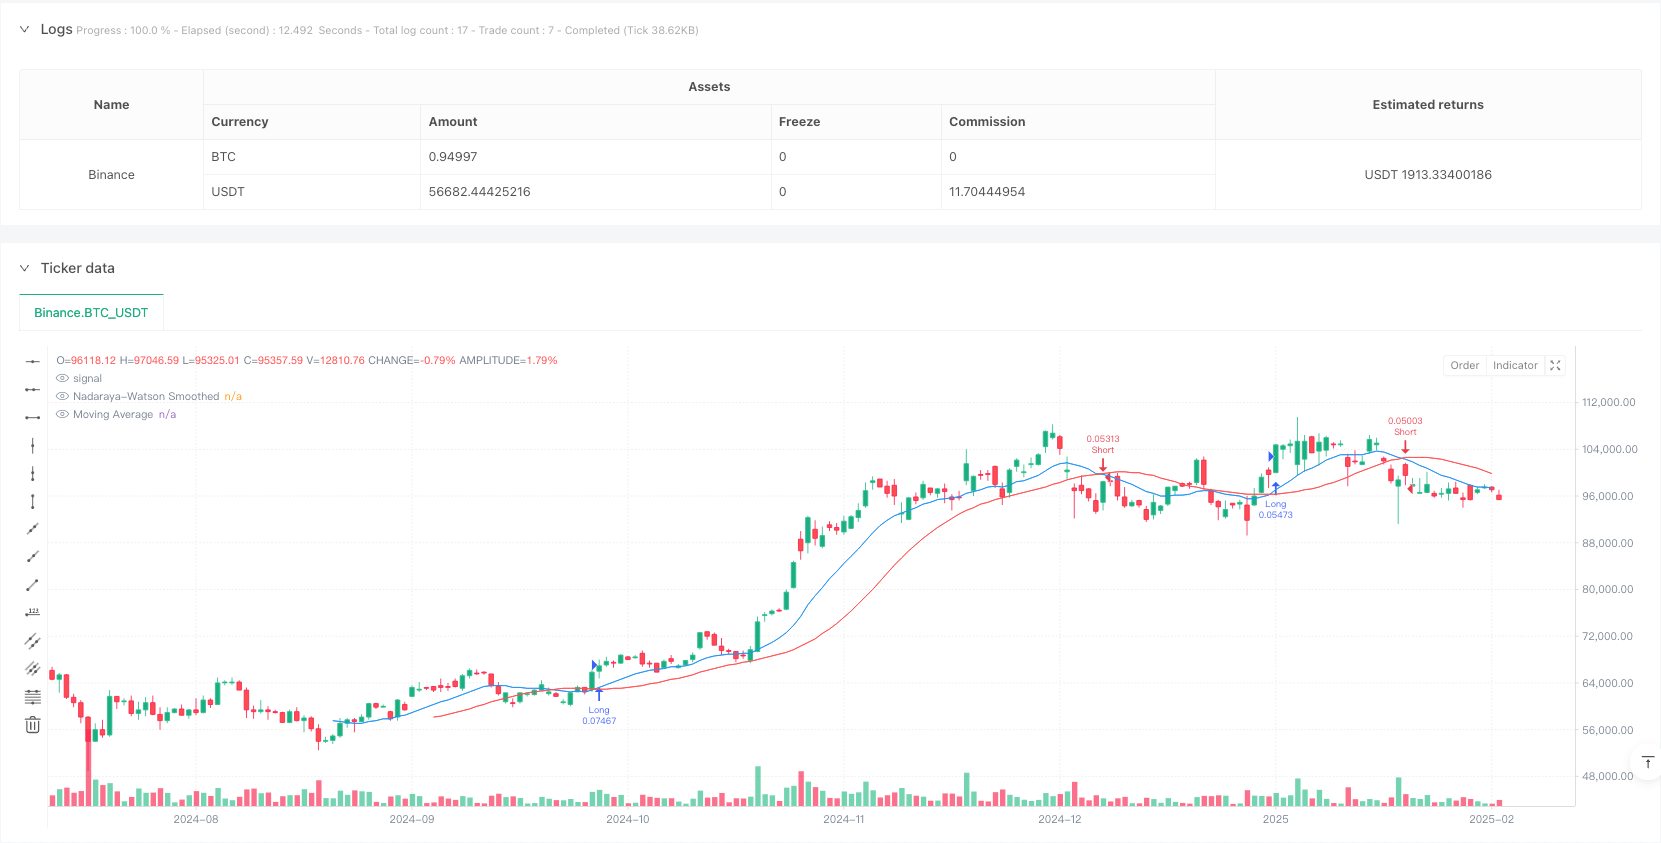
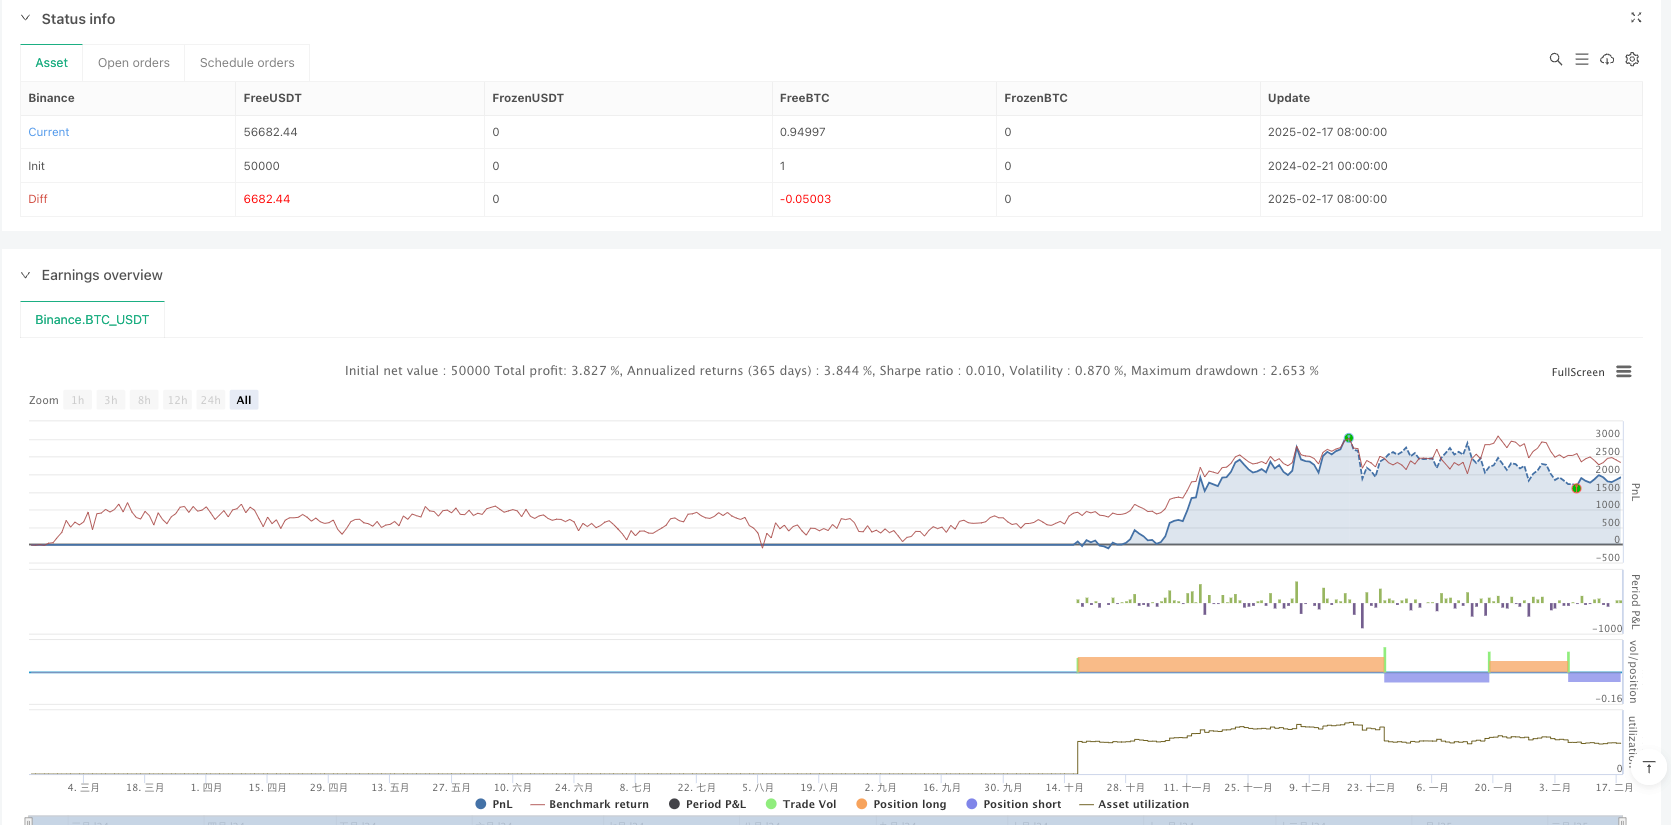
本策略是一个基于Nadaraya-Watson核估计方法和移动平均线交叉的趋势跟踪交易系统。该策略通过高斯核函数对价格数据进行平滑处理,结合移动平均线的交叉信号来捕捉市场趋势,实现智能化的趋势跟踪交易。策略采用百分比仓位管理方式,默认每次交易使用10%的账户权益。
|
|||
|
|
|
|||
|
|
#### 策略原理
|
|||
|
|
策略的核心是Nadaraya-Watson核估计方法,该方法使用高斯核函数对价格数据进行非参数平滑。具体实现包括以下步骤:
|
|||
|
|
1. 使用高斯核函数计算权重,带宽参数h设置为8.0
|
|||
|
|
2. 对过去500个价格数据点进行加权平滑
|
|||
|
|
3. 计算平滑后数据的简单移动平均线(SMA),回溯期为15个周期
|
|||
|
|
4. 当平滑曲线上穿移动平均线时,产生做多信号
|
|||
|
|
5. 当平滑曲线下穿移动平均线时,产生做空信号
|
|||
|
|
6. 使用仓位状态变量跟踪当前持仓情况,避免重复开仓
|
|||
|
|
|
|||
|
|
#### 策略优势
|
|||
|
|
1. 采用非参数估计方法,无需假设数据分布,更好地适应市场变化
|
|||
|
|
2. 高斯核函数平滑可以有效降低噪声影响,提高信号质量
|
|||
|
|
3. 结合移动平均线交叉验证,降低虚假信号
|
|||
|
|
4. 使用仓位管理系统,控制风险敞口
|
|||
|
|
5. 代码实现简洁高效,易于维护和优化
|
|||
|
|
6. 策略逻辑清晰,适合各种时间周期的交易
|
|||
|
|
|
|||
|
|
#### 策略风险
|
|||
|
|
1. 参数敏感性风险:带宽h和移动平均期数的选择会显著影响策略表现
|
|||
|
|
2. 滞后性风险:核估计和移动平均都具有一定滞后性,可能错过急剧行情
|
|||
|
|
3. 震荡市风险:在横盘震荡市场容易产生虚假信号
|
|||
|
|
4. 计算开销:需要处理大量历史数据,可能影响实时性能
|
|||
|
|
5. 过度拟合风险:参数优化可能导致过度拟合历史数据
|
|||
|
|
|
|||
|
|
#### 策略优化方向
|
|||
|
|
1. 引入自适应带宽:根据市场波动率动态调整带宽参数
|
|||
|
|
2. 增加市场环境过滤:添加趋势强度指标,在强趋势市场才开仓
|
|||
|
|
3. 优化止损机制:设计基于波动率的动态止损
|
|||
|
|
4. 改进仓位管理:根据信号强度和市场波动调整仓位大小
|
|||
|
|
5. 引入多时间周期分析:结合更长周期的趋势判断
|
|||
|
|
|
|||
|
|
#### 总结
|
|||
|
|
该策略创新性地将Nadaraya-Watson核估计与传统技术分析相结合,构建了一个稳健的趋势跟踪系统。通过高斯核平滑和移动平均线交叉,有效捕捉市场趋势,同时控制风险。策略具有良好的可扩展性和优化空间,适合进一步开发和实践应用。建议交易者在实盘使用前进行充分的参数优化和回测验证。 ||
|
|||
|
|
|
|||
|
|
#### Overview
|
|||
|
|
This strategy is a trend following trading system based on Nadaraya-Watson kernel estimation method and moving average crossover. The strategy uses a Gaussian kernel function to smooth price data and combines moving average crossover signals to capture market trends, achieving intelligent trend following trading. The strategy adopts percentage position management, using 10% of account equity by default for each trade.
|
|||
|
|
|
|||
|
|
#### Strategy Principles
|
|||
|
|
The core of the strategy is the Nadaraya-Watson kernel estimation method, which uses a Gaussian kernel function for non-parametric smoothing of price data. The specific implementation includes the following steps:
|
|||
|
|
1. Calculate weights using Gaussian kernel function with bandwidth parameter h set to 8.0
|
|||
|
|
2. Perform weighted smoothing on past 500 price data points
|
|||
|
|
3. Calculate Simple Moving Average (SMA) of smoothed data with 15-period lookback
|
|||
|
|
4. Generate long signal when smoothed curve crosses above moving average
|
|||
|
|
5. Generate short signal when smoothed curve crosses below moving average
|
|||
|
|
6. Use position state variable to track current holdings and avoid duplicate entries
|
|||
|
|
|
|||
|
|
#### Strategy Advantages
|
|||
|
|
1. Uses non-parametric estimation method, no assumption of data distribution needed
|
|||
|
|
2. Gaussian kernel smoothing effectively reduces noise impact and improves signal quality
|
|||
|
|
3. Moving average crossover validation reduces false signals
|
|||
|
|
4. Position management system controls risk exposure
|
|||
|
|
5. Code implementation is concise and efficient, easy to maintain and optimize
|
|||
|
|
6. Clear strategy logic suitable for trading across various timeframes
|
|||
|
|
|
|||
|
|
#### Strategy Risks
|
|||
|
|
1. Parameter sensitivity risk: choice of bandwidth h and moving average period significantly affects strategy performance
|
|||
|
|
2. Lag risk: both kernel estimation and moving average have inherent lag, may miss sharp market moves
|
|||
|
|
3. Choppy market risk: prone to false signals in sideways markets
|
|||
|
|
4. Computational overhead: processing large historical data may affect real-time performance
|
|||
|
|
5. Overfitting risk: parameter optimization may lead to overfitting historical data
|
|||
|
|
|
|||
|
|
#### Strategy Optimization Directions
|
|||
|
|
1. Introduce adaptive bandwidth: dynamically adjust bandwidth parameter based on market volatility
|
|||
|
|
2. Add market environment filtering: incorporate trend strength indicators, only enter positions in strong trend markets
|
|||
|
|
3. Optimize stop-loss mechanism: design volatility-based dynamic stop-loss
|
|||
|
|
4. Improve position management: adjust position size based on signal strength and market volatility
|
|||
|
|
5. Introduce multi-timeframe analysis: combine trend judgment from longer timeframes
|
|||
|
|
|
|||
|
|
#### Summary
|
|||
|
|
This strategy innovatively combines Nadaraya-Watson kernel estimation with traditional technical analysis to build a robust trend following system. Through Gaussian kernel smoothing and moving average crossover, it effectively captures market trends while controlling risk. The strategy has good scalability and optimization potential, suitable for further development and practical application. Traders are advised to conduct thorough parameter optimization and backtesting before live trading.[/trans]
|
|||
|
|
|
|||
|
|
|
|||
|
|
|
|||
|
|
> Source (PineScript)
|
|||
|
|
|
|||
|
|
``` pinescript
|
|||
|
|
/*backtest
|
|||
|
|
start: 2024-02-21 00:00:00
|
|||
|
|
end: 2025-02-18 08:00:00
|
|||
|
|
period: 1d
|
|||
|
|
basePeriod: 1d
|
|||
|
|
exchanges: [{"eid":"Binance","currency":"BTC_USDT"}]
|
|||
|
|
*/
|
|||
|
|
|
|||
|
|
// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
|
|||
|
|
// © UniCapInvest
|
|||
|
|
|
|||
|
|
//@version=5
|
|||
|
|
strategy("Nadaraya-Watson Strategy with Moving Average Crossover", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=10, max_bars_back=500)
|
|||
|
|
|
|||
|
|
// Girdiler
|
|||
|
|
h = input.float(8.,'Bandwidth', minval = 0)
|
|||
|
|
src = input(close,'Source')
|
|||
|
|
lookback = input.int(15, "Moving Average Lookback", minval=1)
|
|||
|
|
|
|||
|
|
// Gaussian fonksiyonu
|
|||
|
|
gauss(x, h) => math.exp(-(math.pow(x, 2)/(h * h * 2)))
|
|||
|
|
|
|||
|
|
// Nadaraya-Watson smoothed değerini hesaplama
|
|||
|
|
var float smoothed = na
|
|||
|
|
sum_w = 0.0
|
|||
|
|
sum_xw = 0.0
|
|||
|
|
|
|||
|
|
for i = 0 to 499
|
|||
|
|
w = gauss(i, h)
|
|||
|
|
sum_w += w
|
|||
|
|
sum_xw += src[i] * w
|
|||
|
|
|
|||
|
|
smoothed := sum_w != 0 ? sum_xw / sum_w : na
|
|||
|
|
|
|||
|
|
// Hareketli ortalama hesaplama
|
|||
|
|
ma = ta.sma(smoothed, lookback)
|
|||
|
|
|
|||
|
|
// Alım ve satım koşulları (kesişimlere göre)
|
|||
|
|
longCondition = ta.crossover(smoothed, ma)
|
|||
|
|
shortCondition = ta.crossunder(smoothed, ma)
|
|||
|
|
|
|||
|
|
// Pozisyon durumu
|
|||
|
|
var bool inPosition = false
|
|||
|
|
|
|||
|
|
// Strateji giriş ve çıkış koşulları
|
|||
|
|
if (longCondition and not inPosition)
|
|||
|
|
strategy.entry("Long", strategy.long)
|
|||
|
|
inPosition := true
|
|||
|
|
|
|||
|
|
if (shortCondition and inPosition)
|
|||
|
|
strategy.entry("Short", strategy.short)
|
|||
|
|
inPosition := false
|
|||
|
|
|
|||
|
|
// Plotting
|
|||
|
|
plot(smoothed, color=color.blue, title="Nadaraya-Watson Smoothed")
|
|||
|
|
plot(ma, color=color.red, title="Moving Average")
|
|||
|
|
```
|
|||
|
|
|
|||
|
|
> Detail
|
|||
|
|
|
|||
|
|
https://www.fmz.com/strategy/482809
|
|||
|
|
|
|||
|
|
> Last Modified
|
|||
|
|
|
|||
|
|
2025-02-20 14:54:41
|