217 lines
13 KiB
Markdown
217 lines
13 KiB
Markdown

|
|
||
|
|
> Name
|
||
|
|
|
||
|
|
均线与超级趋势结合的日内多空动态平衡策略Dynamic-Intraday-Long-Short-Balancing-Strategy-Combining-Moving-Average-and-Supertrend
|
||
|
|
|
||
|
|
> Author
|
||
|
|
|
||
|
|
ChaoZhang
|
||
|
|
|
||
|
|
> Strategy Description
|
||
|
|
|
||
|
|
|
||
|
|
[trans]
|
||
|
|
|
||
|
|
## 策略概述
|
||
|
|
|
||
|
|
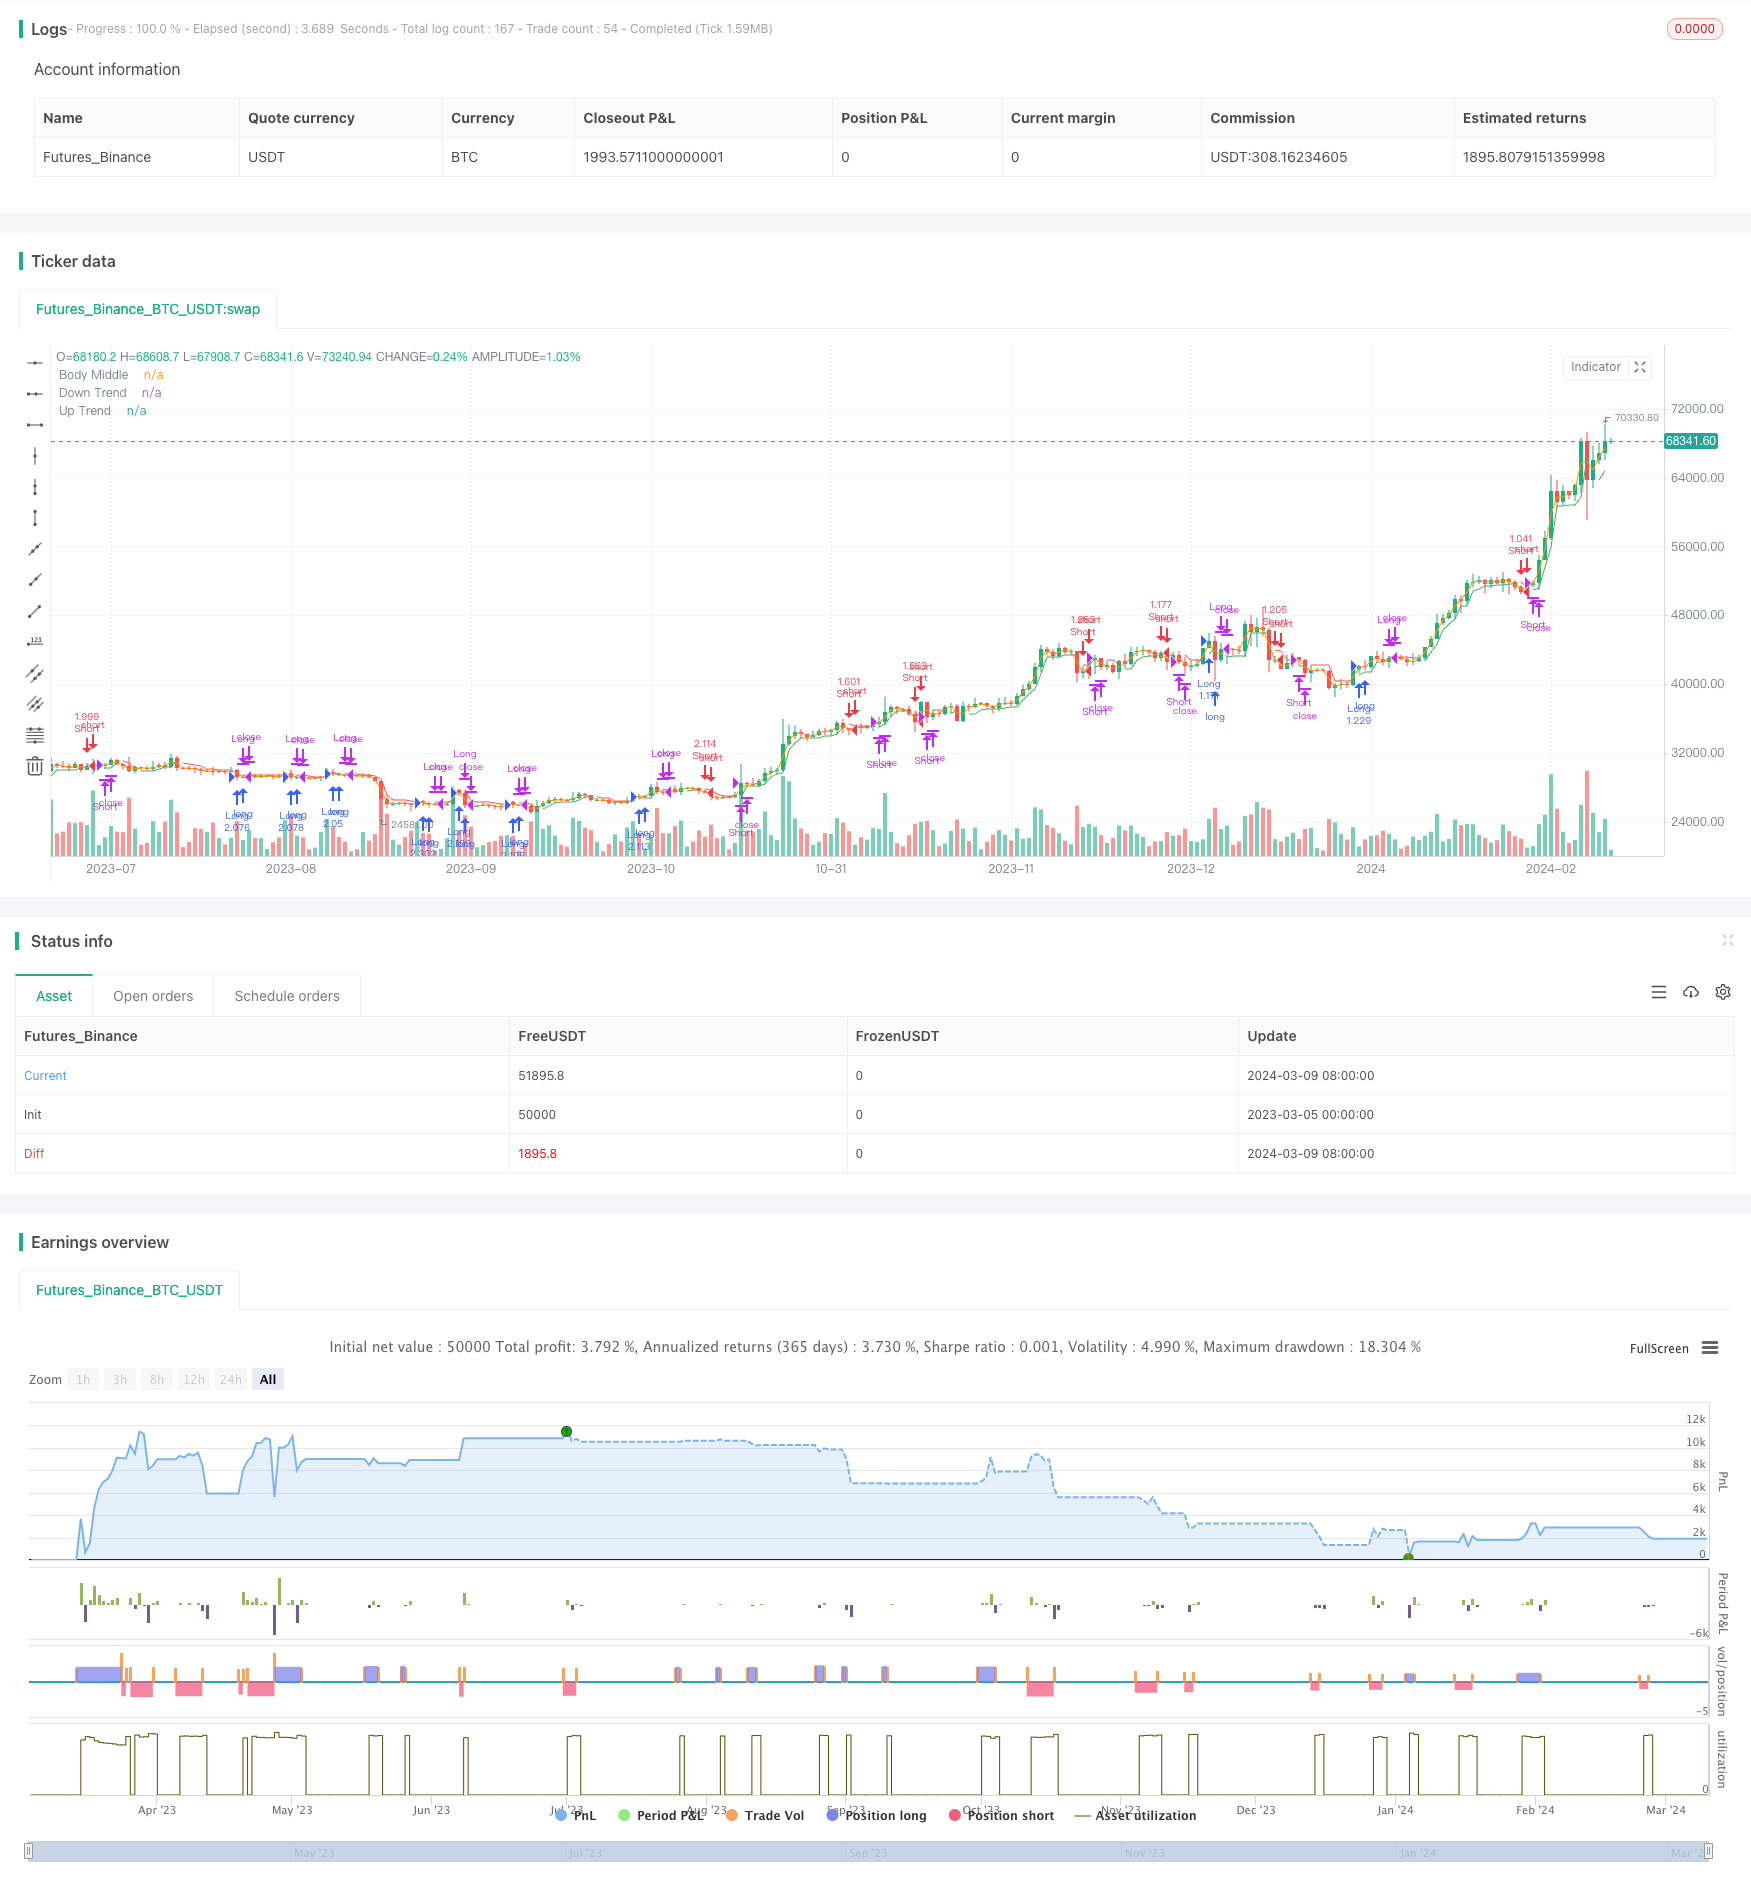
均线与超级趋势结合的日内多空动态平衡策略是一个基于Pine Script™ 5编写的量化交易策略。该策略利用MACD指标和超级趋势指标来捕捉市场的趋势性机会,同时通过动态的多空切换和止损止盈来控制风险。
|
||
|
|
|
||
|
|
## 策略原理
|
||
|
|
|
||
|
|
该策略的核心是将MACD指标和超级趋势指标相结合来判断市场的趋势方向。具体来说:
|
||
|
|
|
||
|
|
1. 使用超级趋势指标判断当前的趋势方向。当超级趋势指标发生变化时,表明趋势发生了反转。
|
||
|
|
2. 使用MACD指标的柱状图来判断动量的变化。当MACD柱状图由负转正时,表明上涨动能增强;当MACD柱状图由正转负时,表明下跌动能增强。
|
||
|
|
3. 当超级趋势指标和MACD指标同时发出做多信号时,开多仓;当超级趋势指标和MACD指标同时发出做空信号时,开空仓。
|
||
|
|
4. 在每个交易日的固定时间(如15:15)平掉所有仓位,避免隔夜风险。
|
||
|
|
5. 在新的交易日(如9:30),根据超级趋势指标和MACD指标的指示重新开仓。
|
||
|
|
|
||
|
|
通过动态的多空切换,该策略能够适应市场的变化,捕捉趋势性机会。同时,固定时间平仓的设计也有助于控制风险。
|
||
|
|
|
||
|
|
## 策略优势
|
||
|
|
|
||
|
|
1. 趋势跟踪:通过将超级趋势指标和MACD指标相结合,该策略能够有效捕捉市场的趋势性机会。
|
||
|
|
2. 动态多空切换:该策略会根据指标的变化动态调整仓位方向,适应市场的变化。
|
||
|
|
3. 风险控制:通过固定时间平仓和多空动态切换,该策略能够较好地控制风险。
|
||
|
|
4. 参数灵活:该策略的参数(如ATR周期、因子等)可以根据市场特点和个人偏好进行调整,具有一定的灵活性。
|
||
|
|
|
||
|
|
## 策略风险
|
||
|
|
|
||
|
|
1. 指标失效风险:在某些市场环境下,MACD指标和超级趋势指标可能会发出错误信号,导致策略失效。
|
||
|
|
2. 参数优化风险:该策略的表现依赖于参数的选择,不恰当的参数可能导致策略表现不佳。
|
||
|
|
3. 止损风险:该策略没有明确的止损逻辑,这可能导致在极端市场环境下出现较大损失。
|
||
|
|
4. 隔夜风险:虽然该策略在日内平仓,但在隔夜开仓时仍可能面临隔夜缺口的风险。
|
||
|
|
|
||
|
|
## 优化方向
|
||
|
|
|
||
|
|
1. 增加止损逻辑:在策略中加入明确的止损逻辑,如固定百分比止损或ATR止损,以进一步控制风险。
|
||
|
|
2. 参数优化:对策略的关键参数,如ATR周期、因子、MACD参数等进行优化,以提高策略的稳健性和收益性。
|
||
|
|
3. 信号过滤:加入更多的信号过滤条件,如价格突破、交易量等,以提高信号的可靠性。
|
||
|
|
4. 多市场测试:在不同的市场和品种上测试该策略,评估其适用性和稳定性。
|
||
|
|
|
||
|
|
## 总结
|
||
|
|
|
||
|
|
均线与超级趋势结合的日内多空动态平衡策略是一个基于趋势跟踪和动量判断的交易策略。通过将超级趋势指标和MACD指标相结合,动态调整仓位方向,该策略能够适应市场的变化,捕捉趋势性机会。同时,固定时间平仓的设计也有助于控制隔夜风险。
|
||
|
|
|
||
|
|
然而,该策略也存在一些风险和不足,如指标失效风险、参数优化风险、止损风险等。为进一步完善该策略,可以考虑增加止损逻辑、优化参数、加入更多信号过滤条件以及在多市场上测试等。
|
||
|
|
|
||
|
|
总的来说,均线与超级趋势结合的日内多空动态平衡策略提供了一个趋势跟踪和风险控制的思路。在实际应用中,交易者应结合自己的风险偏好和市场特点,对策略进行适当调整和优化,审慎运用。量化交易策略虽然可以提供交易思路,但市场瞬息万变,任何策略都不能保证盈利。投资者须理解策略的原理和风险,合理控制仓位,严格止损,时刻保持警惕,才能在市场中长期生存。
|
||
|
|
|
||
|
|
||
|
||
|
|
|
||
|
|
## Strategy Overview
|
||
|
|
|
||
|
|
The Dynamic Intraday Long-Short Balancing Strategy Combining Moving Average and Supertrend is a quantitative trading strategy written in Pine Script™ 5. The strategy utilizes the MACD indicator and the Supertrend indicator to capture trending opportunities in the market, while controlling risk through dynamic long-short switching and stop-loss/take-profit.
|
||
|
|
|
||
|
|
## Strategy Principles
|
||
|
|
|
||
|
|
The core of this strategy is to combine the MACD indicator and the Supertrend indicator to determine the trend direction of the market. Specifically:
|
||
|
|
|
||
|
|
1. Use the Supertrend indicator to determine the current trend direction. When the Supertrend indicator changes, it indicates a reversal of the trend.
|
||
|
|
2. Use the histogram of the MACD indicator to judge the change in momentum. When the MACD histogram turns from negative to positive, it indicates an increase in upward momentum; when the MACD histogram turns from positive to negative, it indicates an increase in downward momentum.
|
||
|
|
3. Open a long position when both the Supertrend indicator and the MACD indicator give a long signal; open a short position when both the Supertrend indicator and the MACD indicator give a short signal.
|
||
|
|
4. Close all positions at a fixed time (such as 15:15) on each trading day to avoid overnight risk.
|
||
|
|
5. Re-open positions on a new trading day (such as 9:30) according to the indications of the Supertrend indicator and the MACD indicator.
|
||
|
|
|
||
|
|
Through dynamic long-short switching, the strategy can adapt to changes in the market and capture trending opportunities. At the same time, the design of closing positions at a fixed time also helps to control risk.
|
||
|
|
|
||
|
|
## Strategy Advantages
|
||
|
|
|
||
|
|
1. Trend tracking: By combining the Supertrend indicator and the MACD indicator, the strategy can effectively capture trending opportunities in the market.
|
||
|
|
2. Dynamic long-short switching: The strategy dynamically adjusts the position direction according to changes in the indicators, adapting to market changes.
|
||
|
|
3. Risk control: Through fixed-time position closing and dynamic long-short switching, the strategy can control risk relatively well.
|
||
|
|
4. Parameter flexibility: The parameters of the strategy (such as ATR period, factor, etc.) can be adjusted according to market characteristics and personal preferences, providing certain flexibility.
|
||
|
|
|
||
|
|
## Strategy Risks
|
||
|
|
|
||
|
|
1. Indicator failure risk: In some market environments, the MACD indicator and the Supertrend indicator may give false signals, leading to strategy failure.
|
||
|
|
2. Parameter optimization risk: The performance of the strategy depends on the choice of parameters, and inappropriate parameters may lead to poor strategy performance.
|
||
|
|
3. Stop-loss risk: The strategy does not have an explicit stop-loss logic, which may lead to significant losses in extreme market environments.
|
||
|
|
4. Overnight risk: Although the strategy closes positions intraday, it may still face the risk of overnight gaps when opening positions overnight.
|
||
|
|
|
||
|
|
## Optimization Directions
|
||
|
|
|
||
|
|
1. Add stop-loss logic: Add explicit stop-loss logic to the strategy, such as fixed percentage stop-loss or ATR stop-loss, to further control risk.
|
||
|
|
2. Parameter optimization: Optimize key parameters of the strategy, such as ATR period, factor, MACD parameters, etc., to improve the robustness and profitability of the strategy.
|
||
|
|
3. Signal filtering: Add more signal filtering conditions, such as price breakout, trading volume, etc., to improve the reliability of signals.
|
||
|
|
4. Multi-market testing: Test the strategy in different markets and instruments to evaluate its applicability and stability.
|
||
|
|
|
||
|
|
## Summary
|
||
|
|
|
||
|
|
The Dynamic Intraday Long-Short Balancing Strategy Combining Moving Average and Supertrend is a trading strategy based on trend tracking and momentum judgment. By combining the Supertrend indicator and the MACD indicator and dynamically adjusting the position direction, the strategy can adapt to changes in the market and capture trending opportunities. At the same time, the design of closing positions at a fixed time also helps to control overnight risk.
|
||
|
|
|
||
|
|
However, the strategy also has some risks and shortcomings, such as indicator failure risk, parameter optimization risk, stop-loss risk, etc. To further improve the strategy, one can consider adding stop-loss logic, optimizing parameters, adding more signal filtering conditions, and testing in multiple markets.
|
||
|
|
|
||
|
|
Overall, the Dynamic Intraday Long-Short Balancing Strategy Combining Moving Average and Supertrend provides a way of thinking for trend tracking and risk control. In practical application, traders should make appropriate adjustments and optimizations to the strategy based on their own risk preferences and market characteristics, and use it cautiously. Quantitative trading strategies can provide trading ideas, but the market is ever-changing, and no strategy can guarantee profits. Investors must understand the principles and risks of the strategy, reasonably control positions, strictly stop losses, and always remain alert in order to survive in the market for the long term.
|
||
|
|
[/trans]
|
||
|
|
|
||
|
|
> Strategy Arguments
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
|Argument|Default|Description|
|
||
|
|
|----|----|----|
|
||
|
|
|v_input_int_1|7|ATR Length|
|
||
|
|
|v_input_float_1|true|Factor|
|
||
|
|
|v_input_1|Asia/Kolkata|Timezone|
|
||
|
|
|
||
|
|
|
||
|
|
> Source (PineScript)
|
||
|
|
|
||
|
|
``` pinescript
|
||
|
|
/*backtest
|
||
|
|
start: 2023-03-05 00:00:00
|
||
|
|
end: 2024-03-10 00:00:00
|
||
|
|
period: 1d
|
||
|
|
basePeriod: 1h
|
||
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
||
|
|
*/
|
||
|
|
|
||
|
|
// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
|
||
|
|
// © smj31071995
|
||
|
|
|
||
|
|
//@version=5
|
||
|
|
strategy("EQ - INTRA - Samsuga supertrend prod", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100, calc_on_every_tick = false)
|
||
|
|
|
||
|
|
|
||
|
|
atrPeriod = input.int(7, "ATR Length", minval = 1)
|
||
|
|
factor = input.float(1.0, "Factor", minval = 0.01, step = 0.01)
|
||
|
|
st_tf = "3"
|
||
|
|
macd_tf="30"
|
||
|
|
|
||
|
|
[supertrend, direction] =request.security(symbol = syminfo.tickerid, timeframe = st_tf,expression = ta.supertrend(factor, atrPeriod),lookahead=barmerge.lookahead_on)
|
||
|
|
|
||
|
|
supertrend := barstate.isfirst ? na : supertrend
|
||
|
|
upTrend = plot(direction <= 0 ? supertrend : na, "Up Trend", color = color.green, style = plot.style_linebr)
|
||
|
|
downTrend = plot(direction <= 0 ? na : supertrend, "Down Trend", color = color.red, style = plot.style_linebr)
|
||
|
|
bodyMiddle = plot(barstate.isfirst ? na : (open + close) / 2, "Body Middle",display = display.none)
|
||
|
|
longcondition = direction[1] > direction
|
||
|
|
shortCondition = direction[1] < direction
|
||
|
|
|
||
|
|
macdp1 = 2
|
||
|
|
macdp2=8
|
||
|
|
macdp3=4
|
||
|
|
|
||
|
|
[macdLine, signalLine, histLine] =request.security(symbol = syminfo.tickerid, timeframe = macd_tf,expression = ta.macd(close,macdp1,macdp2,macdp3),lookahead=barmerge.lookahead_on)
|
||
|
|
// log.info(str.tostring(syminfo.tickerid)+str.tostring(histLine[0]))
|
||
|
|
timezone_input = input("Asia/Kolkata", title="Timezone")
|
||
|
|
// log.info(timezone_input)
|
||
|
|
if(hour==15 and minute==15)
|
||
|
|
strategy.close_all(comment = "DAY EXIT",alert_message = "X-D")
|
||
|
|
else if(hour==9 and minute==30)
|
||
|
|
if(longcondition or histLine[1]>0)
|
||
|
|
strategy.entry(id= "Long", direction=strategy.long, comment = "DL",alert_message = "L")
|
||
|
|
else if(shortCondition or histLine[1]<0)
|
||
|
|
strategy.entry(id= "Short", direction=strategy.short, comment = "DS",alert_message = "S")
|
||
|
|
else
|
||
|
|
if(longcondition)
|
||
|
|
strategy.close("Short",comment = "X-S", alert_message = "X-S")
|
||
|
|
if(histLine[1]>0)
|
||
|
|
strategy.entry(id= "Long", direction=strategy.long, comment = "L",alert_message = "L")
|
||
|
|
else if(shortCondition)
|
||
|
|
strategy.close("Long",comment = "X-L",alert_message = "X-L")
|
||
|
|
if(histLine[1]<0)
|
||
|
|
strategy.entry(id= "Short", direction=strategy.short, comment = "S",alert_message = "S")
|
||
|
|
|
||
|
|
|
||
|
|
// plot(macdLine, title = "MACD", color = #2962FF)
|
||
|
|
// plot(signalLine, title = "Signal", color = #FF6D00)
|
||
|
|
// 8, 21, 5
|
||
|
|
// 8,13,9
|
||
|
|
// 12,26,9
|
||
|
|
// 1--> 3, 17, 5
|
||
|
|
// 3, 10, 16
|
||
|
|
// log.info(str.tostring(syminfo.tickerid)+str.tostring(histLine[0]))
|
||
|
|
// /////////----------------METHOD 1-----------------////////////////
|
||
|
|
// if(longcondition)
|
||
|
|
// if(strategy.opentrades>0)
|
||
|
|
// strategy.close("Long","Prev Exit", immediately = true)
|
||
|
|
// if( histLine[0] > 0.1)
|
||
|
|
// strategy.entry(id= "Long", direction=strategy.long, comment = "update long")
|
||
|
|
|
||
|
|
|
||
|
|
// else if(shortCondition and strategy.openprofit<=0.1)
|
||
|
|
// strategy.close("Long",comment = "Close",immediately = true)
|
||
|
|
// /////////----------------METHOD 2-----------------////////////////
|
||
|
|
// if(longcondition)
|
||
|
|
// if(histLine[0] > 0)
|
||
|
|
// strategy.entry(id= "Long", direction=strategy.long, comment = "update long" )
|
||
|
|
// strategy.exit("Long", loss = close*0.2)
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
// else if(shortCondition )
|
||
|
|
// strategy.close("Long",comment = "Close",immediately = true)
|
||
|
|
// /////////----------------METHOD 3-----------------////////////////
|
||
|
|
|
||
|
|
|
||
|
|
```
|
||
|
|
|
||
|
|
> Detail
|
||
|
|
|
||
|
|
https://www.fmz.com/strategy/444352
|
||
|
|
|
||
|
|
> Last Modified
|
||
|
|
|
||
|
|
2024-03-11 11:33:47
|