138 lines
8.4 KiB
Markdown
138 lines
8.4 KiB
Markdown

|
|
||
|
|
> Name
|
||
|
|
|
||
|
|
双均线交叉风险收益智能调控策略-Dual-EMA-Crossover-Strategy-with-Smart-Risk-Reward-Control
|
||
|
|
|
||
|
|
> Author
|
||
|
|
|
||
|
|
ChaoZhang
|
||
|
|
|
||
|
|
> Strategy Description
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
[trans]
|
||
|
|
#### 概述
|
||
|
|
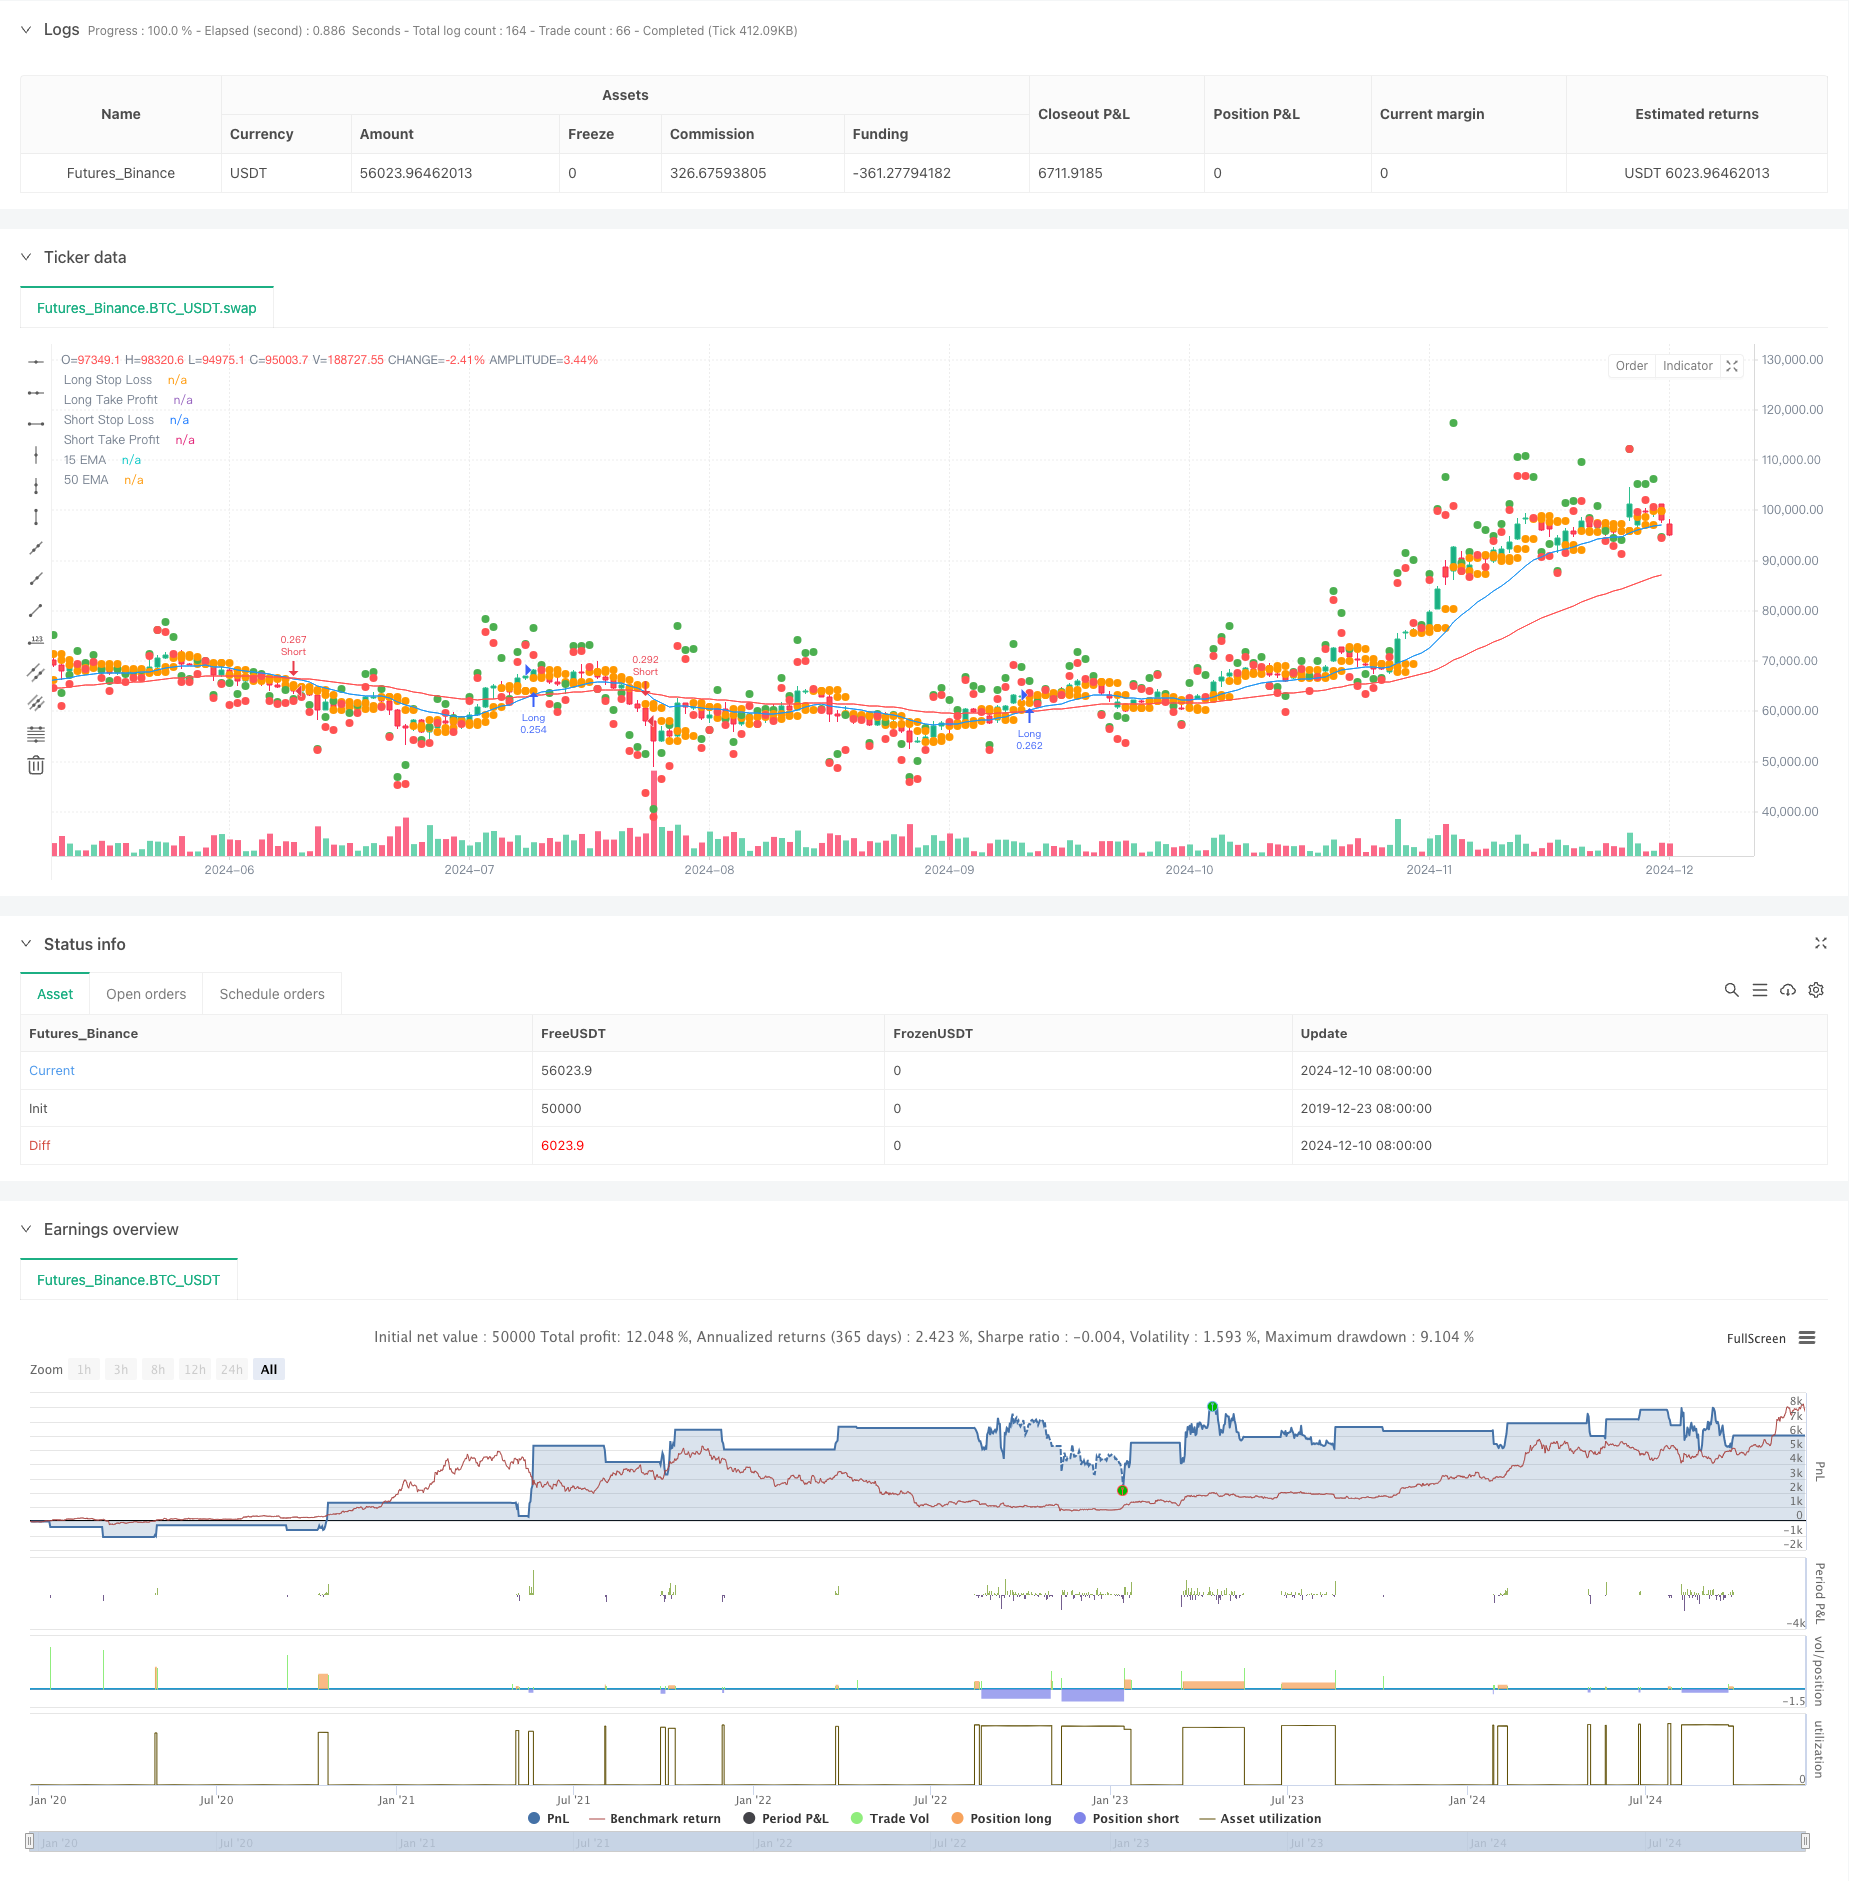
这是一个基于15周期和50周期指数移动平均线(EMA)交叉的交易策略。策略通过智能设置止损和获利点,实现了风险收益比的最优控制。该策略不仅能够捕捉趋势反转信号,还能够根据市场波动自动调整交易参数,从而提高策略的稳定性和盈利能力。
|
||
|
|
|
||
|
|
#### 策略原理
|
||
|
|
策略的核心逻辑基于快速EMA(15周期)和慢速EMA(50周期)的交叉信号。当快线上穿慢线时,系统产生做多信号;当快线下穿慢线时,系统产生做空信号。为了优化风险管理,策略采用了动态止损设置方法,即以前2根K线的最低开盘价作为多头止损点,最高开盘价作为空头止损点。获利目标则通过风险的2倍来设定,确保了良好的风险收益比。策略默认使用账户30%的资金进行交易,这种资金管理方式有助于控制风险。
|
||
|
|
|
||
|
|
#### 策略优势
|
||
|
|
1. 动态风险管理:通过实时计算止损位置,策略能够根据市场波动自动调整风险参数。
|
||
|
|
2. 优化的风险收益比:通过将获利目标设置为止损距离的2倍,确保了每笔交易都具有合理的盈利空间。
|
||
|
|
3. 稳健的资金管理:使用账户30%的资金进行交易,既保证了收益潜力,又避免了过度风险。
|
||
|
|
4. 双向交易机会:策略可以捕捉多空两个方向的交易机会,提高了交易频率和盈利机会。
|
||
|
|
5. 可视化辅助:通过在图表上标记止损和获利位置,交易者可以直观地监控交易状态。
|
||
|
|
|
||
|
|
#### 策略风险
|
||
|
|
1. 震荡市场风险:在横盘震荡市场中,均线交叉信号可能产生虚假信号,导致连续止损。
|
||
|
|
2. 滑点风险:在市场快速波动时,实际成交价格可能与理想价格存在较大偏差。
|
||
|
|
3. 资金管理风险:固定使用30%的资金可能在某些市场条件下过于激进。
|
||
|
|
4. 止损设置风险:基于前2根K线设置的止损可能在极端市场条件下不够灵活。
|
||
|
|
|
||
|
|
#### 策略优化方向
|
||
|
|
1. 引入趋势过滤器:可以添加额外的趋势确认指标,如ADX或趋势强度指标,以过滤弱势信号。
|
||
|
|
2. 动态资金管理:可以根据市场波动率自动调整仓位大小,使策略更具适应性。
|
||
|
|
3. 优化止损方法:可以考虑引入ATR指标来设置止损,使止损更符合市场波动特征。
|
||
|
|
4. 增加时间过滤:添加交易时间段过滤,避开波动剧烈或流动性不足的时段。
|
||
|
|
5. 引入成交量确认:将成交量作为交易信号的确认指标,提高信号可靠性。
|
||
|
|
|
||
|
|
#### 总结
|
||
|
|
这是一个结构完整、逻辑清晰的均线交叉策略。通过将经典的技术分析方法与现代风险管理技术相结合,策略实现了较好的风险收益特征。虽然存在一定的优化空间,但策略的基本框架具有良好的实用性和扩展性。通过建议的优化方向,策略的表现有望得到进一步提升。 ||
|
||
|
|
|
||
|
|
#### Overview
|
||
|
|
This is a trading strategy based on the crossover of 15-period and 50-period Exponential Moving Averages (EMA). The strategy implements intelligent stop-loss and take-profit levels to optimize risk-reward control. It not only captures trend reversal signals but also automatically adjusts trading parameters based on market volatility, thereby improving strategy stability and profitability.
|
||
|
|
|
||
|
|
#### Strategy Principle
|
||
|
|
The core logic is based on crossover signals between the fast EMA (15-period) and slow EMA (50-period). A long signal is generated when the fast line crosses above the slow line, and a short signal when the fast line crosses below. For risk management optimization, the strategy employs a dynamic stop-loss setting method, using the lowest opening price of the previous 2 candles as the long stop-loss and the highest opening price as the short stop-loss. The profit target is set at twice the risk, ensuring a favorable risk-reward ratio. The strategy uses 30% of the account equity for trading, which helps control risk exposure.
|
||
|
|
|
||
|
|
#### Strategy Advantages
|
||
|
|
1. Dynamic Risk Management: The strategy automatically adjusts risk parameters based on market volatility through real-time stop-loss calculations.
|
||
|
|
2. Optimized Risk-Reward Ratio: Setting profit targets at twice the stop-loss distance ensures reasonable profit potential for each trade.
|
||
|
|
3. Robust Money Management: Using 30% of account equity for trading maintains a balance between profit potential and risk control.
|
||
|
|
4. Bi-directional Trading Opportunities: The strategy captures both long and short trading opportunities, increasing trading frequency and profit potential.
|
||
|
|
5. Visual Assistance: Stop-loss and take-profit levels are marked on the chart, allowing traders to monitor trade status intuitively.
|
||
|
|
|
||
|
|
#### Strategy Risks
|
||
|
|
1. Choppy Market Risk: During sideways markets, EMA crossover signals may generate false signals leading to consecutive losses.
|
||
|
|
2. Slippage Risk: During rapid market movements, actual execution prices may significantly deviate from intended prices.
|
||
|
|
3. Money Management Risk: Using a fixed 30% of equity might be too aggressive under certain market conditions.
|
||
|
|
4. Stop-Loss Setting Risk: Stop-losses based on the previous 2 candles might not be flexible enough in extreme market conditions.
|
||
|
|
|
||
|
|
#### Strategy Optimization Directions
|
||
|
|
1. Implement Trend Filters: Add additional trend confirmation indicators like ADX or trend strength indicators to filter weak signals.
|
||
|
|
2. Dynamic Position Sizing: Automatically adjust position size based on market volatility for better adaptability.
|
||
|
|
3. Optimize Stop-Loss Method: Consider incorporating ATR indicator for stop-loss settings to better reflect market volatility characteristics.
|
||
|
|
4. Add Time Filters: Implement trading time filters to avoid periods of high volatility or low liquidity.
|
||
|
|
5. Include Volume Confirmation: Use volume as a confirmation indicator to improve signal reliability.
|
||
|
|
|
||
|
|
#### Summary
|
||
|
|
This is a well-structured EMA crossover strategy with clear logic. By combining classical technical analysis methods with modern risk management techniques, the strategy achieves favorable risk-reward characteristics. While there is room for optimization, the basic framework demonstrates good practicality and extensibility. Through the suggested optimization directions, the strategy's performance can be further enhanced.[/trans]
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
> Source (PineScript)
|
||
|
|
|
||
|
|
``` pinescript
|
||
|
|
/*backtest
|
||
|
|
start: 2019-12-23 08:00:00
|
||
|
|
end: 2024-12-11 08:00:00
|
||
|
|
period: 1d
|
||
|
|
basePeriod: 1d
|
||
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
||
|
|
*/
|
||
|
|
|
||
|
|
//@version=5
|
||
|
|
strategy("EMA Cross - Any Direction", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=30)
|
||
|
|
|
||
|
|
// Input for EMAs
|
||
|
|
ema_short_length = input(15, title="Short EMA Length")
|
||
|
|
ema_long_length = input(50, title="Long EMA Length")
|
||
|
|
|
||
|
|
// Calculate EMAs
|
||
|
|
ema_short = ta.ema(close, ema_short_length)
|
||
|
|
ema_long = ta.ema(close, ema_long_length)
|
||
|
|
|
||
|
|
// Plot EMAs
|
||
|
|
plot(ema_short, color=color.blue, title="15 EMA")
|
||
|
|
plot(ema_long, color=color.red, title="50 EMA")
|
||
|
|
|
||
|
|
// Entry Conditions (Any EMA Cross)
|
||
|
|
cross_condition = ta.crossover(ema_short, ema_long) or ta.crossunder(ema_short, ema_long)
|
||
|
|
|
||
|
|
// Determine Trade Direction
|
||
|
|
is_long = ta.crossover(ema_short, ema_long)
|
||
|
|
is_short = ta.crossunder(ema_short, ema_long)
|
||
|
|
|
||
|
|
// Stop Loss and Take Profit
|
||
|
|
long_stop_loss = ta.lowest(open[1], 2) // Lowest open of the last 2 candles
|
||
|
|
short_stop_loss = ta.highest(open[1], 2) // Highest open of the last 2 candles
|
||
|
|
long_take_profit = close + 2 * (close - long_stop_loss)
|
||
|
|
short_take_profit = close - 2 * (short_stop_loss - close)
|
||
|
|
|
||
|
|
// Execute Trades
|
||
|
|
if (cross_condition)
|
||
|
|
if (is_long)
|
||
|
|
strategy.entry("Long", strategy.long)
|
||
|
|
strategy.exit("Exit Long", "Long", stop=long_stop_loss, limit=long_take_profit)
|
||
|
|
else if (is_short)
|
||
|
|
strategy.entry("Short", strategy.short)
|
||
|
|
strategy.exit("Exit Short", "Short", stop=short_stop_loss, limit=short_take_profit)
|
||
|
|
|
||
|
|
// Plot Stop Loss and Take Profit Levels
|
||
|
|
plot(long_stop_loss, color=color.orange, title="Long Stop Loss", style=plot.style_circles, linewidth=2)
|
||
|
|
plot(long_take_profit, color=color.green, title="Long Take Profit", style=plot.style_circles, linewidth=2)
|
||
|
|
plot(short_stop_loss, color=color.orange, title="Short Stop Loss", style=plot.style_circles, linewidth=2)
|
||
|
|
plot(short_take_profit, color=color.red, title="Short Take Profit", style=plot.style_circles, linewidth=2)
|
||
|
|
|
||
|
|
```
|
||
|
|
|
||
|
|
> Detail
|
||
|
|
|
||
|
|
https://www.fmz.com/strategy/474958
|
||
|
|
|
||
|
|
> Last Modified
|
||
|
|
|
||
|
|
2024-12-13 10:30:17
|