315 lines
18 KiB
Markdown
315 lines
18 KiB
Markdown

|
|
||
|
|
> Name
|
||
|
|
|
||
|
|
双均线交叉动态止盈止损量化策略-Dynamic-Dual-EMA-Crossover-Strategy-with-Adaptive-Profit-Loss-Control
|
||
|
|
|
||
|
|
> Author
|
||
|
|
|
||
|
|
ChaoZhang
|
||
|
|
|
||
|
|
> Strategy Description
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
[trans]
|
||
|
|
#### 概述
|
||
|
|
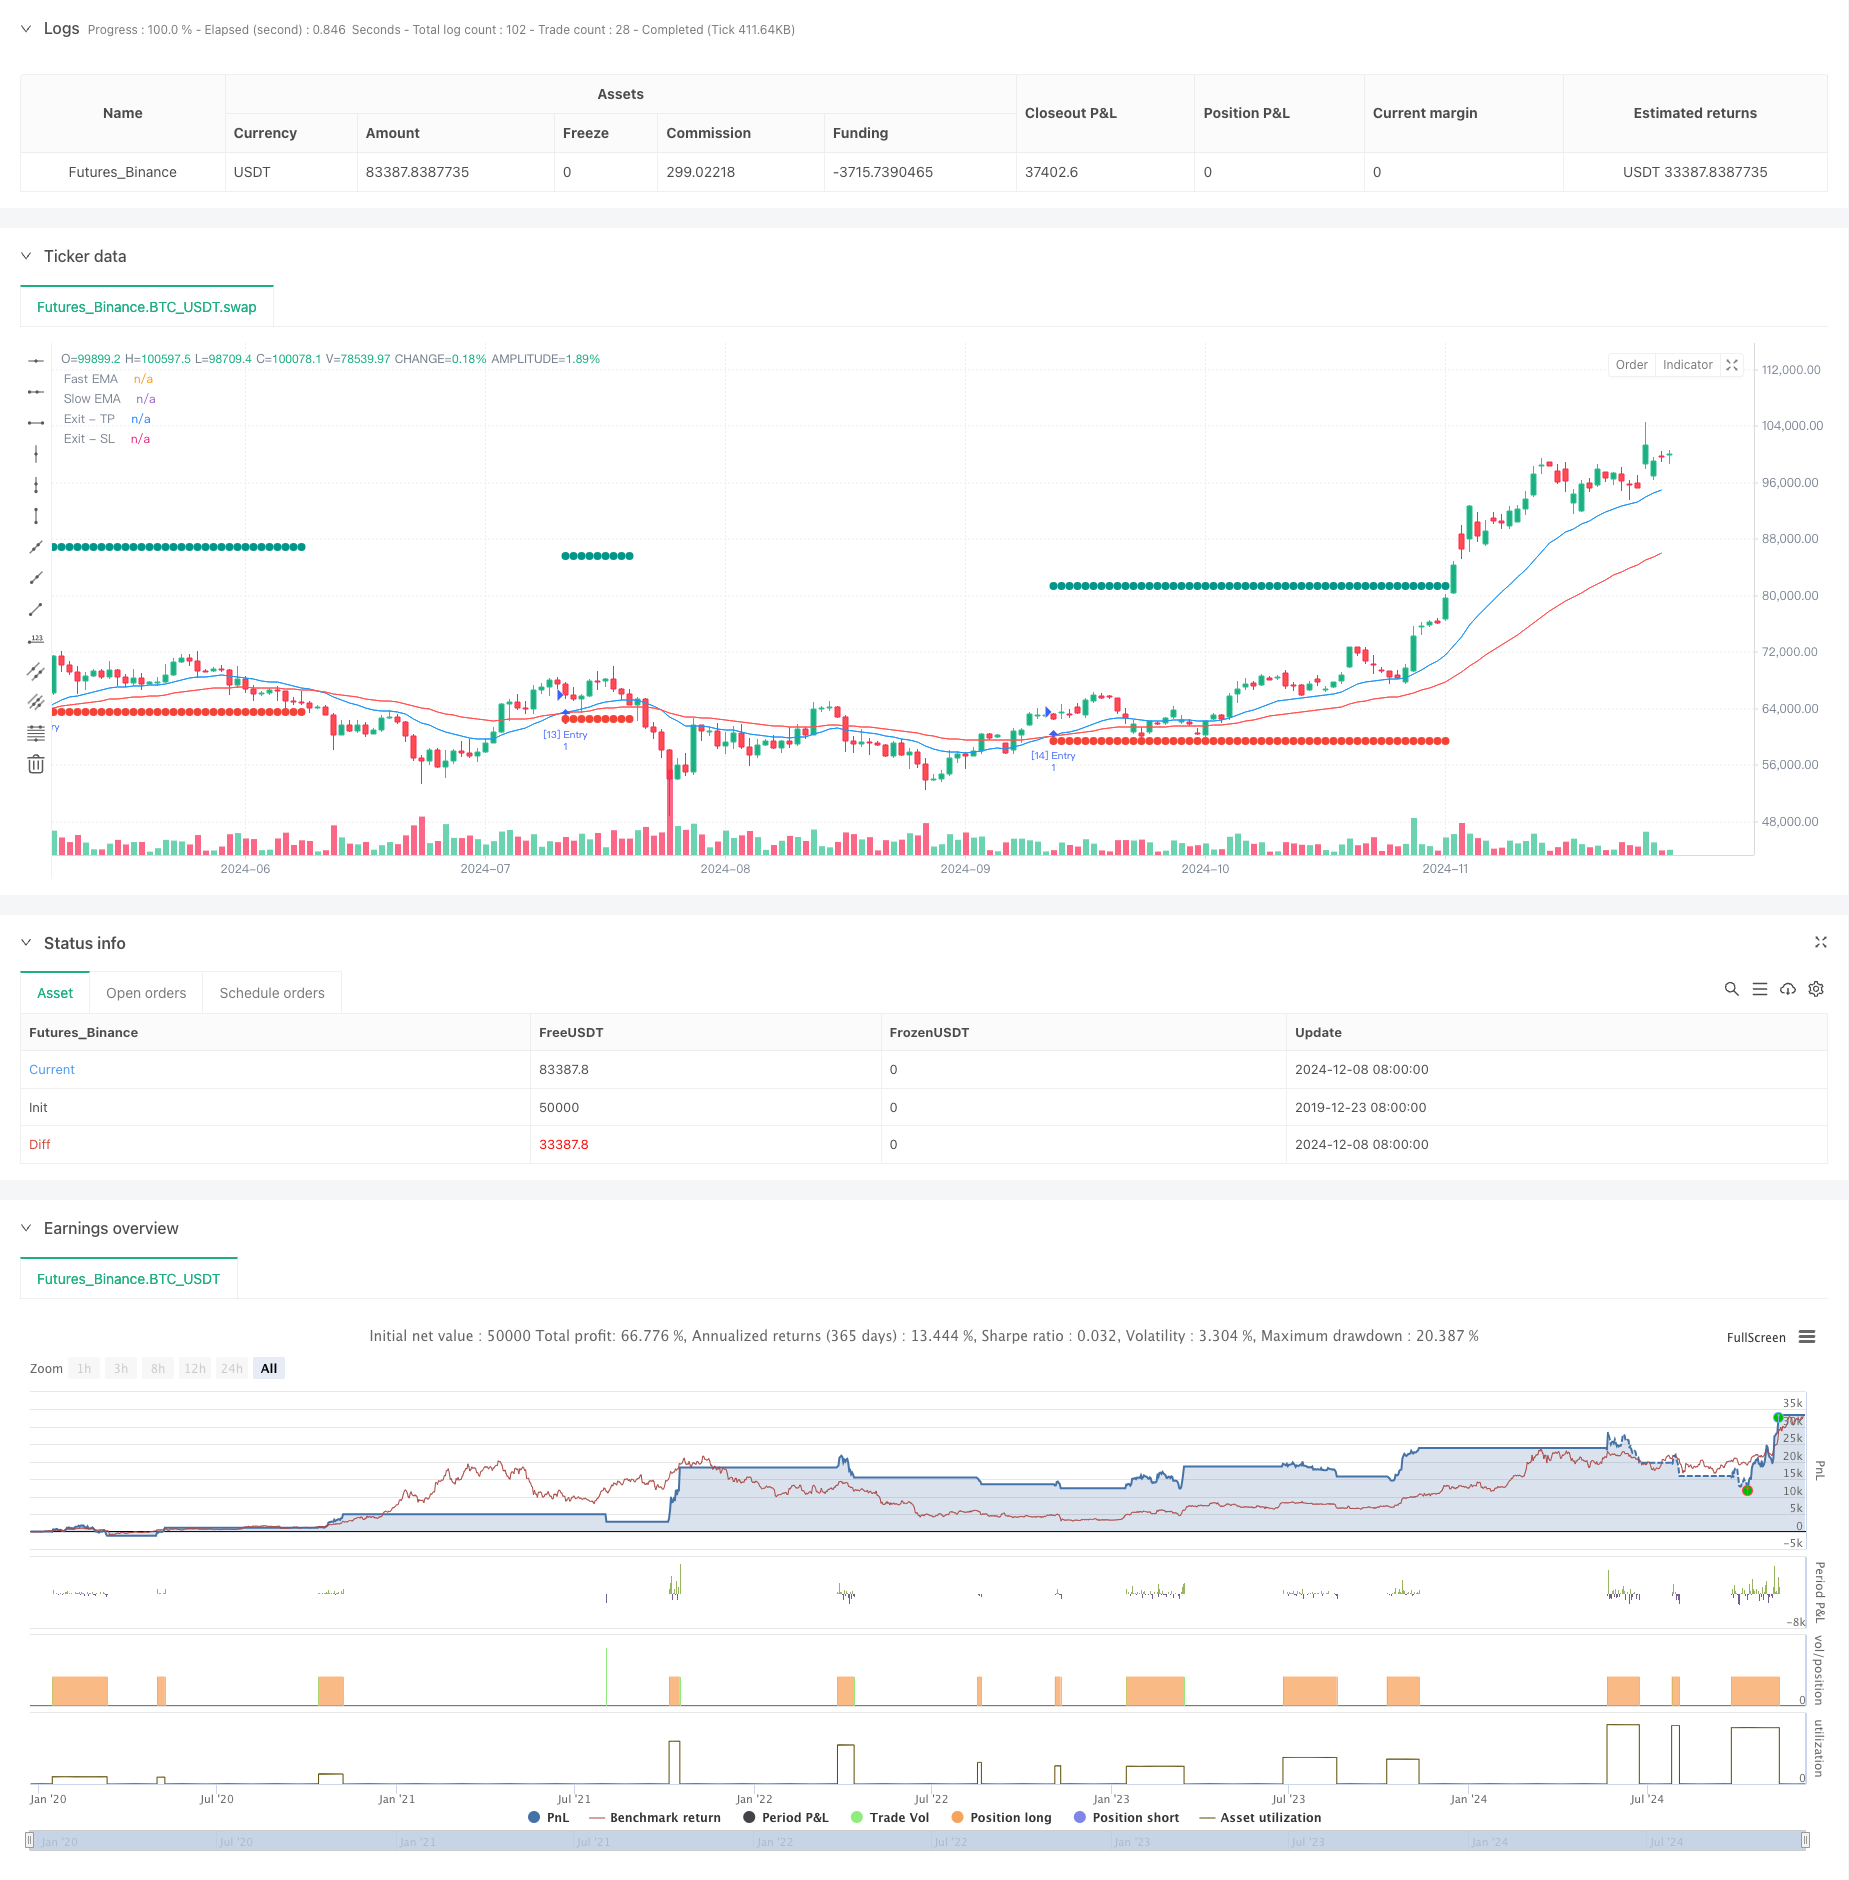
这是一个基于双均线交叉信号的量化交易策略,通过快速指数移动平均线(EMA)和慢速指数移动平均线(EMA)的交叉来判断市场趋势,同时结合动态止盈止损控制来管理风险。策略采用百分比仓位管理,默认使用10%的资金进行交易,通过设定动态的止盈和止损价格来保护利润和控制风险。
|
||
|
|
|
||
|
|
#### 策略原理
|
||
|
|
策略的核心逻辑是通过监测20周期和50周期的指数移动平均线(EMA)的交叉来识别趋势变化。当快速EMA向上穿越慢速EMA时,系统产生做多信号。每次开仓后,系统会根据入场价格自动设置止盈价格(入场价格的1.3倍)和止损价格(入场价格的0.95倍)。这种动态止盈止损的设计能够根据不同的市场环境自适应调整,提高策略的灵活性。
|
||
|
|
|
||
|
|
#### 策略优势
|
||
|
|
1. 信号稳定性强 - 使用EMA而非简单移动平均线(SMA),能够更快速地响应价格变化,同时又能过滤掉部分市场噪音。
|
||
|
|
2. 风险管理完善 - 采用动态止盈止损机制,止盈止损价格会随着入场价格的变化而调整。
|
||
|
|
3. 资金管理合理 - 使用固定比例仓位管理,避免了全仓操作的高风险。
|
||
|
|
4. 自动化程度高 - 从信号生成到仓位管理都实现了自动化,减少了人为干预。
|
||
|
|
5. 适应性强 - 策略可以适应不同的市场环境,参数可根据实际情况灵活调整。
|
||
|
|
|
||
|
|
#### 策略风险
|
||
|
|
1. 均线滞后性 - EMA虽然反应较快,但仍存在一定的滞后性,可能导致入场时机略有延迟。
|
||
|
|
2. 震荡市不适用 - 在市场横盘震荡时,可能会产生频繁的假突破信号。
|
||
|
|
3. 固定倍数止盈止损 - 使用固定的倍数设置止盈止损,可能不适合所有市场环境。
|
||
|
|
4. 回撤风险 - 在剧烈波动的市场中,5%的止损可能不足以应对大幅波动。
|
||
|
|
|
||
|
|
#### 策略优化方向
|
||
|
|
1. 引入波动率指标 - 建议添加ATR指标来动态调整止盈止损倍数,使其更适应市场波动。
|
||
|
|
2. 增加趋势确认 - 可以结合RSI、MACD等指标来过滤交易信号,提高胜率。
|
||
|
|
3. 优化仓位管理 - 可以根据市场波动率动态调整仓位大小,实现更精细的风险控制。
|
||
|
|
4. 添加时间过滤 - 考虑增加交易时间窗口的限制,避开波动较大的时段。
|
||
|
|
5. 完善止盈机制 - 可以实现移动止盈,在行情持续向好时获取更多收益。
|
||
|
|
|
||
|
|
#### 总结
|
||
|
|
这是一个设计合理、逻辑清晰的趋势跟踪策略,通过双均线交叉捕捉趋势,使用动态止盈止损来管理风险。策略的优势在于操作规则明确、风险可控,适合作为中长期交易系统的基础框架。通过添加更多的过滤条件和优化止盈止损机制,该策略还有较大的优化空间。建议交易者在实盘使用前,先通过回测验证策略在不同市场环境下的表现,并根据自己的风险承受能力调整参数。 ||
|
||
|
|
|
||
|
|
#### Overview
|
||
|
|
This is a quantitative trading strategy based on dual EMA crossover signals, which uses the intersection of fast and slow Exponential Moving Averages (EMA) to determine market trends, combined with dynamic take-profit and stop-loss controls for risk management. The strategy employs percentage-based position management, defaulting to 10% of capital per trade, and implements dynamic profit targets and stop-loss levels for protection.
|
||
|
|
|
||
|
|
#### Strategy Principles
|
||
|
|
The core logic revolves around monitoring crossovers between 20-period and 50-period EMAs to identify trend changes. A long position is initiated when the fast EMA crosses above the slow EMA. Upon entry, the system automatically sets take-profit levels (1.3 times entry price) and stop-loss levels (0.95 times entry price). This dynamic profit/loss control design adapts to different market conditions, enhancing strategy flexibility.
|
||
|
|
|
||
|
|
#### Strategy Advantages
|
||
|
|
1. Signal Stability - Uses EMA instead of SMA, providing faster response to price changes while filtering market noise.
|
||
|
|
2. Comprehensive Risk Management - Implements dynamic take-profit and stop-loss mechanisms that adjust with entry prices.
|
||
|
|
3. Rational Capital Management - Uses fixed proportion position sizing, avoiding high-risk full position trading.
|
||
|
|
4. High Automation - Automates everything from signal generation to position management, reducing human intervention.
|
||
|
|
5. Strong Adaptability - Strategy can adapt to different market conditions with adjustable parameters.
|
||
|
|
|
||
|
|
#### Strategy Risks
|
||
|
|
1. EMA Lag - Despite being faster than SMA, EMA still has some inherent lag, potentially causing delayed entries.
|
||
|
|
2. Poor Performance in Ranging Markets - May generate frequent false breakout signals during sideways market conditions.
|
||
|
|
3. Fixed Multiplier for Profit/Loss - Using fixed multipliers for take-profit and stop-loss may not suit all market conditions.
|
||
|
|
4. Drawdown Risk - 5% stop-loss might not be sufficient in highly volatile markets.
|
||
|
|
|
||
|
|
#### Optimization Directions
|
||
|
|
1. Incorporate Volatility Indicators - Suggest adding ATR to dynamically adjust profit/loss multipliers for better market adaptation.
|
||
|
|
2. Add Trend Confirmation - Consider incorporating RSI, MACD for signal filtering to improve win rate.
|
||
|
|
3. Optimize Position Sizing - Implement dynamic position sizing based on market volatility for finer risk control.
|
||
|
|
4. Add Time Filters - Consider adding trading time windows to avoid highly volatile periods.
|
||
|
|
5. Enhance Profit-Taking - Implement trailing stops to capture more profit in strong trends.
|
||
|
|
|
||
|
|
#### Conclusion
|
||
|
|
This is a well-designed trend-following strategy with clear logic, using dual EMA crossovers for trend capture and dynamic profit/loss controls for risk management. The strategy's strengths lie in its clear rules and controlled risk, making it suitable as a foundation for medium to long-term trading systems. There's significant room for optimization through additional filters and enhanced profit/loss mechanisms. Traders should validate the strategy through backtesting across different market conditions and adjust parameters according to their risk tolerance before live implementation.[/trans]
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
> Source (PineScript)
|
||
|
|
|
||
|
|
``` pinescript
|
||
|
|
/*backtest
|
||
|
|
start: 2019-12-23 08:00:00
|
||
|
|
end: 2024-12-09 08:00:00
|
||
|
|
period: 1d
|
||
|
|
basePeriod: 1d
|
||
|
|
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
|
||
|
|
*/
|
||
|
|
|
||
|
|
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
|
||
|
|
// © Pineify
|
||
|
|
|
||
|
|
//======================================================================//
|
||
|
|
// ____ _ _ __ //
|
||
|
|
// | _ \(_)_ __ ___(_)/ _|_ _ //
|
||
|
|
// | |_) | | '_ \ / _ \ | |_| | | | //
|
||
|
|
// | __/| | | | | __/ | _| |_| | //
|
||
|
|
// |_| |_|_| |_|\___|_|_| \__, | //
|
||
|
|
// |___/ //
|
||
|
|
//======================================================================//
|
||
|
|
|
||
|
|
//@version=5
|
||
|
|
strategy(title="TQQQ EMA Strategy", overlay=true)
|
||
|
|
|
||
|
|
//#region —————————————————————————————————————————————————— Common Dependence
|
||
|
|
|
||
|
|
p_comm_time_range_to_unix_time(string time_range, int date_time = time, string timezone = syminfo.timezone) =>
|
||
|
|
int start_unix_time = na
|
||
|
|
int end_unix_time = na
|
||
|
|
int start_time_hour = na
|
||
|
|
int start_time_minute = na
|
||
|
|
int end_time_hour = na
|
||
|
|
int end_time_minute = na
|
||
|
|
if str.length(time_range) == 11
|
||
|
|
// Format: hh:mm-hh:mm
|
||
|
|
start_time_hour := math.floor(str.tonumber(str.substring(time_range, 0, 2)))
|
||
|
|
start_time_minute := math.floor(str.tonumber(str.substring(time_range, 3, 5)))
|
||
|
|
end_time_hour := math.floor(str.tonumber(str.substring(time_range, 6, 8)))
|
||
|
|
end_time_minute := math.floor(str.tonumber(str.substring(time_range, 9, 11)))
|
||
|
|
else if str.length(time_range) == 9
|
||
|
|
// Format: hhmm-hhmm
|
||
|
|
start_time_hour := math.floor(str.tonumber(str.substring(time_range, 0, 2)))
|
||
|
|
start_time_minute := math.floor(str.tonumber(str.substring(time_range, 2, 4)))
|
||
|
|
end_time_hour := math.floor(str.tonumber(str.substring(time_range, 5, 7)))
|
||
|
|
end_time_minute := math.floor(str.tonumber(str.substring(time_range, 7, 9)))
|
||
|
|
start_unix_time := timestamp(timezone, year(date_time, timezone), month(date_time, timezone), dayofmonth(date_time, timezone), start_time_hour, start_time_minute, 0)
|
||
|
|
end_unix_time := timestamp(timezone, year(date_time, timezone), month(date_time, timezone), dayofmonth(date_time, timezone), end_time_hour, end_time_minute, 0)
|
||
|
|
[start_unix_time, end_unix_time]
|
||
|
|
|
||
|
|
p_comm_time_range_to_start_unix_time(string time_range, int date_time = time, string timezone = syminfo.timezone) =>
|
||
|
|
int start_time_hour = na
|
||
|
|
int start_time_minute = na
|
||
|
|
if str.length(time_range) == 11
|
||
|
|
// Format: hh:mm-hh:mm
|
||
|
|
start_time_hour := math.floor(str.tonumber(str.substring(time_range, 0, 2)))
|
||
|
|
start_time_minute := math.floor(str.tonumber(str.substring(time_range, 3, 5)))
|
||
|
|
else if str.length(time_range) == 9
|
||
|
|
// Format: hhmm-hhmm
|
||
|
|
start_time_hour := math.floor(str.tonumber(str.substring(time_range, 0, 2)))
|
||
|
|
start_time_minute := math.floor(str.tonumber(str.substring(time_range, 2, 4)))
|
||
|
|
timestamp(timezone, year(date_time, timezone), month(date_time, timezone), dayofmonth(date_time, timezone), start_time_hour, start_time_minute, 0)
|
||
|
|
|
||
|
|
p_comm_time_range_to_end_unix_time(string time_range, int date_time = time, string timezone = syminfo.timezone) =>
|
||
|
|
int end_time_hour = na
|
||
|
|
int end_time_minute = na
|
||
|
|
if str.length(time_range) == 11
|
||
|
|
end_time_hour := math.floor(str.tonumber(str.substring(time_range, 6, 8)))
|
||
|
|
end_time_minute := math.floor(str.tonumber(str.substring(time_range, 9, 11)))
|
||
|
|
else if str.length(time_range) == 9
|
||
|
|
end_time_hour := math.floor(str.tonumber(str.substring(time_range, 5, 7)))
|
||
|
|
end_time_minute := math.floor(str.tonumber(str.substring(time_range, 7, 9)))
|
||
|
|
timestamp(timezone, year(date_time, timezone), month(date_time, timezone), dayofmonth(date_time, timezone), end_time_hour, end_time_minute, 0)
|
||
|
|
|
||
|
|
p_comm_timeframe_to_seconds(simple string tf) =>
|
||
|
|
float seconds = 0
|
||
|
|
tf_lower = str.lower(tf)
|
||
|
|
value = str.tonumber(str.substring(tf_lower, 0, str.length(tf_lower) - 1))
|
||
|
|
if str.endswith(tf_lower, 's')
|
||
|
|
seconds := value
|
||
|
|
else if str.endswith(tf_lower, 'd')
|
||
|
|
seconds := value * 86400
|
||
|
|
else if str.endswith(tf_lower, 'w')
|
||
|
|
seconds := value * 604800
|
||
|
|
else if str.endswith(tf_lower, 'm')
|
||
|
|
seconds := value * 2592000
|
||
|
|
else
|
||
|
|
seconds := str.tonumber(tf_lower) * 60
|
||
|
|
seconds
|
||
|
|
|
||
|
|
p_custom_sources() =>
|
||
|
|
[open, high, low, close, volume]
|
||
|
|
|
||
|
|
//#endregion —————————————————————————————————————————————————————————————————
|
||
|
|
|
||
|
|
|
||
|
|
//#region —————————————————————————————————————————————————— Ta Dependence
|
||
|
|
|
||
|
|
|
||
|
|
//#endregion —————————————————————————————————————————————————————————————
|
||
|
|
|
||
|
|
|
||
|
|
//#region —————————————————————————————————————————————————— Constants
|
||
|
|
|
||
|
|
// Input Groups
|
||
|
|
string P_GP_1 = ""
|
||
|
|
|
||
|
|
//#endregion —————————————————————————————————————————————————————————
|
||
|
|
|
||
|
|
|
||
|
|
//#region —————————————————————————————————————————————————— Inputs
|
||
|
|
|
||
|
|
// Default
|
||
|
|
int p_inp_1 = input.int(defval=20, title="Fast EMA Length", group=P_GP_1)
|
||
|
|
int p_inp_2 = input.int(defval=50, title="Slow EMA Length", group=P_GP_1)
|
||
|
|
float p_inp_3 = input.float(defval=1.3, title="Take Profit Price Multiplier", group=P_GP_1, step=0.01)
|
||
|
|
float p_inp_4 = input.float(defval=0.95, title="Stop Loss Price Multiplier", group=P_GP_1, step=0.01)
|
||
|
|
|
||
|
|
|
||
|
|
//#endregion ———————————————————————————————————————————————————————
|
||
|
|
|
||
|
|
|
||
|
|
//#region —————————————————————————————————————————————————— Price Data
|
||
|
|
|
||
|
|
|
||
|
|
|
||
|
|
//#endregion ———————————————————————————————————————————————————————————
|
||
|
|
|
||
|
|
|
||
|
|
//#region —————————————————————————————————————————————————— Indicators
|
||
|
|
|
||
|
|
p_ind_1 = ta.ema(close, p_inp_1) // Fast EMA
|
||
|
|
p_ind_2 = ta.ema(close, p_inp_2) // Slow EMA
|
||
|
|
|
||
|
|
|
||
|
|
//#endregion ———————————————————————————————————————————————————————————
|
||
|
|
|
||
|
|
|
||
|
|
//#region —————————————————————————————————————————————————— Conditions
|
||
|
|
|
||
|
|
p_cond_1 = (ta.crossover(p_ind_1, p_ind_2))
|
||
|
|
|
||
|
|
|
||
|
|
//#endregion ———————————————————————————————————————————————————————————
|
||
|
|
|
||
|
|
|
||
|
|
//#region —————————————————————————————————————————————————— Strategy
|
||
|
|
|
||
|
|
// Strategy Order Variables
|
||
|
|
string p_st_name_1 = "Entry"
|
||
|
|
string p_st_name_2 = "Exit"
|
||
|
|
var float p_st_name_2_tp = na
|
||
|
|
var bool p_st_name_2_tp_can_drawing = true
|
||
|
|
var float p_st_name_2_sl = na
|
||
|
|
var bool p_st_name_2_sl_can_drawing = true
|
||
|
|
|
||
|
|
// Strategy Global
|
||
|
|
open_trades_number = strategy.opentrades
|
||
|
|
pre_bar_open_trades_number = na(open_trades_number[1]) ? 0 : open_trades_number[1]
|
||
|
|
var p_entry_order_id = 1
|
||
|
|
p_can_place_entry_order() =>
|
||
|
|
strategy.equity > 0
|
||
|
|
get_entry_id_name(int current_order_id, string name) =>
|
||
|
|
"[" + str.tostring(current_order_id) + "] " + name
|
||
|
|
is_entry_order(string order_id, string name) =>
|
||
|
|
str.startswith(order_id, "[") and str.endswith(order_id, "] " + name)
|
||
|
|
get_open_trades_entry_ids() =>
|
||
|
|
int p_open_trades_count = strategy.opentrades
|
||
|
|
string[] p_entry_ids = array.new_string(0, "")
|
||
|
|
if p_open_trades_count > 0
|
||
|
|
for i = 0 to p_open_trades_count - 1
|
||
|
|
array.push(p_entry_ids, strategy.opentrades.entry_id(i))
|
||
|
|
p_entry_ids
|
||
|
|
|
||
|
|
// Entry (Entry)
|
||
|
|
if p_cond_1 and p_can_place_entry_order()
|
||
|
|
p_st_name_1_id = get_entry_id_name(p_entry_order_id, p_st_name_1)
|
||
|
|
p_entry_order_id := p_entry_order_id + 1
|
||
|
|
string entry_message = ""
|
||
|
|
strategy.entry(id=p_st_name_1_id, direction=strategy.long, alert_message=entry_message, comment=p_st_name_1_id)
|
||
|
|
|
||
|
|
// TP/SL Exit (Exit)
|
||
|
|
float p_st_name_2_limit = close * p_inp_3
|
||
|
|
if p_st_name_2_tp_can_drawing
|
||
|
|
p_st_name_2_tp_can_drawing := false
|
||
|
|
p_st_name_2_tp := p_st_name_2_limit
|
||
|
|
float p_st_name_2_stop = close * p_inp_4
|
||
|
|
if p_st_name_2_sl_can_drawing
|
||
|
|
p_st_name_2_sl_can_drawing := false
|
||
|
|
p_st_name_2_sl := p_st_name_2_stop
|
||
|
|
string p_st_name_2_alert_message = ""
|
||
|
|
strategy.exit(id=p_st_name_1_id + "_0", from_entry=p_st_name_1_id, qty_percent=100, limit=p_st_name_2_limit, stop=p_st_name_2_stop, comment_profit=p_st_name_2 + " - TP", comment_loss=p_st_name_2 + " - SL", alert_message=p_st_name_2_alert_message)
|
||
|
|
|
||
|
|
|
||
|
|
if high >= p_st_name_2_tp or (pre_bar_open_trades_number > 0 and open_trades_number == 0)
|
||
|
|
p_st_name_2_tp_can_drawing := true
|
||
|
|
p_st_name_2_sl_can_drawing := true
|
||
|
|
p_st_name_2_tp := na
|
||
|
|
p_st_name_2_sl := na
|
||
|
|
plot(p_st_name_2_tp, title="Exit - TP", color=color.rgb(0, 150, 136, 0), linewidth=1, style = plot.style_circles)
|
||
|
|
if low <= p_st_name_2_sl or (pre_bar_open_trades_number > 0 and open_trades_number == 0)
|
||
|
|
p_st_name_2_sl_can_drawing := true
|
||
|
|
p_st_name_2_tp_can_drawing := true
|
||
|
|
p_st_name_2_sl := na
|
||
|
|
p_st_name_2_tp := na
|
||
|
|
plot(p_st_name_2_sl, title="Exit - SL", color=color.rgb(244, 67, 54, 0), linewidth=1, style = plot.style_circles)
|
||
|
|
//#endregion —————————————————————————————————————————————————————————
|
||
|
|
|
||
|
|
|
||
|
|
//#region —————————————————————————————————————————————————— Indicator Plots
|
||
|
|
|
||
|
|
// Fast EMA
|
||
|
|
plot(p_ind_1, "Fast EMA", color.rgb(33, 150, 243, 0), 1)
|
||
|
|
|
||
|
|
// Slow EMA
|
||
|
|
plot(p_ind_2, "Slow EMA", color.rgb(255, 82, 82, 0), 1)
|
||
|
|
|
||
|
|
//#endregion ————————————————————————————————————————————————————————————————
|
||
|
|
|
||
|
|
|
||
|
|
//#region —————————————————————————————————————————————————— Custom Plots
|
||
|
|
|
||
|
|
//#endregion —————————————————————————————————————————————————————————————
|
||
|
|
|
||
|
|
|
||
|
|
//#region —————————————————————————————————————————————————— Alert
|
||
|
|
|
||
|
|
//#endregion ——————————————————————————————————————————————————————
|
||
|
|
|
||
|
|
|
||
|
|
```
|
||
|
|
|
||
|
|
> Detail
|
||
|
|
|
||
|
|
https://www.fmz.com/strategy/474636
|
||
|
|
|
||
|
|
> Last Modified
|
||
|
|
|
||
|
|
2024-12-11 11:23:54
|